

Kimberly-Clark Corporation KMB is likely to witness a top and bottom-line decline when it reports third-quarter 2026 earnings on Nov. 5. The Zacks Consensus Estimate for revenues is pegged at $4.2 billion, indicating a 0.1% decrease from the prior-year quarter’s reported figure.
The consensus mark for earnings has moved up 4 cents in the past 30 days to $1.66 per share, which implies a 8.8% decrease from the figure reported a year ago. KMB has a trailing four-quarter earnings surprise of about 13%, on average.
Kimberly-Clark Corporation Price, Consensus and EPS Surprise
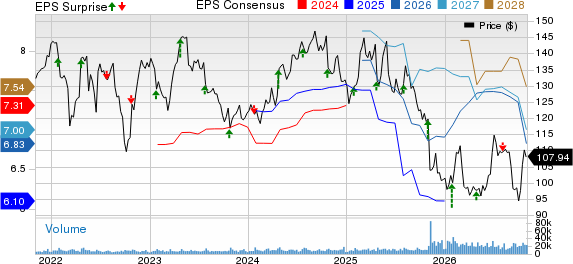
Kimberly-Clark Corporation price-consensus-eps-surprise-chart | Kimberly-Clark Corporation Quote
Factors Likely to Influence KMB’s Upcoming Results
Kimberly-Clark's third-quarter performance is likely to have been affected by a challenging consumer environment and moderating category growth. Cautious consumer spending and uneven purchasing patterns might have constrained sales momentum across its personal care categories. Increased competitive activity across certain personal care categories might also have weighed on performance. Disruptions in the company's China diaper business are also likely to have weighed on sales during the quarter.
Kimberly-Clark’s margins might have remained under pressure from elevated energy and other input costs, partly stemming from geopolitical tensions. Targeted pricing investments to strengthen consumer value propositions, alongside increased spending to support new product launches and brand-building activities, are likely to have added to cost pressures.
Nonetheless, Kimberly-Clark’s focus on innovation and operational efficiency is likely to have provided some support. New Huggies Skin Essentials diapers, upgraded Little Snugglers products and continued momentum in Viva and Goodnites are likely to have supported brand performance. Strong personal care demand across select international markets, aided by e-commerce and social commerce initiatives, alongside productivity savings from automation and supply-chain optimization, might have partly offset these headwinds.
Earnings Whispers for KMB Stock
Our proven model does not conclusively predict an earnings beat for Kimberly-Clark this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Kimberly-Clark carries a Zacks Rank #5 (Strong Sell) and has an Earnings ESP of -0.02%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Some Stocks With a Favorable Combination
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings this reporting cycle.
Dollar General Corporation DG has an Earnings ESP of +8.66% and currently carries a Zacks Rank of 2. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Dollar General’s upcoming quarter’s earnings per share is pegged at 1.40 cents, implying 9.4% year-over-year growth. The consensus estimate for Dollar General’s quarterly revenues is pegged at $11.1 billion, which indicates an increase of 4.5% from the figure reported in the prior-year quarter. DG has a trailing four-quarter earnings surprise of 19.1%, on average.
Burlington Stores, Inc. BURL currently has an Earnings ESP of +1.19% and a Zacks Rank of 3. The Zacks Consensus Estimate for Burlington Stores’ upcoming quarter’s earnings per share is pegged at $1.71, which implies a 5% decrease year over year.
The consensus estimate for Burlington Stores’ quarterly revenues is pegged at $3 billion, which indicates a surge of 10.5% from the figure reported in the prior-year quarter. BURL delivered a trailing four-quarter earnings surprise of 16.7%, on average.
The Kroger Co. KR currently has an Earnings ESP of +3.43% and a Zacks Rank of 3. The Zacks Consensus Estimate for Kroger’s upcoming quarter’s EPS is pegged at $1.16, implying a 10.5% year-over-year increase.
The Zacks Consensus Estimate for quarterly revenues is pegged at $34.6 billion, which indicates a increase of 2.1% from the figure reported in the prior-year quarter. KR has a trailing four-quarter earnings surprise of 2.7%, on average.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Kimberly-Clark Corporation (KMB): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
The Kroger Co. (KR): Free Stock Analysis Report
Burlington Stores, Inc. (BURL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).