

Advanced Micro Devices AMD is set to release its third-quarter 2026 results on Nov. 3.
AMD expects third-quarter 2026 revenues of $13 billion (+/-$300 million). At the midpoint of the revenue range, this represents year-over-year growth of 41% and 13% sequentially.
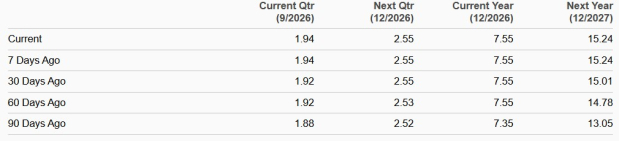
The Zacks Consensus Estimate for AMD’s third-quarter revenues is pegged at $13.12 billion, suggesting year-over-year growth of 42%. The consensus mark for third-quarter 2026 earnings is pegged at $1.94 per share, up a couple of cents over the past 30 days. The earnings estimate indicates growth of 61.7% on a year-over-year basis.
Consensus Estimate Trend
Image Source: Zacks Investment Research
AMD beat the Zacks Consensus Estimate for earnings in all the trailing four quarters, the average surprise being 6.74%.
Advanced Micro Devices, Inc. Price and EPS Surprise
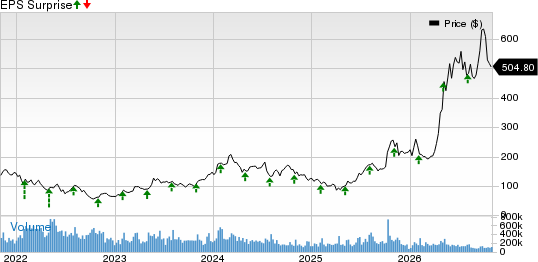
Advanced Micro Devices, Inc. price-eps-surprise | Advanced Micro Devices, Inc. Quote
Let’s see how things have shaped up for the upcoming earnings announcement.
Factors to Note Ahead of AMD’s Q3 Results
AMD’s third-quarter 2026 performance is likely to have benefited significantly from accelerating adoption of EPYC server processors across hyperscale cloud providers and enterprise customers. Growing AI inference and agentic AI workloads are driving demand for high-performance CPUs capable of managing data retrieval, workflow orchestration and AI processing tasks. The company’s fifth-generation EPYC Turin and fourth-generation EPYC Genoa processors have continued gaining traction across cloud and enterprise environments. The introduction of sixth-generation EPYC Venice processors, based on Zen 6 architecture and 2-nanometer technology, is expected to have strengthened AMD's competitive positioning.
The Data Center segment is likely to have benefited from increasing adoption of Instinct MI350-series GPUs across AI training and inference workloads. Demand for MI355X accelerators has strengthened as AI developers and cloud service providers expand deployments. The initial production shipments of AMD’s Helios rack-scale AI platform, powered by MI450-series GPUs, EPYC Venice processors and Pensando networking, are also expected to have contributed to third-quarter revenues. However, Helios contributions are expected to have been relatively modest in the to-be-reported quarter.
AMD’s Client business is likely to have benefited from continued Ryzen processor adoption, particularly across commercial notebooks, enterprise PCs and AI-enabled systems. Expanding adoption of Ryzen AI PRO 400-series processors across systems offered by Dell, HP, Lenovo and ASUS is expected to have supported market-share gains. Growing enterprise interest in local AI inference and AI-powered productivity applications may have provided additional opportunities for the Ryzen AI portfolio. Although management anticipated softer overall PC demand, AMD expected its Client business to outperform the broader market, supported by commercial customer adoption and product competitiveness.
Meanwhile, AMD’s Embedded segment is expected to have aided third-quarter performance as demand recovered across networking, communications, aerospace and defense, test and measurement and industrial applications. The growing adoption of embedded x86 processors in data center networking and control-plane functions is likely to have strengthened the segment’s growth trajectory. The third-quarter profitability is likely to have benefited from a growing contribution from higher-margin EPYC server processors and a recovery in the Embedded segment. Increasing Data Center revenues are expected to have supported gross profit expansion, while rising scale across AMD’s product portfolio may have improved operating leverage.
However, AMD continues to face stiff competition from NVIDIA NVDA, Broadcom AVGO and Intel INTC. AMD faces intense competition from NVIDIA in AI accelerators and Intel in server and client processors. The growing adoption of internally developed AI accelerators by hyperscalers, along with Arm-based server processors, adds competitive pressure. Broadcom is increasing competitive pressure on AMD by strengthening its position in custom AI accelerators and high-performance networking for hyperscale customers.
AMD Stock Outperforms Sector & Peers
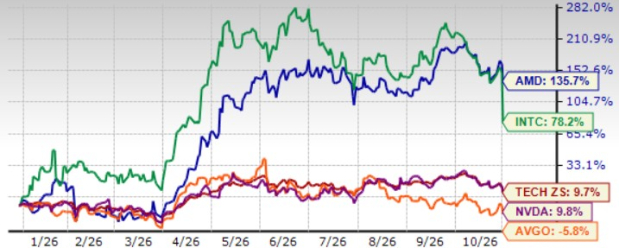
Advanced Micro Devices shares have surged 135.7% year to date (YTD), outperforming the Zacks Computer and Technology sector’s return of 9.7%. The company’s shares have outperformed Intel, NVIDIA and Broadcom YTD. Shares of Intel and NVIDIA have appreciated 78.2% and 9.8%, respectively, while Broadcom dropped 5.8%.
AMD’s Share Price Performance
Image Source: Zacks Investment Research
The AMD stock is not so cheap, as its Value Score of F suggests a stretched valuation at this moment.
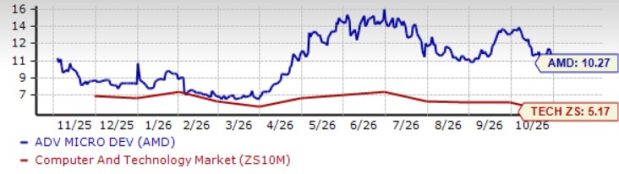
In terms of the forward 12-month price/sales, AMD is currently trading at 10.27X, higher than the sector’s 5.17X, NVIDIA’s 8.03X and Intel’s 4.85X, but lower than Broadcom’s 14.64X.
AMD Stock’s Valuation
Image Source: Zacks Investment Research
AMD Rides on Strong Portfolio Amid Stiff Competition
AMD is positioned to capitalize on accelerating investments in AI infrastructure as hyperscalers, cloud providers and enterprises expand AI training, inference and agentic computing capabilities. The company expects the Data Center AI accelerator market to reach approximately $1.4 trillion by 2030, growing at an annual rate exceeding 45%. Increasing demand for GPUs, server CPUs and networking solutions provides AMD with a substantial opportunity to expand its presence across AI infrastructure. The company expects Data Center segment revenues to more than double year over year in 2027, supported by the increasing scale of AI deployments and strong demand for EPYC processors.
AMD’s transition toward integrated rack-scale AI infrastructure represents a significant long-term growth catalyst. The Helios platform combines MI450-series GPUs, EPYC Venice CPUs, Pensando networking and ROCm software to deliver competitive AI inference performance and economics. The company expects substantial Helios shipment growth beginning in the fourth quarter of 2026 and accelerating throughout 2027. Strategic relationships with OpenAI, Meta and Anthropic provide multi-generation deployment opportunities, while Microsoft’s Azure adoption broadens AMD’s presence among major cloud providers. Beyond Helios, the planned MI500-series GPU platform, along with Verano CPUs and next-generation networking technologies, is expected to strengthen AMD's ability to compete for increasingly complex AI workloads.
Conclusion
AMD’s strong AI infrastructure portfolio, accelerating EPYC adoption and expanding hyperscaler partnerships position it well for long-term growth. However, stiff competition from NVIDIA, Broadcom and Intel, alongside a stretched valuation, remains a concern. Moreover, the stock’s impressive year-to-date rally suggests that much of the optimism surrounding its AI growth prospects may already be priced in. Investors should therefore adopt a cautious approach and wait for greater clarity on the Helios ramp and earnings growth before taking fresh positions in AMD stock.
AMD currently has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Broadcom Inc. (AVGO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).