

Remitly Global, Inc. RELY is slated to release third-quarter 2026 results on Nov. 4, after market close. The company’s quarterly results are likely to display an increase in both revenues and earnings per share.
In the last reported quarter, Remitly reported earnings of $1.07 per share, beating the Zacks Consensus Estimate of 29 cents per share. Second-quarter 2026 revenues were $495.2 million, up 20% year over year, driven by more active customers, stronger send volume and scaling growth accelerators.
Over the trailing four quarters, the company’s EPS surpassed the Zacks Consensus Estimate on each occasion. This is depicted in the graph below:
Remitly Global, Inc. Price and EPS Surprise
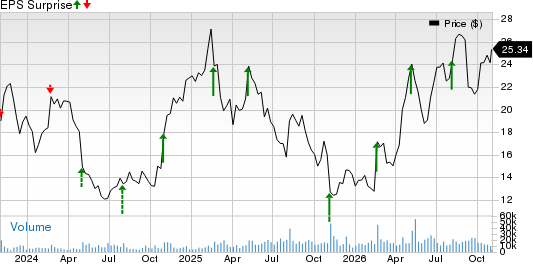
Remitly Global, Inc. price-eps-surprise | Remitly Global, Inc. Quote
Key Factors to Watch Ahead of RELY’s Q3 Results
Remitly Global appears positioned for another quarter of solid growth as customers shift from cash-based money transfers to digital channels. Wider geographic reach and demand for cross-border payments are likely to have supported activity. Management expects third-quarter 2026 revenues of $505-$507 million, suggesting 20-21% year-over-year growth.
Customer trends merit attention. After reaching 10.2 million quarterly active customers and $23.5 billion in send volume in the second quarter, Remitly is likely to have maintained momentum. Management expects send-volume growth to exceed revenue growth, with revenues rising slightly faster than active customers. Send volume per active customer is projected to increase by mid- to high-single digits.
High-value senders and businesses are expected to have added to transaction volumes. Bank-wire funding and easier onboarding could have encouraged larger transfers, extending the second-quarter growth. Remitly Business had more than 25,000 users at June-end. The September Etsy partnership expanded its business opportunity, although its fall rollout limits visibility into any third-quarter benefit.
Product expansion might have helped engagement, but its immediate financial impact remains uncertain. The Global Card began a phased rollout in July, while receiver services started generating revenues in the second quarter. Meanwhile, the expanded Skip the Line campaign and increased UAE marketing are likely to have supported customer acquisition, although at higher spending per active customer.
Remitly expects transaction margins to improve slightly year over year, supported by payment efficiencies. However, transaction losses remain a potential headwind. Management forecasts adjusted EBITDA of $92-$94 million, implying an 18-19% adjusted EBITDA margin, and anticipates year-over-year growth in net income. Overall, the outlook suggests growth with measured expense pressure.
Q3 Projections for Remitly
The Zacks Consensus Estimate for third-quarter revenues is currently pegged at $506.36 million, indicating a 20.71% year-over-year increase. The consensus mark for active customers is currently pegged at 10.5 million, up from 10.2 million in the prior quarter, while the same for send volume currently stands at $24.7 billion, suggesting an increase from $23.5 billion in the prior quarter.
The company’s activities in the to-be-reported quarter were adequate to garner analysts’ confidence. The consensus mark for EPS has been revised three cents upward to 33 cents over the past 90 days. This also implies a significant year-over-year increase from 4 cents reported in the year-ago period.
Here Is What Our Quantitative Model Predicts for RELY
Our proven model does not conclusively predict an earnings beat for Remitly this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
SEZL has an Earnings ESP of 0.00% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks to Consider
Here are some companies — Hut 8 Corp. HUT and StoneCo Ltd. STNE — worth considering, as our model shows that they have the right combination of elements to beat on earnings in their upcoming releases:
Hut 8 currently has an Earnings ESP of +24.67% and a Zacks Rank #3. Hut 8 is scheduled to report third-quarter 2026 results on Nov. 4. You can see the complete list of today’s Zacks #1 Rank stocks here.
StoneCo currently has an Earnings ESP of +2.74% and a Zacks Rank #3. STNE is slated to report third-quarter 2026 results on Nov. 12.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Remitly Global, Inc. (RELY): Free Stock Analysis Report
StoneCo Ltd. (STNE): Free Stock Analysis Report
Hut 8 Corp. (HUT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).