

Grab Holdings Limited GRAB used its third-quarter 2026 earnings call to emphasize improving profitability across its three core businesses, accelerating financial services expansion and continued investment in the Southeast Asian ecosystem.
Management raised its full-year outlook for the second time in 2026 while addressing analysts’ concerns about fourth-quarter spending, delivery margins, lending risks and capital allocation. The discussion highlighted how Grab intends to balance growth investments with operating leverage.
Grab posted break-even earnings compared with the Zacks Consensus Estimate of 2 cents in the quarter. Revenues of $1.11 billion beat the consensus mark of $1.07 billion.
Grab Holdings Limited Price, Consensus and EPS Surprise
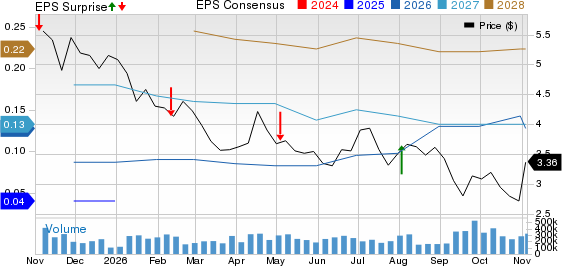
Grab Holdings Limited price-consensus-eps-surprise-chart | Grab Holdings Limited Quote
GRAB Raises Outlook but Maintains Spending Discipline
Grab raised its 2026 revenue guidance to $4.15-$4.20 billion from $4.10-$4.15 billion. Adjusted EBITDA guidance increased to $790-$800 million from $720-$740 million.
Chief financial officer Peter Oey explained that fourth-quarter profitability expectations reflect deliberate reinvestment during Southeast Asia’s festive and tourism season. Elevated fuel costs also require continued driver support.
Responding to analysts from JPMorgan, HSBC, Barclays and Mizuho, Oey emphasized investments in driver availability, consumer affordability and new products. Management expects regional corporate costs to remain relatively stable between the first and second halves.
Grab Targets Further Deliveries Margin Expansion
President and chief operating officer Alexander Hungate attributed Deliveries margin expansion to operating leverage, advertising monetization and AI-enabled marketplace efficiencies.
Deliveries segment adjusted EBITDA reached $123 million, with its margin expanding to 2.7% of gross merchandise value from 2.1% a year earlier. Hungate reiterated the longer-term margin target exceeding 4%, despite planned product investments.
Responding to analysts from Morgan Stanley, Citi and other firms, Hungate highlighted GrabMall’s potential to combine branded retail commerce, advertising and fulfillment. Management expects GrabMart and GrabMall expansion to support additional monetization opportunities, including lending following the proposed Atome acquisition.
GRAB Sees Financial Services as a Growth Engine
Financial Services achieved its first positive quarterly segment adjusted EBITDA of $12 million, supported by lending expansion and contributions from Superbank and Stash.
Hungate told analysts that Grab’s established customer relationships, transaction information and digital banking deposits provide advantages in acquiring borrowers, underwriting loans and funding lending operations.
Management reiterated its 2028 Financial Services adjusted EBITDA target of $500 million and gross loan portfolio target exceeding $6 billion, including Atome, subject to completion. Oey expects $300 million of the EBITDA target to come from Atome and Superbank. Credit quality remains important, with nonperforming loans representing 2.6% of the portfolio.
Grab Expands AI Applications Across Its Ecosystem
Chief executive officer Anthony Tan emphasized measurable transaction activity rather than time spent within Grab’s application as the primary indicator of AI effectiveness.
Tan reported that nearly 500,000 drivers have access to Grab’s AI assistant, with active users earning more than 10% additional income per online hour. Merchants using its AI assistant generate approximately 20% higher earnings on average.
Addressing questions from Daiwa and Mizuho, Tan discussed Grab’s OpenAI partnership to train 30,000 driver and merchant partners. He also described an early-stage Meta Muse integration enabling purchases through GrabMart. Management considers agent-driven transactions an emerging acquisition channel but said the pilot remains too early to quantify.
GRAB Balances Buybacks With Strategic Investments
Oey highlighted the acceleration of Grab’s share repurchase program, with $400 million bought back during September and October and another $500 million targeted for completion by September 2027.
Following Taiwan’s rejection of the proposed foodpanda acquisition, management reiterated its preference for investments supporting Mobility, Deliveries and Financial Services.
Hungate also outlined Grab’s autonomous vehicle strategy, emphasizing an asset-light operating model supported by fleet owners and technology partners. Management expects autonomous vehicles and human drivers to operate alongside each other during a prolonged regional transition.
Grab Maintains Focus on Profitable Expansion
Management’s overarching message centered on scaling existing operations while directing investment toward financial services, AI-enabled efficiencies and customer engagement.
Despite fuel-related pressures and regulatory uncertainty in Indonesia, executives maintained their 2028 expectations for revenue compounded annual growth exceeding 30% and adjusted EBITDA of $1.7 billion, including the proposed Atome acquisition.
What GRAB’s Zacks Rank and Style Scores Indicate
GRAB currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term earnings estimate revision outlook. The stock’s Value Score of C reflects middle-range valuation characteristics, while its Growth Score, Momentum Score and VGM Score of F indicate relatively weak combined Value, Growth and Momentum characteristics under the Zacks methodology. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
These signals warrant consideration alongside the neutral Zacks Rank, which may change as analysts revise earnings estimates following the latest quarterly results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Grab Holdings Limited (GRAB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).