

Kimberly-Clark Corporation KMB posted third-quarter 2026 results, with adjusted earnings beating the Zacks Consensus Estimate but revenues falling short.
Taking a Closer Look at KMB’s Q3 Results
Adjusted earnings attributable to Kimberly-Clark were $1.70 per share, down 6.6% year over year but surpassing the consensus estimate of $1.66. Adjusted earnings from continuing operations increased 17.2% year over year to $1.70 per share, primarily driven by lower net interest expenses and a reduced adjusted effective tax rate.
Kimberly-Clark Corporation Price, Consensus and EPS Surprise
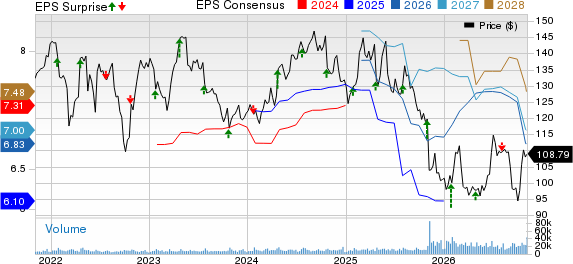
Kimberly-Clark Corporation price-consensus-eps-surprise-chart | Kimberly-Clark Corporation Quote
Net sales declined 0.4% year over year to $4,134 million, missing the Zacks Consensus Estimate of $4,147 million. The decline in organic sales, reflecting pricing pressures and disruptions in China, was partly offset by favorable currency impacts and sales recognized under supply agreements with the Arbex Joint Venture.
Organic sales declined 1.3%, including an approximately 270-basis-point headwind from the China social media disruption. Retail inventory movements in North America also pressured performance.
The adjusted gross margin contracted 130 basis points year over year to 35.5%, reflecting unfavorable pricing net of cost inflation and supply-chain investments. Strong productivity savings partly cushioned these pressures.
Adjusted operating profit declined 0.9% to $677 million from $683 million. Unfavorable pricing and the China disruption, which created an approximately 530-basis-point headwind, weighed on profitability. Lower marketing, research and general expenses provided some relief.
KMB Provides Q3 Insights by Segment
North America (“NA”) segment's net sales increased 0.9% year over year to $2,738 million, supported by supply-agreement transactions with the Arbex Joint Venture and organic sales growth of 0.4%.
Organic sales benefited from 2% volume growth despite an approximately 130-basis-point drag from retailer inventory movements. Lower pricing, resulting from increased promotional activities, partly offset the volume gains.
NA's operating profit increased 2.7% to $657 million. Strong productivity savings and reduced advertising spending outweighed some of the pressures from unfavorable pricing, cost inflation and supply-chain investments.
The International Personal Care (“IPC”) segment's net sales declined 2.8% year over year to $1,396 million. Organic sales dropped 4.6%, as growth in South Korea, Indonesia and Enterprise Markets was more than offset by weakness in China.
The China social media disruption created an approximately 770-basis-point headwind to IPC's organic sales.
IPC's operating profit plunged 32.7% to $144 million, primarily due to higher input costs and an approximately 16.8% headwind from the China disruption. Strong productivity savings partly mitigated these challenges.
Kimberly-Clark’s Financial Health Snapshot
Kimberly-Clark ended the third quarter with cash and cash equivalents of $1,874 million, up from $688 million at the end of December 2025. Long-term debt stood at $5,870 million, while total stockholders' equity reached $3,074 million.
For the first nine months of 2026, cash provided by operations totaled $2,408 million compared with $1,805 million in the prior-year period. Capital spending increased to $1,039 million from $741 million.
Kimberly-Clark Advances Its Portfolio Transformation
Kimberly-Clark completed the acquisition of Kenvue on Nov. 2, 2026, marking a significant milestone in its transformation into a global health and wellness leader. Management emphasized opportunities to leverage the combined company's innovation, brand-building and productivity capabilities.
Management aims to capitalize on these opportunities by applying its proven growth strategies and productivity initiatives to the combined company. The focus remains on driving sustainable growth, improving operational efficiency and building on the progress achieved through its Powering Care transformation strategy.
KMB Reaffirms Its 2026 Standalone Outlook
Kimberly-Clark continues to expect 2026 organic sales growth to trail the weighted average growth of its operating categories and markets by approximately 100 basis points. These categories and markets have recorded roughly 1.7% growth on a trailing 12-month basis.
The outlook reflects realized and potential companywide headwinds of approximately 100 basis points from the China social media disruption.
Adjusted operating profit is projected to grow at a mid-single-digit rate on a constant-currency basis. Adjusted earnings from continuing operations are expected to increase at a high-single-digit rate, while adjusted earnings attributable to Kimberly-Clark are projected to decline at a low-single-digit rate on the same basis.
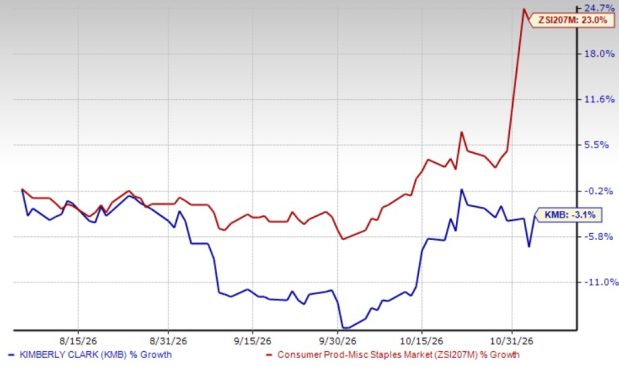
This Zacks Rank #5 (Strong Sell) company has fallen 3.1% in the past three months against the industry’s 23% growth.
Image Source: Zacks Investment Research
Stocks to Consider
Ulta Beauty, Inc. ULTA operates as a specialty beauty retailer in the United States, Mexico, and Kuwait and currently holds a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Ulta Beauty’s current fiscal-year sales and earnings calls for growth of 10.7% and 12.9%, respectively, from the year-ago reported numbers. ULTA delivered a trailing four-quarter earnings surprise of 7.6%, on average.
Dollar General Corporation DG is one of the largest discount retailers in the United States, selling low-priced merchandise, typically $10 or less. The company currently has a Zacks Rank of 2. DG delivered a trailing four-quarter earnings surprise of 19.1%, on average.
The Zacks Consensus Estimate for Dollar General’s current fiscal-year sales and EPS is expected to rise 5.8% and 15.9%, respectively, from the year-ago reported figures.
Target Corporation TGT operates as a general merchandise retailer in the United States. The company currently carries a Zacks Rank of 2. TGT delivered a trailing four-quarter earnings surprise of 10.5%, on average.
The Zacks Consensus Estimate for Target Corporation’s current fiscal-year sales and EPS indicates growth of 4.6% and 39%, respectively, from the year-ago reported numbers.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Kimberly-Clark Corporation (KMB): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
Ulta Beauty Inc. (ULTA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).