

Dillard's Inc. DDS delivered third-quarter fiscal 2026 results, wherein both earnings and revenues surpassed the Zacks Consensus Estimate. The company reported earnings of $8.38 per share, beating the consensus mark of $7.80 by 7.4%. Earnings increased 0.8% year over year from $8.31 per share.
Net sales rose 0.8% year over year to $1.48 billion, surpassing the consensus estimate of $1.47 billion by 1%. The performance was supported by higher retail sales and stable merchandise margins. Comparable store sales increased 1%, reflecting continued growth across several merchandise categories.
Dillard's, Inc. Price, Consensus and EPS Surprise
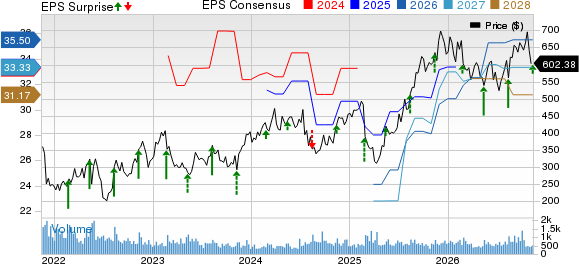
Dillard's, Inc. price-consensus-eps-surprise-chart | Dillard's, Inc. Quote
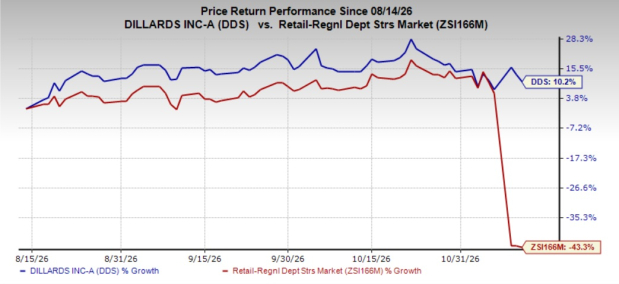
Shares of the Zacks Rank #3 (Hold) company have risen 10.2% in the past three months, outperforming the industry's 43.3% decline.
Image Source: Zacks Investment Research
DDS Records Higher Retail Sales in Q3
DDS generated total retail sales of $1.418 billion in the fiscal third quarter compared with $1.401 billion in the prior-year period. Total retail sales, which exclude the company's construction business, CDI Contractors, increased 1% year over year.
Sales trends varied across merchandise categories. Home and furniture, men's apparel and accessories, ladies' accessories and lingerie, and juniors' and children's apparel recorded moderate increases. Cosmetics registered slight growth, while shoes remained essentially flat. Ladies' apparel experienced a slight decline.
Dillard's Maintains Strong Retail Gross Margin
Dillard's reported a retail gross margin of 45.3% of sales in the fiscal third quarter, unchanged from the year-ago period. The steady margin performance reflected a mixed trend across merchandise categories, with improvements in certain businesses offsetting declines elsewhere.
Retail gross margin increased moderately in men's apparel and accessories and home and furniture. Shoes registered a slight improvement, while ladies' apparel, cosmetics, and ladies' accessories and lingerie witnessed slight declines. Juniors' and children's apparel recorded a moderate margin contraction.
The company's consolidated gross margin expanded 20 basis points (bps) year over year to 43.6% from 43.4%. The improvement contributed to profitability despite higher operating expenses.
DDS Faces Higher Operating Expenses
Dillard's reported selling, general and administrative expenses, or operating expenses, of $448.9 million in the fiscal third quarter compared with $440.4 million in the year-ago quarter. The increase was primarily attributable to higher payroll expenses.
As a percentage of sales, operating expenses increased 30 bps year over year to 30.3% from 30%. The rise in expenses outpaced the modest increase in retail sales, reflecting continued pressure from payroll costs.
Despite the higher expense burden, DDS reported net income of $130.9 million compared with $129.8 million in the prior-year quarter. The company's stable retail gross margin and improved consolidated gross margin helped support earnings growth.
Dillard's Reports Strong YTD Results
For the first 39 weeks of fiscal 2026, Dillard's reported net sales of $4.556 billion compared with $4.511 billion in the corresponding prior-year period. Total retail sales increased 2% to $4.391 billion from $4.315 billion, while comparable store sales also advanced 2%.
The company reported net income of $479.1 million, or $30.68 per share, compared with $366.5 million, or $23.39 per share, a year earlier. Results included $37.2 million in refunds related to International Emergency Economic Powers Act tariffs and a $104.1 million pretax gain from a litigation settlement involving payment card interchange fees.
Retail gross margin improved to 44% from 42.9%, benefiting from an 80-bps contribution from tariff refunds. Operating expenses increased to $1.337 billion from $1.296 billion, primarily due to higher payroll expenses.
DDS Strengthens Liquidity Amid Higher Inventories
DDS ended the fiscal third quarter with cash and cash equivalents of $896.8 million and short-term investments of $488.7 million. Merchandise inventories increased to $1.781 billion from $1.718 billion in the prior-year period, representing approximately 4% growth.
Long-term debt stood at $145.8 million compared with $225.7 million a year ago. Stockholders' equity increased to $2.248 billion from $2.045 billion. For the first 39 weeks, operating activities generated $479.8 million in cash compared with $505.8 million in the year-ago period.
The company operated 272 Dillard's stores, including 28 clearance centers, across 30 states, alongside its online store. It announced plans to close its Boynton Beach Mall Clearance Center in Florida in January 2027.
Dillard's Provides Updated FY26 Financial Estimates
Dillard's provided financial estimates for fiscal 2026, ending Jan. 30, 2027. The company expects depreciation and amortization of $175 million compared with $179 million in fiscal 2025.
Rentals are projected at $17 million versus $19 million in fiscal 2025. The company anticipates net interest and debt income of $12 million compared with $6 million in the prior year. Capital expenditures are estimated at $100 million, up from $93 million in fiscal 2025.
Stocks to Consider
Dollar General Corporation DG, a discount retailer, currently carries a Zacks Rank of 2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for Dollar General’s current fiscal-year sales and EPS implies growth of 4.3% and 15.9%, respectively, from the year-ago figures. DG delivered a trailing four-quarter earnings surprise of 19.1%, on average.
Target Corporation TGT, which operates as a general merchandise retailer, currently carries a Zacks Rank #2. TGT delivered a trailing four-quarter earnings surprise of 10.5%, on average.
The Zacks Consensus Estimate for Target’s current fiscal-year sales and EPS implies growth of 5.1% and 39%, respectively, from the year-ago figures.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Dillard's, Inc. (DDS): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Dollar General Corporation (DG): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).