

Bruker Corporation BRKR appears well-positioned for growth in the coming quarters, supported by revenue growth in its Biosystems and Diagnostics businesses, strength in molecular diagnostics and favorable demand in Europe. The company is broadening its preclinical imaging portfolio through advanced MRI systems and its majority investment in MIMETAS. Bruker is also on track to achieve its 2026 cost-savings target of $140 million, supporting its margin expansion goal. However, uneven academic demand and macroeconomic uncertainty remain concerns for the company’s operations.
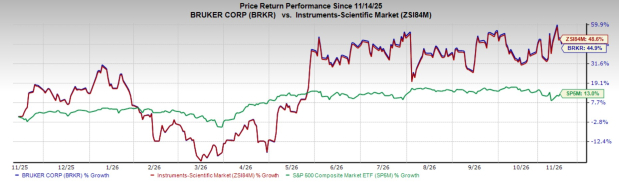
In the past year, this Zacks Rank #3 (Hold) stock has risen 44.9% compared with 48.6% growth of the industry and the S&P 500 Composite’s 13% return.
The renowned medical device company has a market capitalization of $9.53 billion. Bruker’s estimated earnings yield is 3.4% against the industry’s negative 10.9% yield. In the trailing four quarters, it surpassed earnings estimates thrice and missed on one occasion, with the average surprise being 21.96%.
Let’s delve deeper.
Upsides for BRKR Stock
Mass Spectrometry and Diagnostics Broaden Growth: Bruker’s mass spectrometry and diagnostics businesses benefit from demand across biopharma, molecular diagnostics and advanced analytical research. During the first nine months of 2026, BSI Biosystems revenues increased by a low-single-digit percentage at constant exchange rates to $1.15 billion. Mass spectrometry benefited from the TOFWERK acquisition, while IR and Raman spectroscopy also recorded revenue growth.
BMID revenues increased 6% year over year to $395.8 million, driven by robust molecular diagnostics growth and modest gains in microbiology. European demand remained favorable, offsetting softer conditions in the United States and Asia-Pacific. The reorganized operating groups allow Bruker to focus more closely on these markets, supporting longer-term growth opportunities in diagnostics and advanced analytical research.
Image Source: Zacks Investment Research
Preclinical Imaging Remains an Expansion Avenue: Bruker’s preclinical imaging portfolio serves cancer research, neuroimaging, orthopedics, cardiac imaging and stroke models, with higher-field systems supporting applications requiring greater resolution. The first quarter of 2026 included acceptance of an 18 Tesla preclinical MRI system, while first-half NMR preclinical and preclinical imaging orders both increased at double-digit rates.
In the third quarter, Bruker expanded its preclinical capabilities through a majority investment in MIMETAS, which develops humanized organ-on-a-chip models for drug discovery. MIMETAS generates approximately $10 million in annual revenues, with management expecting double-digit growth. Its technology complements Bruker’s multiomics, spatial biology and imaging workflows, broadening opportunities in translational research.
Cost Actions Support Margin Recovery: Bruker’s cost-reduction program continues to improve underlying profitability despite modest organic revenue growth. Third-quarter 2026 adjusted operating margin increased 400 basis points (bps) to 16.3%, supported by approximately 300 bps from cost savings and 90 bps from favorable mix.
For the first nine months of 2026, adjusted operating margin improved 220 bps to 13.6%, while adjusted earnings per share (EPS) increased 10.6% to $1.36. Bruker remains on track to achieve $140 million in annualized cost savings in 2026, which is expected to drive a 250-300 bps expansion in full-year adjusted operating margin. These efficiency gains also support the unchanged 2026 adjusted EPS guidance of $2.10-$2.15, representing 15%-17% year-over-year growth.
What Ails Bruker?
U.S. Academic Demand Remains Uneven: Academic and government research remains an important market for Bruker, with funding uncertainty continuing to affect demand for scientific instruments. U.S. academic and government bookings returned to double-digit organic growth in the third quarter of 2026, marking the first year-over-year increase since the 2025 NIH funding disruption.
However, the recovery benefited from a weak comparison period and has yet to translate into broader revenue growth. During the first nine months of 2026, softness in academic and government spending continued to weigh on Biosystems and NANO revenues. Regional demand also remained uneven, with European and Japanese academic bookings declining in the third quarter.
Macroeconomic Variability: Trade policy uncertainty continues to affect Bruker’s revenue and profitability, while uneven customer spending adds to demand volatility. In the second quarter of 2026, U.S. tariff refunds reduced organic revenue growth from 3.4% to 2.8%, although net tariff effects added approximately 200 bps to operating margin. Organic revenue declined 0.3% in the first nine months of 2026, reflecting uneven demand across academic, government and industrial markets.
BRKR Stock’s Estimate Trend
The Zacks Consensus Estimate for Bruker’s 2026 EPS has increased 1 cent to $2.13 in the past 30 days.
The consensus mark for 2026 revenues is pegged at $3.54 billion, suggesting a 3.1% rise from the year-ago reported number.
Key Picks
Some better-ranked stocks in the broader medical space are Phibro Animal Health PAHC, IDEXX Laboratories IDXX and Globus Medical GMED.
Phibro Animal Health has an earnings yield of 10.6% compared with the industry’s 2.8% yield. Shares of the company have plunged 20.7% compared with the industry’s 21% decline over the past year. PAHC’s earnings outpaced estimates in three of the trailing four quarters and matched on one occasion, the average surprise being 12.43%.
PAHC carries a Zacks Rank #2 (Buy) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
IDEXX Laboratories, carrying a Zacks Rank #2, has an earnings yield of 2.2% against the industry’s negative 2.3% yield. Its earnings beat estimates in each of the trailing four quarters, the average surprise being 5.5%. IDXX shares have plunged 0.5% against the industry’s 4.8% growth over the past year.
Globus Medical, carrying a Zacks Rank #2, has an earnings yield of 7% against the industry’s negative 2.3% yield. Its earnings surpassed estimates in each of the trailing four quarters, with the average surprise being 16.2%. GMED shares have dipped 13.9% against the industry’s 4.8% gain over the past year.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Bruker Corporation (BRKR): Free Stock Analysis Report
IDEXX Laboratories, Inc. (IDXX): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).