

Astera Labs (ALAB) is heading into what is likely to be its biggest quarter yet. Management expects third-quarter revenue of $540 million to $560 million and non-GAAP EPS of $1.16 to $1.21, up from $0.80 in Q2. Revenue of $392.4 million in Q2 was also a company record, so expecting revenue to jump about 40% next quarter shows how fast Astera is growing.
Even so, Northland Capital Markets cut ALAB stock to “Market Perform” from “Outperform” on Oct. 9, citing valuation concerns. Analyst Gus Richard noted that shares had climbed past Northland's earlier target. Yet Richard still sees estimates moving higher as Scorpio X ramps, calling EPS of $5 in 2028 achievable. The analyst also pointed to Astera’s heavy reliance on a small number of customers, a risk the company has long faced.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Northland has a fair point in the short run. The Q3 jump is being driven mainly by Scorpio X, a high-capacity artificial intelligence (AI) switch that’s now moving into volume production at one lead customer. Other buyers are still testing the chip, with production expected around the end of this year or early next year. If those ramps slip, Astera Labs' growth would lean even harder on a single buyer.
Why the Customer Picture May Be Improving
Looking beyond the next quarter, Astera Labs' customer base appears to be widening. More than 10 customers are engaged on Scorpio X. Astera also expects to ship its Leo memory controllers in volume to two U.S. hyperscalers in 2027.
As the industry moves to UALink, a newer standard for connecting AI chips, management expects the company to earn more revenue from each AI chip. Profitability is improving, too. Non-GAAP operating margin is guided to about 43% in Q3, up from 39.1% in Q2. Gross margin is expected to drift toward a long-term target of 70% as lower-margin hardware grows, but rising revenue is still pushing profits higher.
In my opinion, Northland’s call is more about ALAB stock’s price than the business itself.
About Astera Labs Stock
Astera Labs designs and sells semiconductor-based connectivity products that help connect chips, servers, and memory in cloud computing and AI data centers. Its products help data move faster and more reliably between components, while its COSMOS software chips help companies monitor and manage these connections across large data centers. Instead of competing with headline AI chipmakers like Nvidia (NVDA) and Advanced Micro Devices (AMD), Astera provides the essential internal plumbing that lets those massive processors communicate. Founded in 2017, the company is headquartered in San Jose, California.
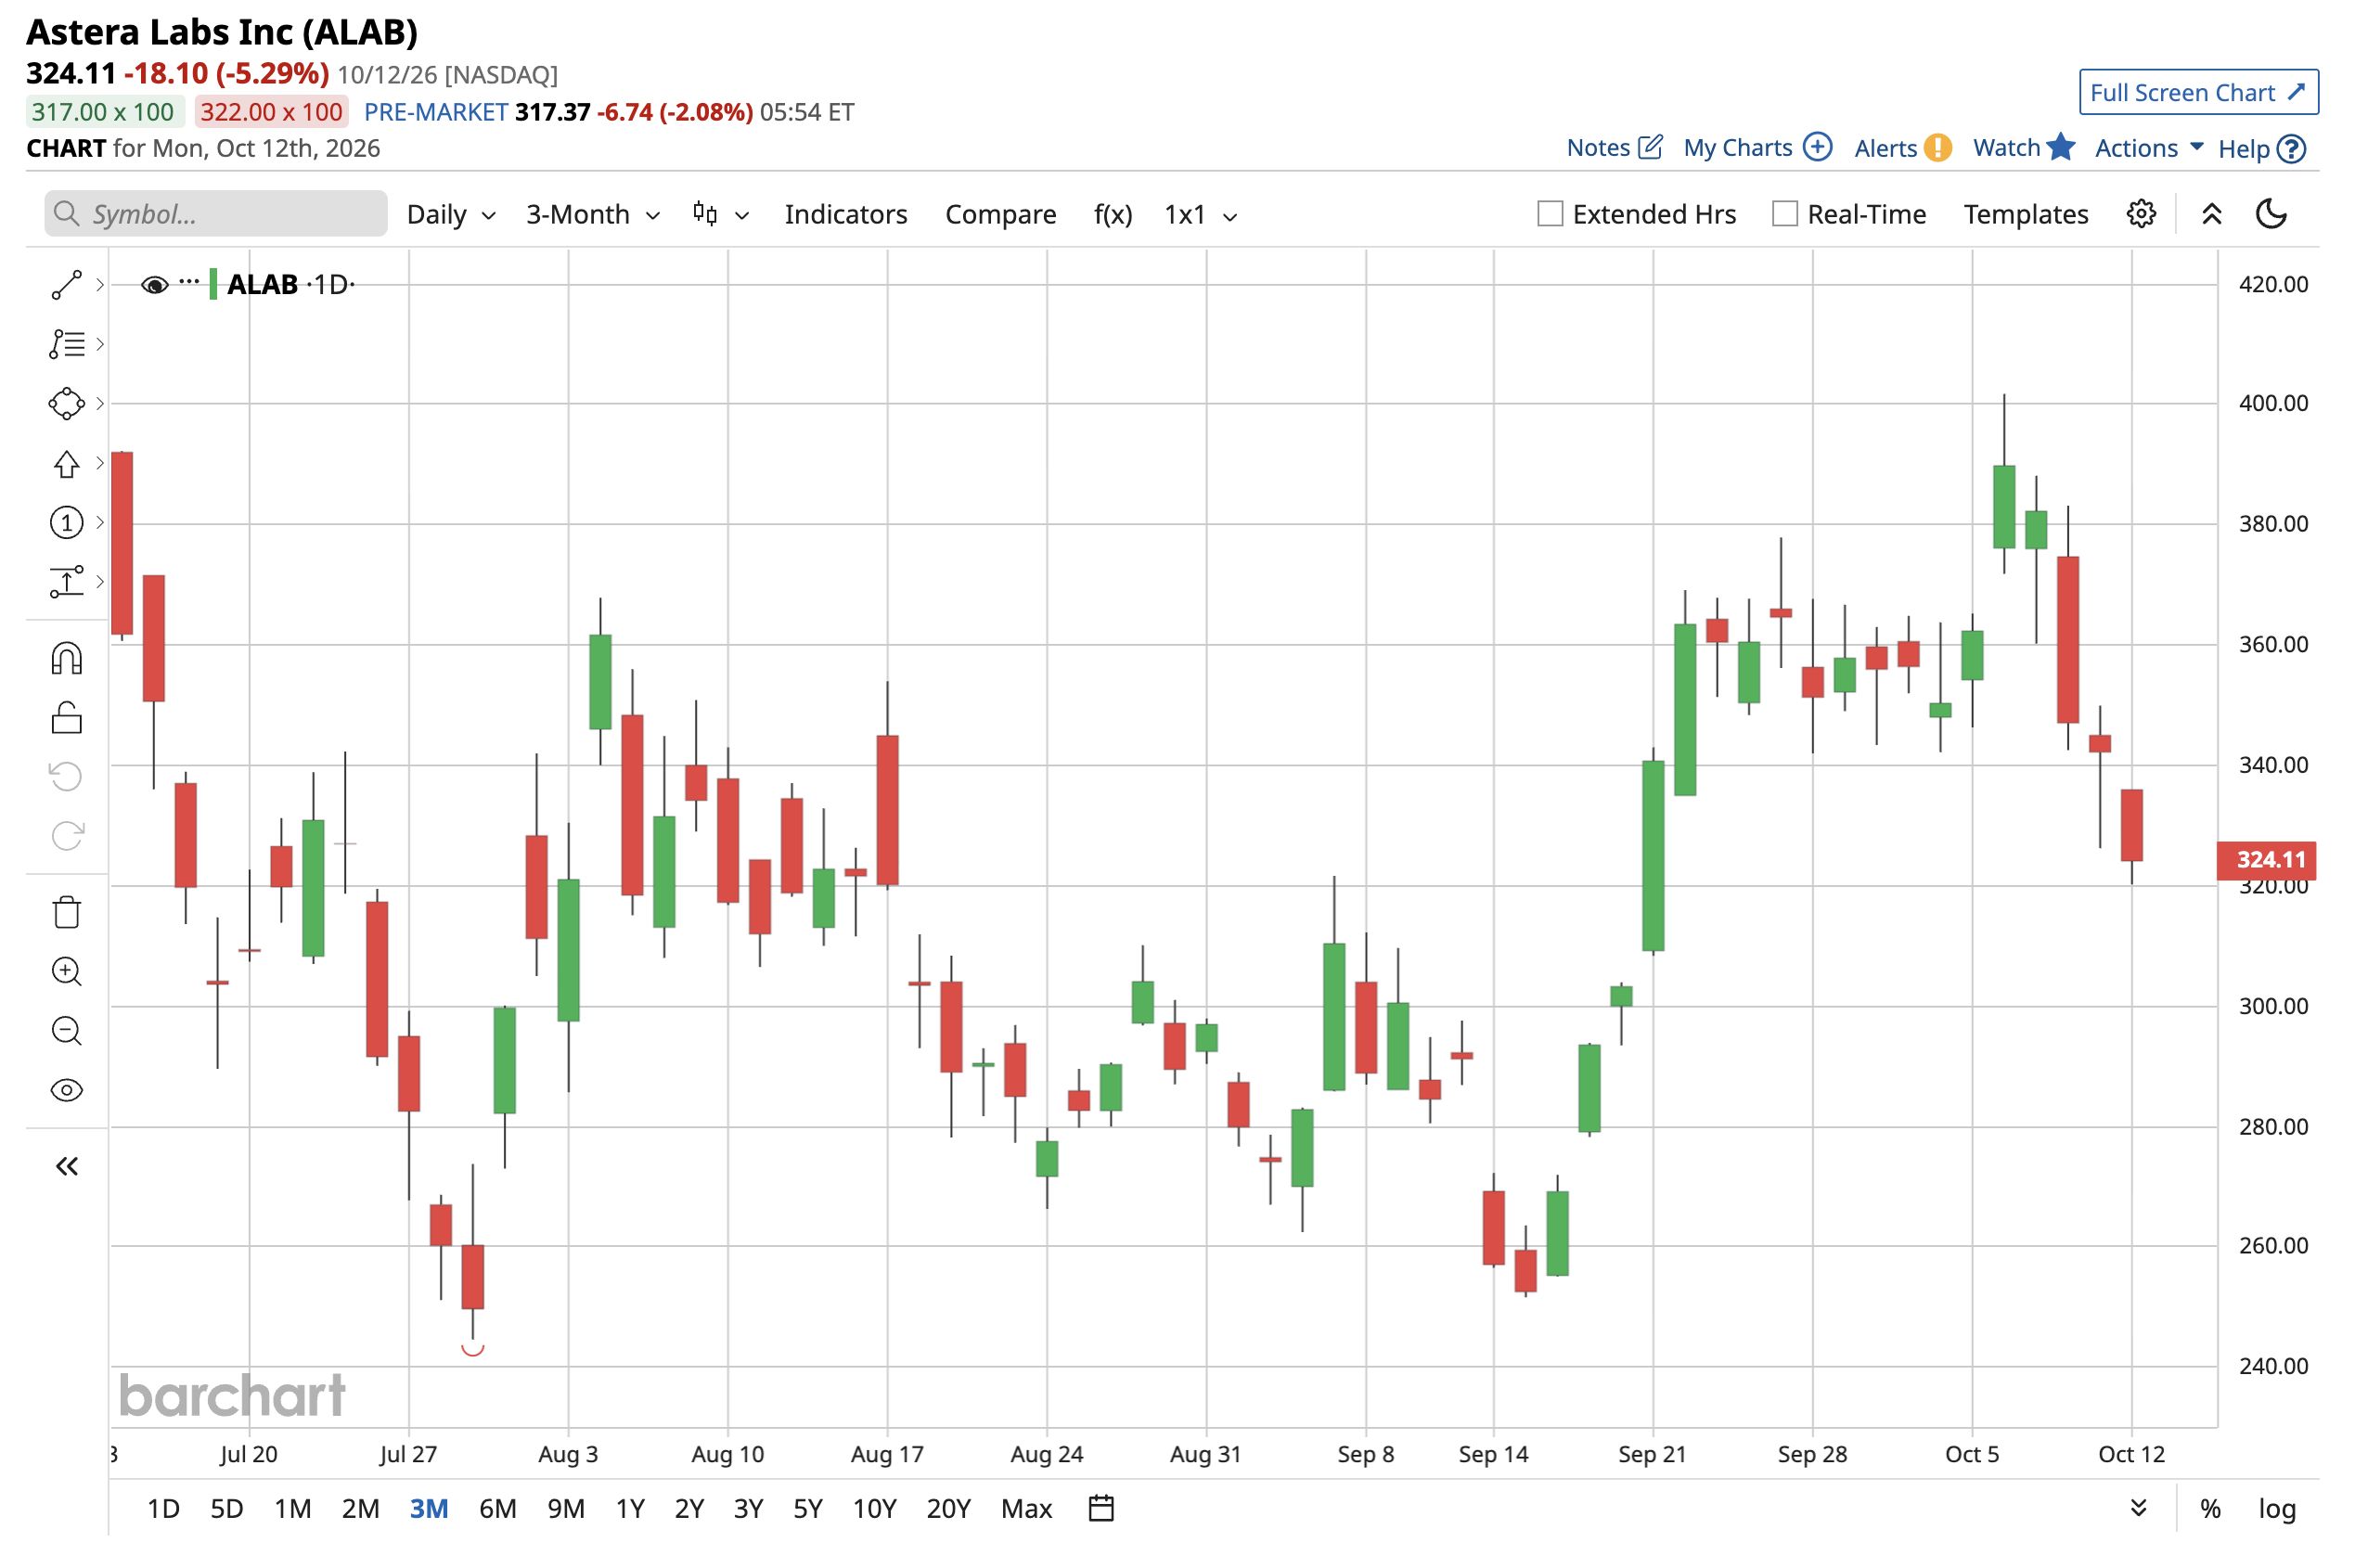
Over the past year, ALAB stock has gained 75%, which is slightly better than the 71% rise of the iShares Semiconductor ETF (SOXX) over the same period. The shares surged more than 400% from a 52-week low of $97.89 in late March to a high of $499.48 in late June. However, the rally has since faded. ALAB stock closed at $285.82 per share on Oct. 16, about 43% below its late June peak.
 www.barchart.com
The valuation is high on most measures. ALAB stock has a forward price-to-earnings (P/E) ratio of 111 times, while the price-to-sales (P/S) ratio is 61.1 times. Strong growth could bring the multiples down, though. Analysts expect EPS to jump 137% in fiscal 2026 and 70% in fiscal 2027, which would put the stock at roughly 62 times 2027 earnings.
Astera holds about $1.25 billion in cash against just $44.4 million in debt, making it essentially debt-free. For me, it all comes down to how fast Astera can bring new Scorpio X customers on board.
What Do Analysts Expect for ALAB Stock?
Wall Street remains divided on ALAB stock. Recently, Northland downgraded shares to “Market Perform” from “Outperform” with no price target. Analyst Gus Richard expects earnings estimates to rise over the next few quarters as the company expands Scorpio X. In contrast to Northland, Fubon Securities recently initiated coverage of ALAB stock with a “Buy” rating and a price target of $500.
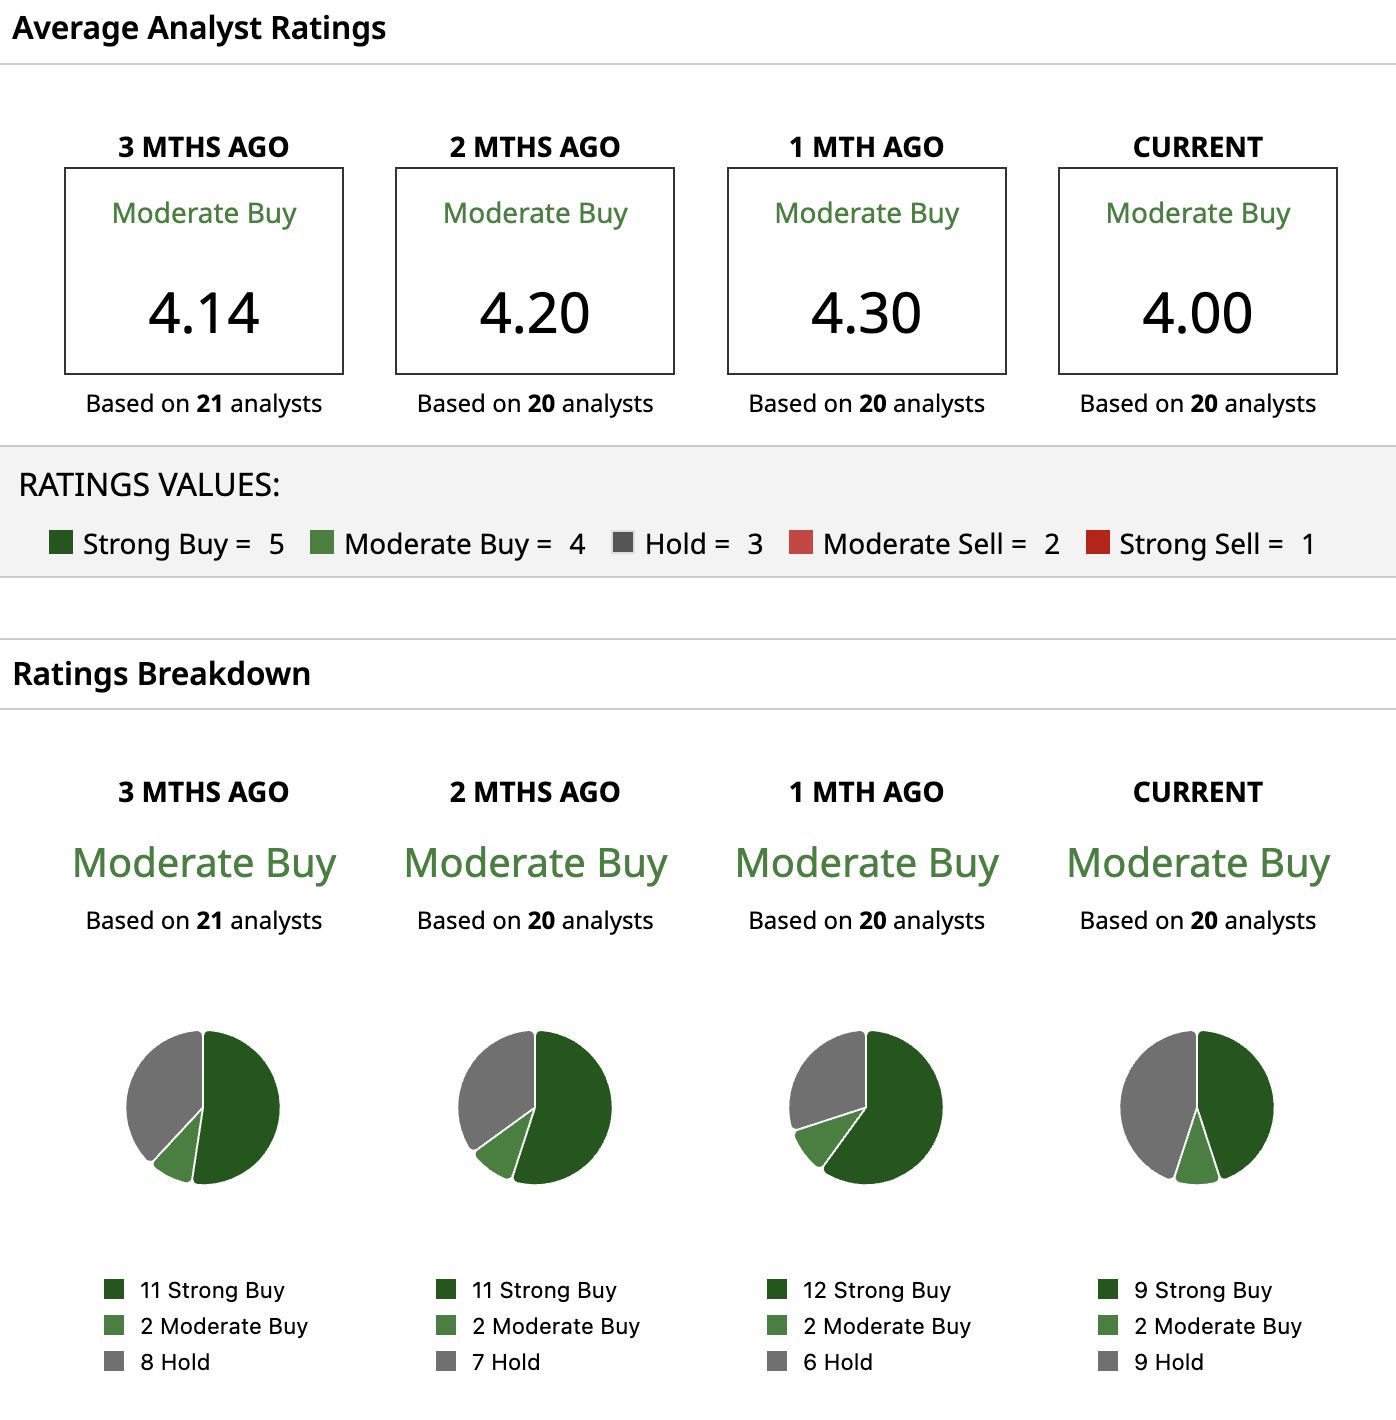
Based on 20 Wall Street analysts with coverage, Astera Labs holds a consensus “Moderate Buy” rating. Out of those analysts, nine have a “Strong Buy” rating, two have a “Moderate Buy” rating, and nine have a “Hold” rating. The mean price target of $423.53 reflects potential upside of 48% from current levels. Meanwhile, the high price target of $500 implies shares could rise as much as 75% from here.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Northland Downgraded Astera Labs Even Though It Expects Earnings to Rise Goldman vs. JPMorgan: Both Raised Their Dividends. Which Bank Is the Better Buy? Lockheed Martin's $88 Billion Missile Backlog Could Be a Reason to Buy Before October 22 Applied Materials Just Opened a $5 Billion R&D Center. What That Actually Means for AMAT Stock.