

Investors don’t have to bet on Nvidia (NVDA) alone to benefit from AI chip spending. Marvell Technology (MRVL) ranks among the top global chipmakers, thanks to its role in custom AI chips and data center connectivity. As companies develop more of their own processors due to the AI boom, Marvell could benefit from designing those chips and connecting the systems around them. This opportunity has led management to raise its fiscal 2028 revenue target to $20 billion. But can earnings grow fast enough to justify the stock’s valuation?
Custom AI Chips Are Just One Part of Marvell’s Growth Story
In my view, Marvell’s biggest advantage is that its revenue streams are not just dependent on processors. The company raised its fiscal 2031 revenue target to $70 billion to $90 billion at its Oct. 6 investor day. It also expects custom chip revenue to exceed $12 billion in fiscal 2029. But I believe the broader opportunity is just as important. Marvell also sees opportunities in XPU-attached products, which add networking, memory, and other functions to AI processors. These products could give Marvell another source of growth beyond designing complete custom chips. CEO Matt Murphy's comments on the company's broader connectivity portfolio further support this thesis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Marvell Stock
Marvell Technology is a semiconductor company that provides data infrastructure solutions used in data centers, networking systems, and communication equipment worldwide. The company designs advanced chips that move, process, and store data efficiently. It offers a portfolio of Ethernet solutions, networking controllers, processors, storage controllers, optical and interconnect solutions, and custom chips. Marvell focuses on technologies that improve high-speed data transfer, connectivity, and AI infrastructure performance. Founded in 1995, the company is headquartered in Wilmington, Delaware.
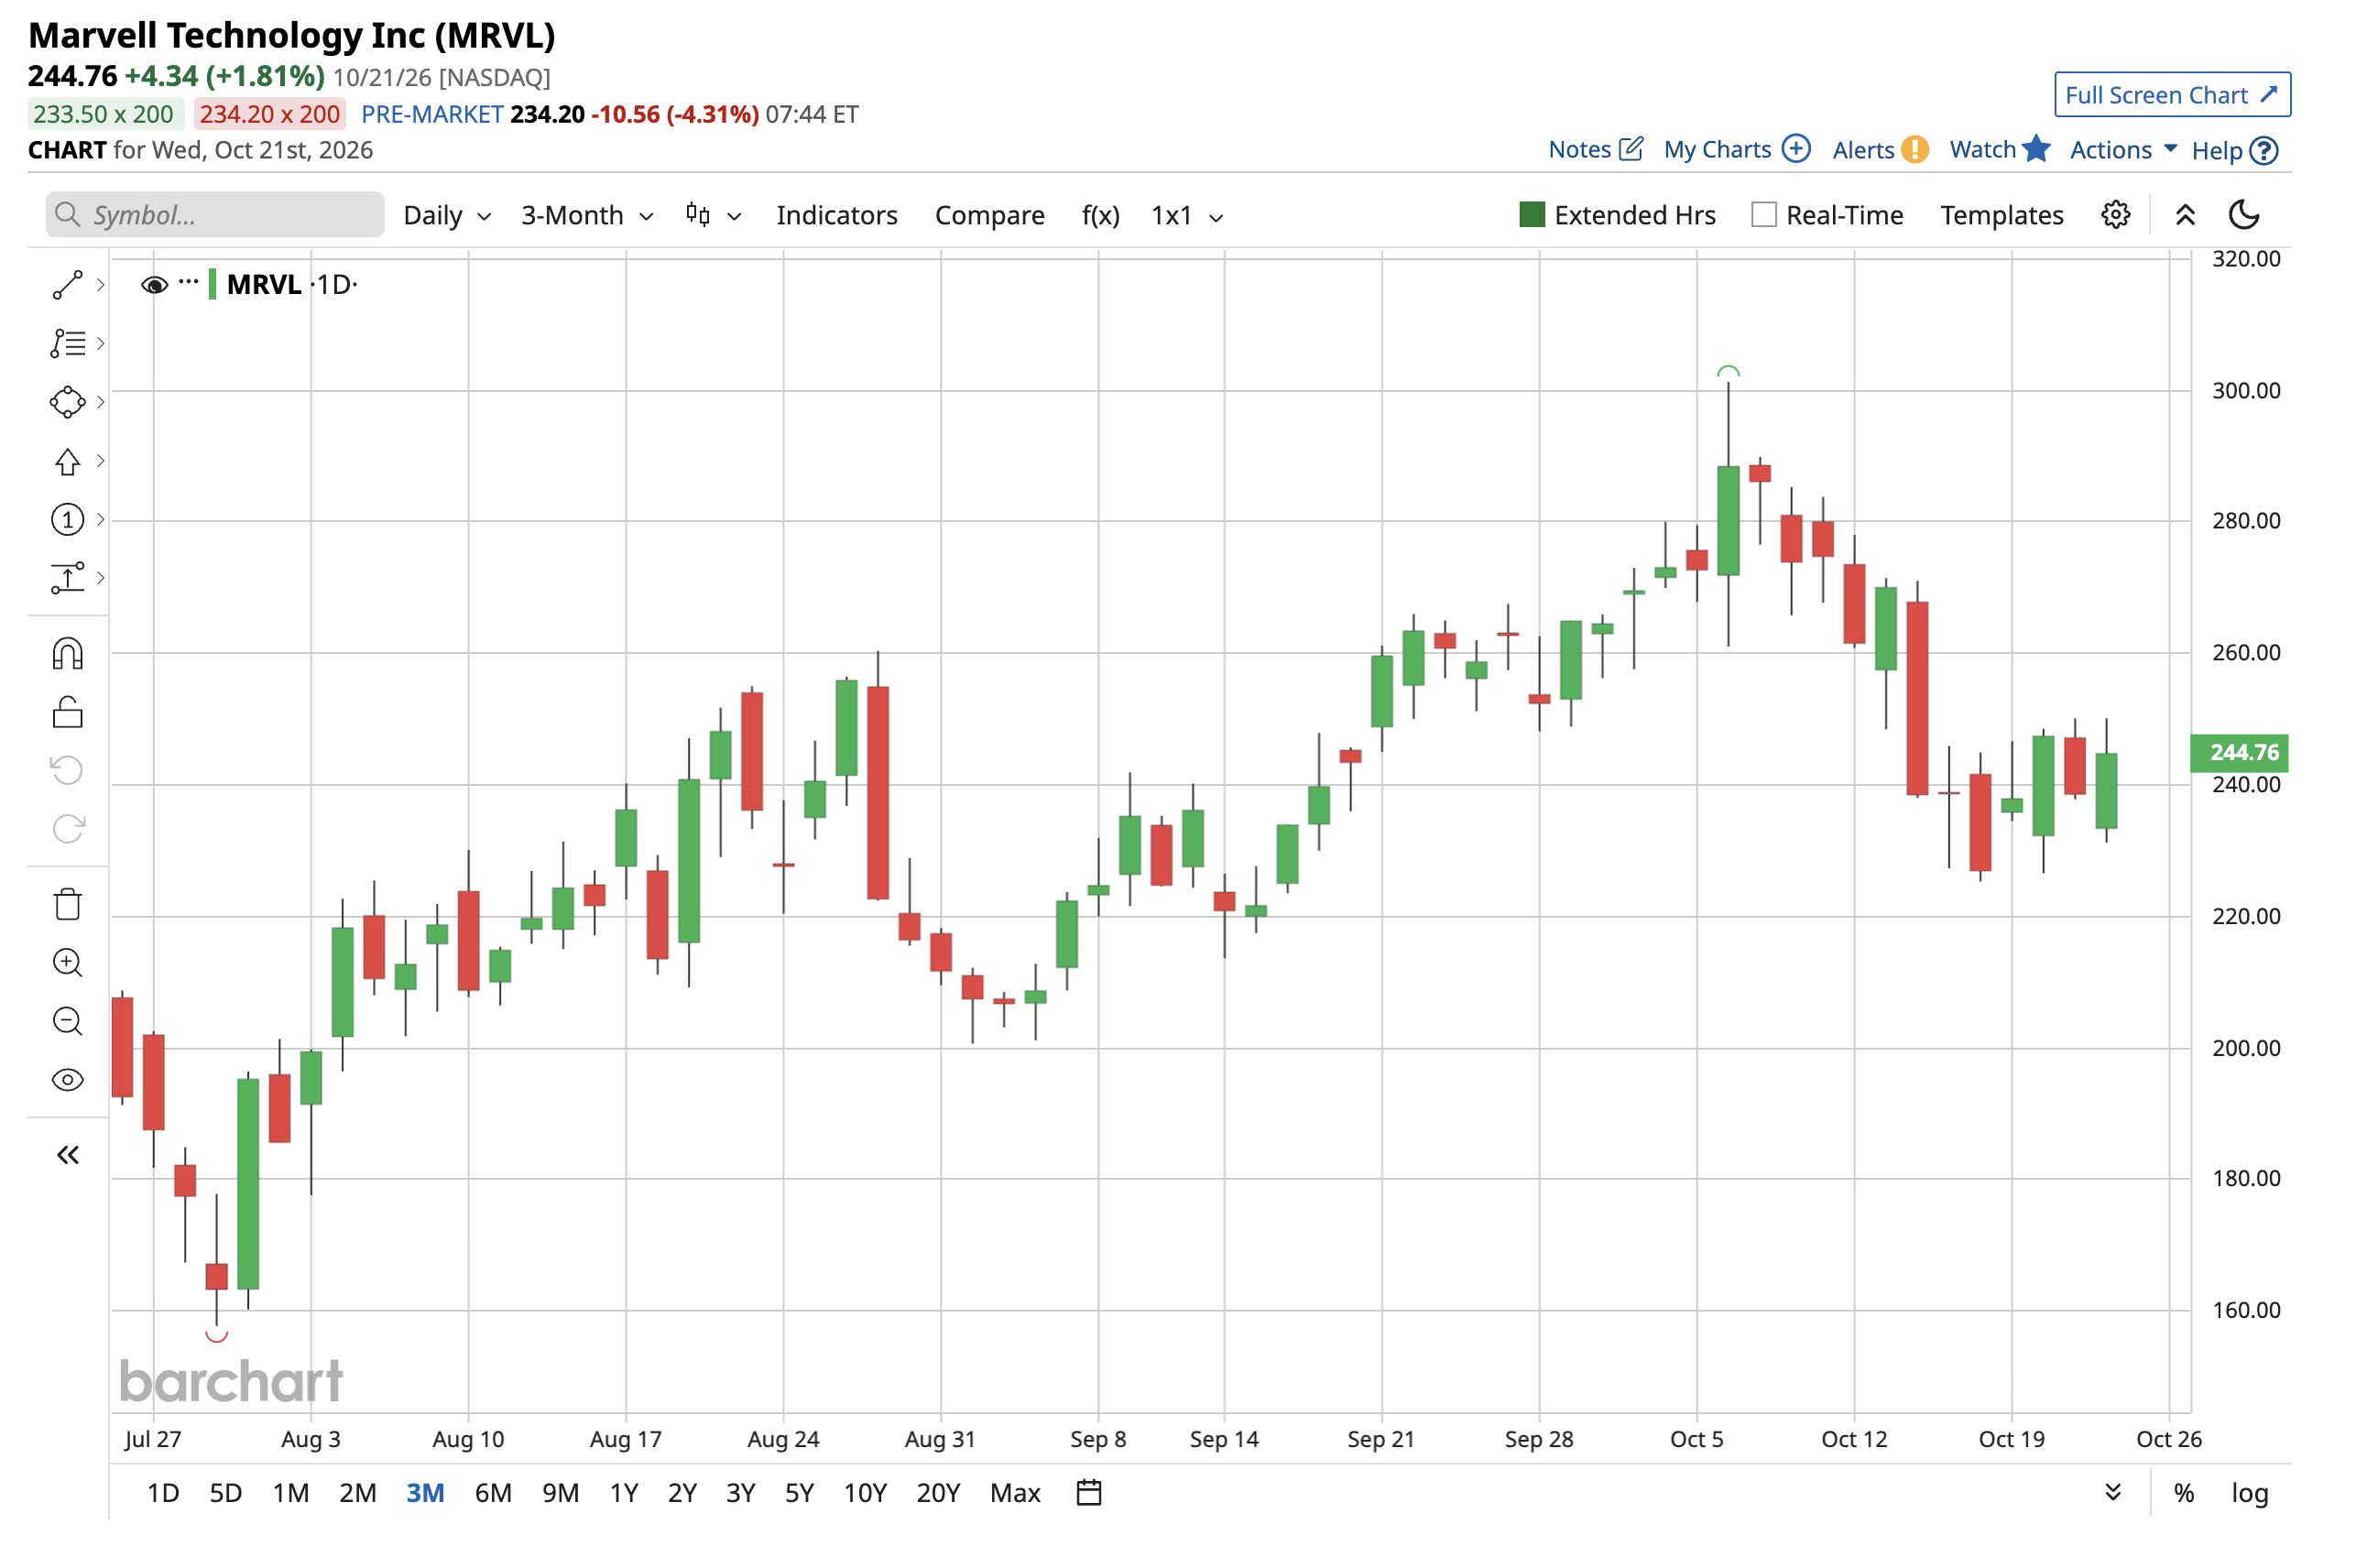
Over the last 12 months, Marvell has significantly outperformed the semiconductor sector, with the stock climbing roughly 202%. This was well above the iShares Semiconductor ETF (SOXX), which gained about 79% during the same period. The rally was driven by growing demand for AI data-center infrastructure, including custom AI chips and high-speed networking solutions. Moreover, Marvell’s fiscal 2026 revenue rose 42% to a record $8.2 billion, while data-center revenue jumped 46% to $6.1 billion.
 barchart.com
Marvell’s forward P/E of 53.98x is steep, sitting about 42% above its five-year average of 38.05x. Its forward price-to-sales ratio of 16.55x is also 61% above its historical average of 10.25x. So the stock is more expensive than usual, even as investors bet on its AI opportunity. The earnings outlook helps explain the premium. Analysts expect EPS to grow 48.6% in fiscal 2027 and 72.89% in fiscal 2028. If Marvell delivers that growth, its earnings could begin to justify the valuation.
Expensive, but Earnings Could Catch Up
Marvell Technology reported its second-quarter fiscal 2027 earnings on August 27. For Q2 fiscal 2027, data-centre revenue increased 46% YOY to $2.17 billion, representing 79% of total revenue. The data-center segment is expected to remain the key growth driver, with Marvell having expanded commercial agreements with Tier 1 hyperscalers for multiple custom products. The non-GAAP earnings per share came in at $0.94, beating the Wall Street estimates of $0.93. At the same time, Marvell reported an operating cash flow of $605.5 million. This implies an annualized OCF potential of $2.42 billion.
Since the valuation might be a potential deterrent for investors, it’s important to also talk about the growth trajectory. Marvell guided for 45% revenue growth in fiscal 2027 to $12 billion. Further, the company expects 50% revenue growth in fiscal 2028 to $18 billion. Even beyond fiscal 2028, the outlook remains positive. For example, Marvell is positioned for $10 billion to $11 billion in custom-silicon business for fiscal 2029. The company has a custom-silicon partnership with Alphabet's (GOOG) Google, which should have a meaningful impact on revenue.
What Do Analysts Expect for MRVL Stock?
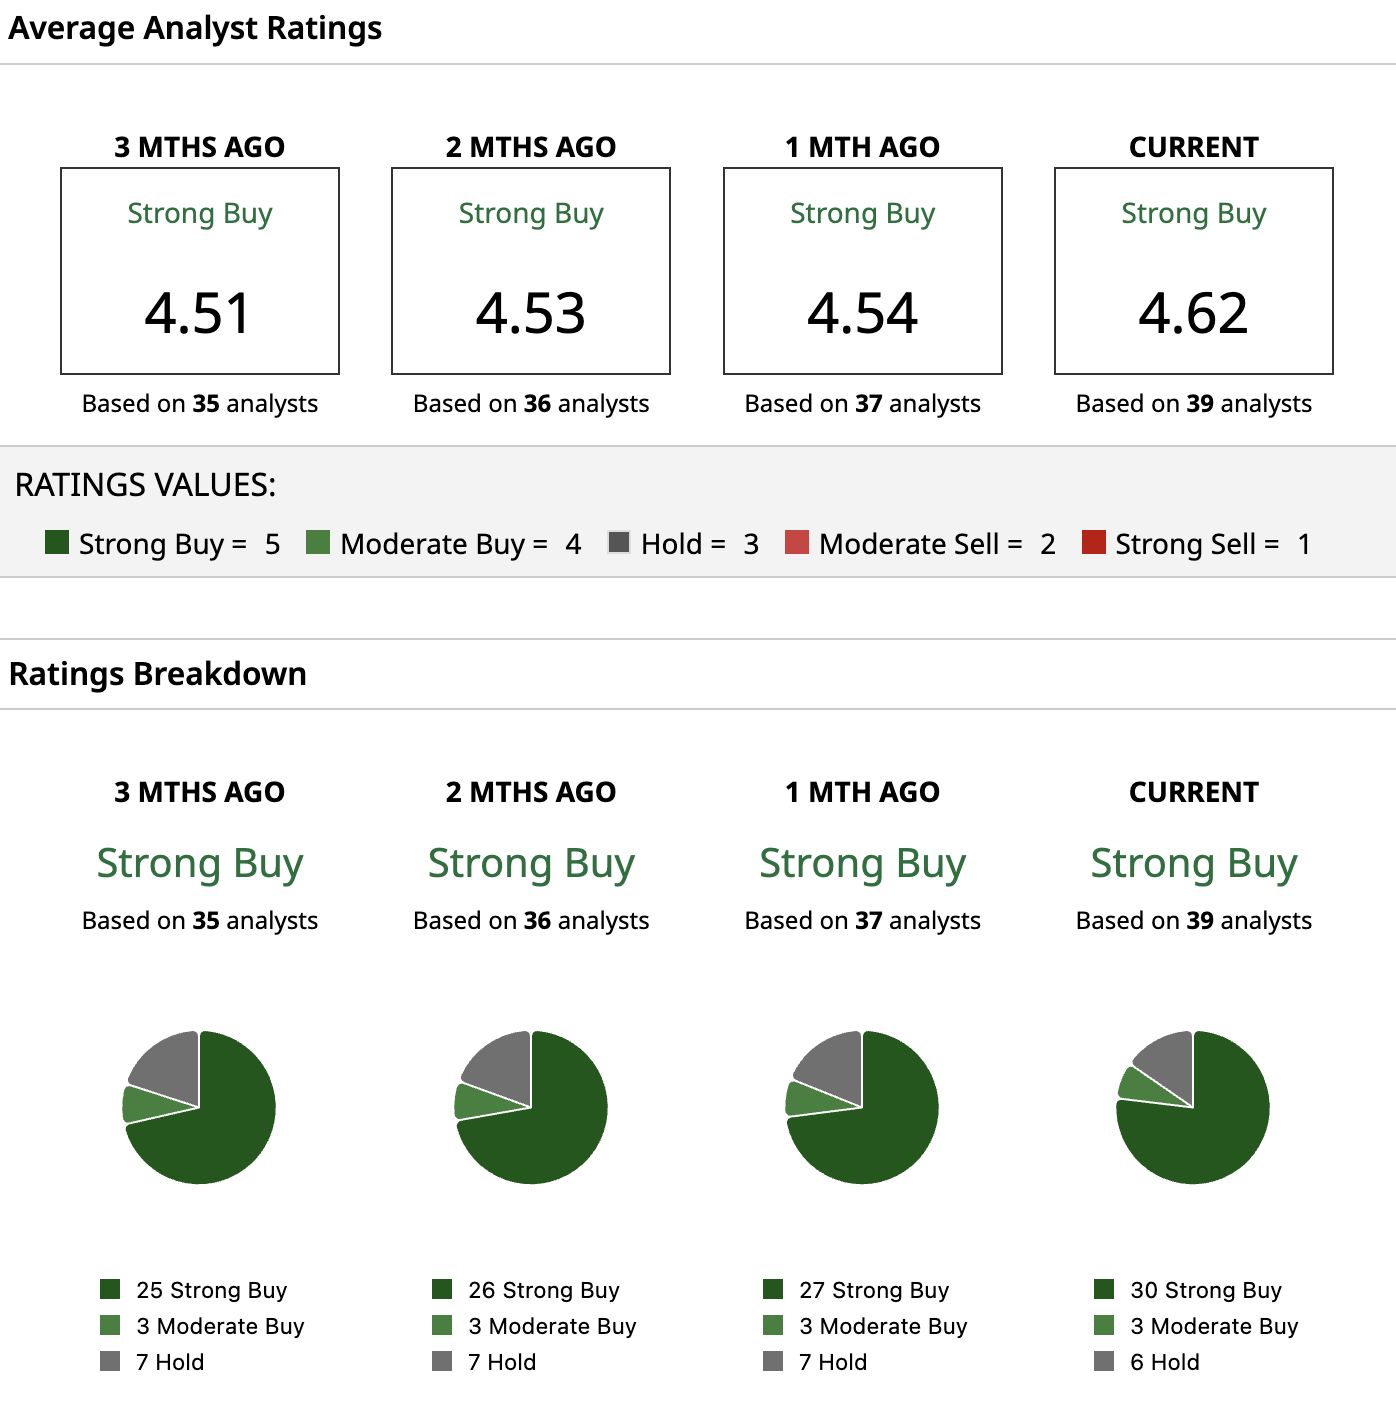
The analyst outlook for Marvell Technology is significantly positive. Based on 39 analysts with coverage, MRVL stock has a consensus “Strong Buy” rating on Wall Street. While 30 analysts have a “Strong Buy” rating for the stock, three have a “Moderate Buy,” and six have a “Hold” rating.
The mean price target of $337.05 represents potential upside of 38% from current levels. Meanwhile, the most bullish price target of $450 suggests that MRVL stock could climb as much as 84% from here.
 barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Marvell’s Road to $90B: The 3 Moves Behind the Boldest Target in AI Chips Dear SoFi Stock Fans, Mark Your Calendar for October 27 Piper Sandler Says Financing Concerns for CoreWeave Are Overblown. Not Everyone Is Convinced. Why You Should Buy Meta Stock Before It Touches $1,050