

The J.M. Smucker Co. SJM enters fiscal 2027 with stronger earnings expectations and two brands delivering double-digit growth, but the portfolio is not advancing evenly. The current fiscal-year EPS estimate has risen 7.2% in the past four weeks.
The investment question is whether Uncrustables, Cafe Bustelo and better underlying profitability can outweigh continued weakness in Sweet Baked Snacks and limited companywide revenue growth.
The J. M. Smucker Company Price, Consensus and EPS Surprise
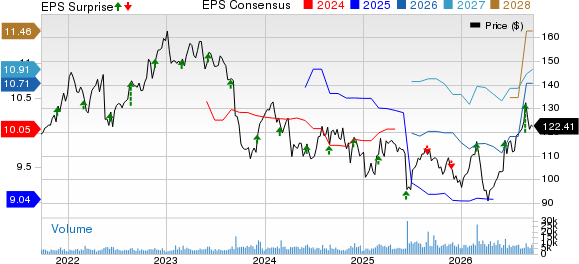
The J. M. Smucker Company price-consensus-eps-surprise-chart | The J. M. Smucker Company Quote
SJM's Growth Engines Keep Building Scale
Uncrustables delivered 12% total-company net sales growth in the first quarter of fiscal 2027, driven by double-digit volume/mix growth. The brand also reached record quarterly volume, net sales and household penetration.
Cafe Bustelo increased net sales 23%, including an 8% contribution from volume/mix. With Uncrustables household penetration at 27% and additional capacity planned at the McCalla, AL, facility, these platforms have room to become a larger part of Smucker's growth mix.
Smucker's Margin Recovery Strengthens the Earnings Case
Adjusted gross margin improved 760 basis points in the first quarter. Excluding the $115 million tariff-refund benefit, adjusted gross margin still expanded 240 basis points, showing that the improvement was not entirely refund-driven.
Lower green coffee costs are expected to support profitability, though Smucker plans to pass deflation through to consumers. That trade-off should pressure reported coffee sales as pricing resets, even as the company targets a healthier underlying cost structure.
SJM Still Needs Broader Revenue Growth
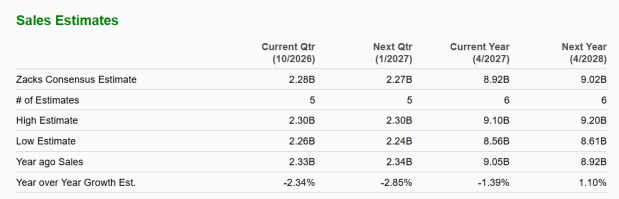
Smucker now expects fiscal 2027 net sales to decline 1%-2%, with volume/mix approximately flat. The midpoint improvement in guidance reflects better expectations for U.S. Retail Coffee and U.S. Retail Frozen Handheld and Spreads, but not broad-based expansion.
Image Source: Zacks Investment Research
Packaged-food peers show that this backdrop is not unique. General Mills, Inc. GIS reported flat organic net sales in its fiscal 2027 first quarter, while The Kraft Heinz Company KHC posted a 1.3% decline in second-quarter 2026 organic net sales. For SJM, the key issue remains whether its strongest brands can offset weaker parts of the portfolio.
Smucker's Snack and Pet Businesses Need More Progress
Sweet Baked Snacks sales fell 7% in the first quarter as volume/mix reduced sales by 8 percentage points. U.S. retail channels improved modestly and Donettes posted double-digit growth, but convenience-channel pressure and prior SKU rationalization continued to weigh on the segment.
Pet Foods sales rose just 1%, while segment profit declined 2%. Meow Mix sales increased 4%, Milk-Bone returned to volume/mix growth and Pup-Peroni gained 5%, yet broader pet-category progress is still needed for the segment to become a more dependable contributor.
SJM's Valuation Balances Opportunity and Execution Risk
SJM trades at 11.4X forward 12-month earnings, below 14.2X for its Zacks sub-industry and 16.8X for the sector. The relative discount gives investors some valuation support as earnings expectations improve.
The multiple is also close to SJM's five-year median of 11.9X. That means the shares are not unusually cheap relative to their own history, leaving earnings delivery, margin follow-through and wider portfolio stabilization central to the valuation case.
SJM's Mixed Style Profile Keeps Execution in Focus
SJM's setup supports a patient rather than one-sided reading. Growth brands are scaling, underlying margins are improving and earnings expectations have moved higher, but fiscal-year sales are still projected to decline and several businesses need better volume performance.
The stock currently carries a Zacks Rank #3 (Hold), with a Growth Score of A, VGM Score of A, Value Score of B and Momentum Score of F. The strong Growth and VGM scores and favorable Value score sit alongside weak momentum. Within the Zacks framework, that mix keeps the focus on execution and broader operating improvement rather than on valuation alone. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The J. M. Smucker Company (SJM): Free Stock Analysis Report
General Mills, Inc. (GIS): Free Stock Analysis Report
Kraft Heinz Company (KHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).