

Anthropic’s (ANT) IPO dominated Thursday as investors piled into the AI giant. It closed the day up 17% at $97.17. That enthusiasm didn’t carry over to the rest of the markets.
All three major indices lost more than 2% yesterday. As a result, the S&P 500 is down more than 5% so far in November, while the Nasdaq 100 is off over 7%. With 17.5 trading days left in 2026, both could finish the year in negative territory.
Can’t Get Enough Options?: Join the list for Barchart’s daily unusual options report, delivered free.
You don’t hear much about market strength from the White House these days. Rightfully so. The current situation could get much worse if the U.S. resumes its war with Iran or the Nvidia (NVDA) situation continues to spiral. But these are all topics for people well beyond my pay grade.
In yesterday’s unusual options activity, Carlyle Group (CG), one of the country’s largest alternative asset managers with $479 billion in AUM, had the second- and third-highest Vol/OI (volume-to-open-interest) ratios yesterday for puts and calls expiring in six days or more.
I’ve owned shares of the VanEck Alternative Asset Manager ETF (GPZ) for some time. It’s my way to access alternative assets easily. As I anticipated, it hasn't been an easy ride since the fund’s inception in June 2025, down 12% over the past 18 months from its $25 initial price.
I’m a patient investor, so I’m not particularly concerned about the losses, but if you’re not tolerant of major swings in stock prices, GPZ is not for you. But I digress.
In addition to Carlyle’s two unusually active options yesterday, four others from U.S.-listed alternative asset managers held by GPZ achieved notable options activity.
While several options strategies are available to investors based on the six shown below, I’ll focus on Carlyle’s two leaders.
Have an excellent weekend!
The CG Options in Question
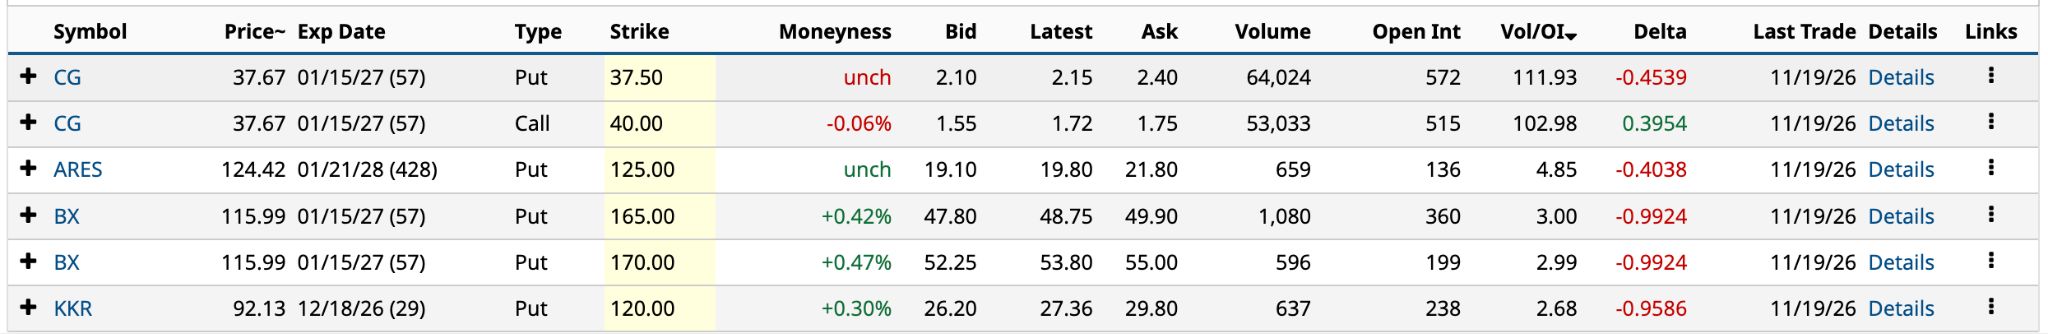
As you can see above, the two Carlyle options accounted for most of the unusual options activity among alternative asset managers yesterday, so they’ll be the focus of my trade to consider.
Carlyle Group Shouldn’t Be Overlooked
As I mentioned, the D.C.-based firm has almost $500 billion in AUM across three segments: Global Private Equity (59% of segment revenue), Global Credit (28%), and Carlyle AlpInvest (13%). The first two are self-explanatory. They make direct investments on behalf of their institutional clients, whereas the last segment, formerly called Global Financial Solutions, invests in funds managed by other asset managers.
Like most of its peers, its revenues vary considerably from year to year depending on performance allocations, commonly referred to as carried interest, which is its share of profits from investments made and sold on behalf of its clients. This carried interest is often 20% of those profits. For example, it generated $6.08 billion in 2021, but only $1.33 billion in 2022. That’s part of the business you can’t avoid.
So, analyzing companies like Carlyle takes more time than a consumer-focused company like Nike (NKE) because their financial statements have so many moving parts.
For example, in Q3 2026, it had total segment revenue of $994.5 million. Still, after accounting for $562.0 million in overhead, employee compensation including performance-based pay, interest expense, etc., you’re left with distributable earnings of $432.5 million. That is pre-tax. After tax, it worked out to $397.1 million, or $1.12 per share, up from $ 1.07 in Q3 2025.
I love businesses with lots of moving parts. It really makes you focus on how the business makes money. I wouldn’t say Carlyle is my favorite GPZ holding — that goes to Brookfield (BN), the ETF’s largest holding with a 12.93% weighting — but the unusual options activity makes it worth discussing.
Carlyle’s $2.72 Million Ratio Collar
A quick look at Carlyle’s options flow from yesterday suggests an institution was hedging a long position in CG stock by implementing a Ratio Collar--which differs from a standard Protective Collar where you own 100 shares of stock, buy 1 OTM (out of the money) put to protect your downside, and sell one OTM call to offset some of the put’s cost--which skews the calls/puts from a traditional 1:1 ratio.

The above shows three trades that took place at 11:18:50 ET yesterday. The calls-to-puts ratio was approximately 1.2:1. The institution paid $12.93 million for downside protection on 6.4 million shares by buying 64,000 Jan. 15/2027 $37.50 put contracts, while offsetting the cost of the protection by selling 53,000 Jan. 15/2027 $40 call contracts for $10.21 million in premium, resulting in a net debit of $2.72 million.
Why would they do that? For two reasons.
First, they have protected their downside on 6.4 million shares held below $35.48 [$37.50 strike price - $2.02 per share put cost]. Maybe they bought shares in 2022 or 2023 when CG traded in the mid-20s. Or perhaps they just bought, see upside down the road, but understand we’re in a volatile market — the VIX is at one of its highest levels over the past five years.
Secondly, in addition to downside protection on 6.4 million shares, selling 53,000 calls capped the upside on 5.3 million shares at $40, leaving 1.1 million shares uncapped so the institution can still participate if CG rallies strongly before January 2027.
On the date of publication, Will Ashworth had a position in: GPZ . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
What Unusual Options Activity in Carlyle Group Stock Tells Us Now — and the Ratio Collar Trade in Question This Payments Stock Is a Triple Threat with Profitability, Momentum, and Robust Growth Coatue Management Just Bought 8 Million Shares of Salesforce Stock. Why Investors Should Care. Wall Street Promised Nvidia $500 Billion. Michael Burry Wants to Know Where It Is.