

The U.S. communication components industry has been benefiting from healthy demand trends driven by the fast-track 5G deployment and the transition to cloud and fiber networks. As both consumers and enterprises are using networks more extensively, there is tremendous demand for quality networking components.
The Zacks-defined Communication - Components industry is currently in the top 7% of the Zacks Industry Rank. Over the past year, the industry has provided a massive 169.4% returns, while its year-to-date return is 118.6%. Since it is ranked in the top half of the Zacks Ranked Industries, we expect it to outperform the market over the next three to six months.
Here, we recommend two bigwigs — Corning Inc. GLW and Ciena Corp. CIEN — from the communication components industry for investment. These stocks have flourished this year. Despite the rally, they have double-digit price upside left in the near term.
Each of our picks currently carries either a Zacks Rank #1 (Strong Buy) or 2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
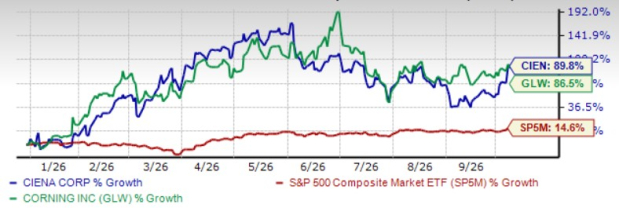
The chart below shows the price performance of our two picks year to date.
Image Source: Zacks Investment Research
Corning Inc.
Corning entered the second half of 2026 with its growth outlook tied to AI infrastructure and optical connectivity. Revenue growth was primarily led by Optical Communications and Solar segments. Enterprise Networks sales jumped supported by accelerating demand for generative AI infrastructure. Core operating margin also expanded as higher volumes and improved execution strengthened profitability.
GLW continues to strengthen its competitive position through innovation across optical connectivity, advanced glass and semiconductor applications. The company recently launched Gorilla Glass Ceramic 3 and continues to see opportunities for advanced optics products tied to AI-driven data center build-outs and semiconductor manufacturing demand. GLW is expanding its Generative AI optical portfolio with multicore fiber and high-density connectivity solutions that improve network capacity and reduce installation complexity.
AI and Optical Communications Momentum
Enterprise Networks drove the improvement as hyperscale customers expanded AI-related data center capacity. GLW announced multiyear agreements with Amazon.Com Inc. AMZN and NVIDIA Corp. NVDA, supporting further demand for optical fiber, cable and connectivity products. The NVDA partnership plans to increase U.S. optical connectivity manufacturing capacity tenfold and expand domestic fiber production capacity by more than 50%.
Strong Guidance
For the third quarter, management expects core sales between $4.9 billion and $5 billion, representing approximately 16% year-over-year growth. Core earnings are projected between 85 cents and 89 cents per share, implying growth of roughly 28%.
Corning continues to target an annualized sales run rate of $20 billion by the end of 2026 under its upgraded Springboard Plan. The company also aims to reach $30 billion by the end of 2028 and $40 billion by the end of 2030, supported by AI infrastructure, solar expansion and deeper customer partnerships.
Solid Estimate Revisions
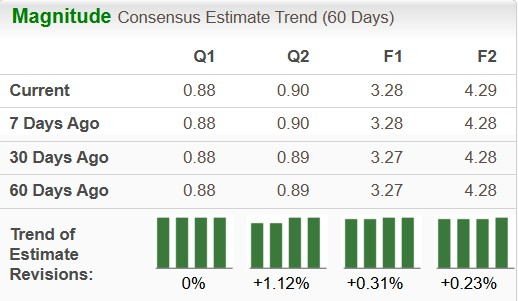
Corning has an expected revenue and earnings growth rate of 16% and 30.2%, respectively, for the current year. The Zacks Consensus Estimate for the current year’s earnings has improved 0.3% over the last 30 days.
GLW has an expected revenue and earnings growth rate of 18% and 30.7%, respectively, for the next year. The Zacks Consensus Estimate for next year’s earnings has improved 0.2% over the last seven days.
Image Source: Zacks Investment Research
Robust Price Upside Potential
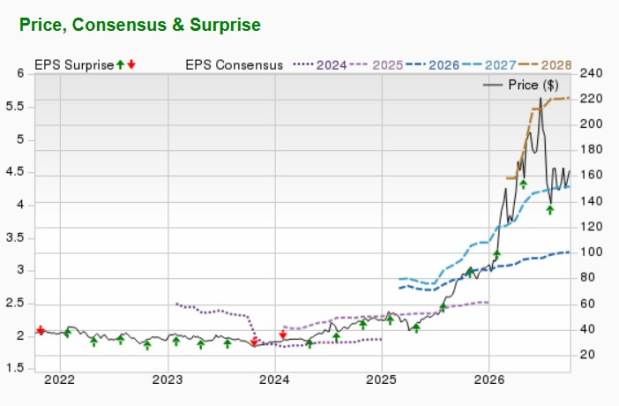
The short-term average price target of brokerage firms represents an increase of 14% from the last closing price of $163.25. The brokerage target price is currently in the range of $129-$238. This indicates a maximum upside of 45.8% and a downside of 21%.
Image Source: Zacks Investment Research
Ciena Corp.
Zacks Rank #1 Ciena is witnessing encouraging demand trends as AI applications drive higher network traffic and bandwidth consumption across cloud and service provider environments. Customers are prioritizing investments in network infrastructure to support AI model training, data ingestion and inference workloads.
CIEN continues to expect its addressable market to reach roughly $50 billion by 2029 as growth extends from traditional WAN into data center connectivity. Fiscal third-quarter 2026 backlog rose to $8.5 billion and is expected to exceed $10 billion at year-end.
Expanding Data Center Connectivity Opportunity
Ciena's revenues are primarily generated from packet optical transport, switching products, integrated networks and software platforms. The company continues to diversify its footprint in data center connectivity and AI networking infrastructure. In the last reported quarter, direct cloud provider revenue rose 82% year over year and represented 53% of sales, while interconnects more than doubled.
WaveLogic 6 Nano 800ZR shipments more than doubled sequentially, and CIEN received Vesta sample orders from several anchor customers. CPX revenue is expected to begin in 2027 and ramp in 2028. These developments broaden Ciena's reach across optical systems, modules and components.
Strong Guidance
For fourth-quarter fiscal 2026, CIEN expects revenue of $1.75 billion (+/- $50 million). Adjusted gross margin is projected at 45% (+/- 50 bps), and adjusted operating expenses are expected to be $415 million (+/- $10 million). Adjusted operating margin is forecast at 20% (+/- 50 bps).
Ciena raised fiscal 2026 revenue guidance to $6.42 billion (+/- $50 million), implying 35% year-over-year growth at the midpoint. For fiscal 2027, management’s early view indicates at least 30% revenue growth, an adjusted gross margin of 45-46%, and an adjusted operating margin of 25-27%.
Solid Estimate Revisions
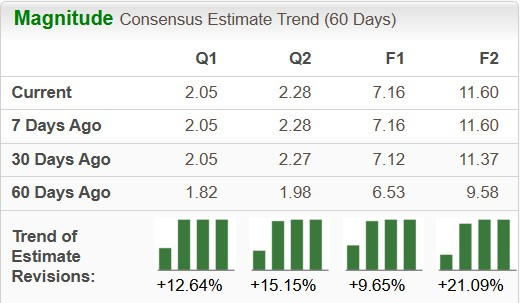
Ciena has an expected revenue and earnings growth rate of 34.6% and more than 100%, respectively, for the current year (ending October 2026). The Zacks Consensus Estimate for the current year’s earnings has improved 0.6% over the last 30 days.
CIEN has an expected revenue and earnings growth rate of 18% and 30.7%, respectively, for the next year. The Zacks Consensus Estimate for next year’s earnings has improved 0.2% over the last seven days.
Image Source: Zacks Investment Research
Robust Price Upside Potential
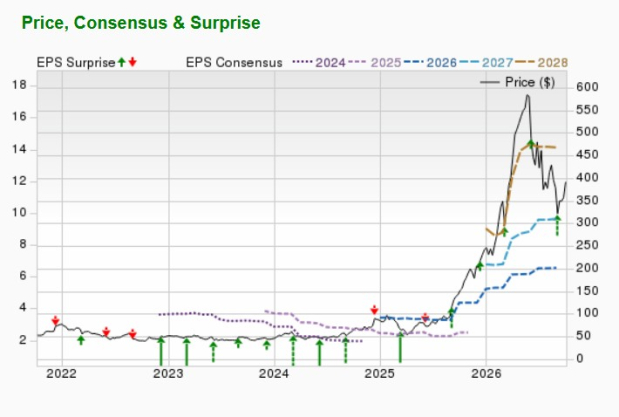
The short-term average price target of brokerage firms represents an increase of 17.7% from the last closing price of $446.45. The brokerage target price is currently in the range of $347-$660. This indicates a maximum upside of 47.8% and a downside of 22.3%.
Image Source: Zacks Investment Research
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ciena Corporation (CIEN): Free Stock Analysis Report
Corning Incorporated (GLW): Free Stock Analysis Report
Amazon.com, Inc. (AMZN): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).