

Higher borrowing costs have made residential solar installations harder for homeowners to afford, while the expiration of the federal tax incentive has added another hurdle. Against this backdrop, Enphase Energy (ENPH) has faced weaker demand across its major geographical markets.
So much so that on Tuesday, Oct. 27, Enphase’s shares fell nearly 2%, followed by a bruising 16% plunge in the next trading session after the company reported Q3 FY2026 earnings and revenue below analyst expectations. Management then deepened the gloom with Q4 guidance that came in well below Wall Street forecasts.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
However, heading into 2027, Enphase is banking on five growth drivers, including its new IQ Battery G5, prepaid solar leasing plans, commercial solar and battery solutions, electric vehicle (EV) chargers that can charge vehicles or send power back to the grid, and advanced power technology designed for next-generation artificial intelligence (AI) data centers.
These strategies might give Enphase several avenues to pursue growth beyond its current difficulties. However, after the share price rout, the central question is whether ENPH stock offers an attractive entry point or whether another round of disappointment could follow.
About Enphase Stock
Enphase Energy develops clean energy technology and commands a market cap of nearly $3.3 billion. Headquartered in Fremont, California, the company specializes in solar microinverters, battery storage systems, energy management software, and EV charging solutions for residential and commercial customers worldwide.
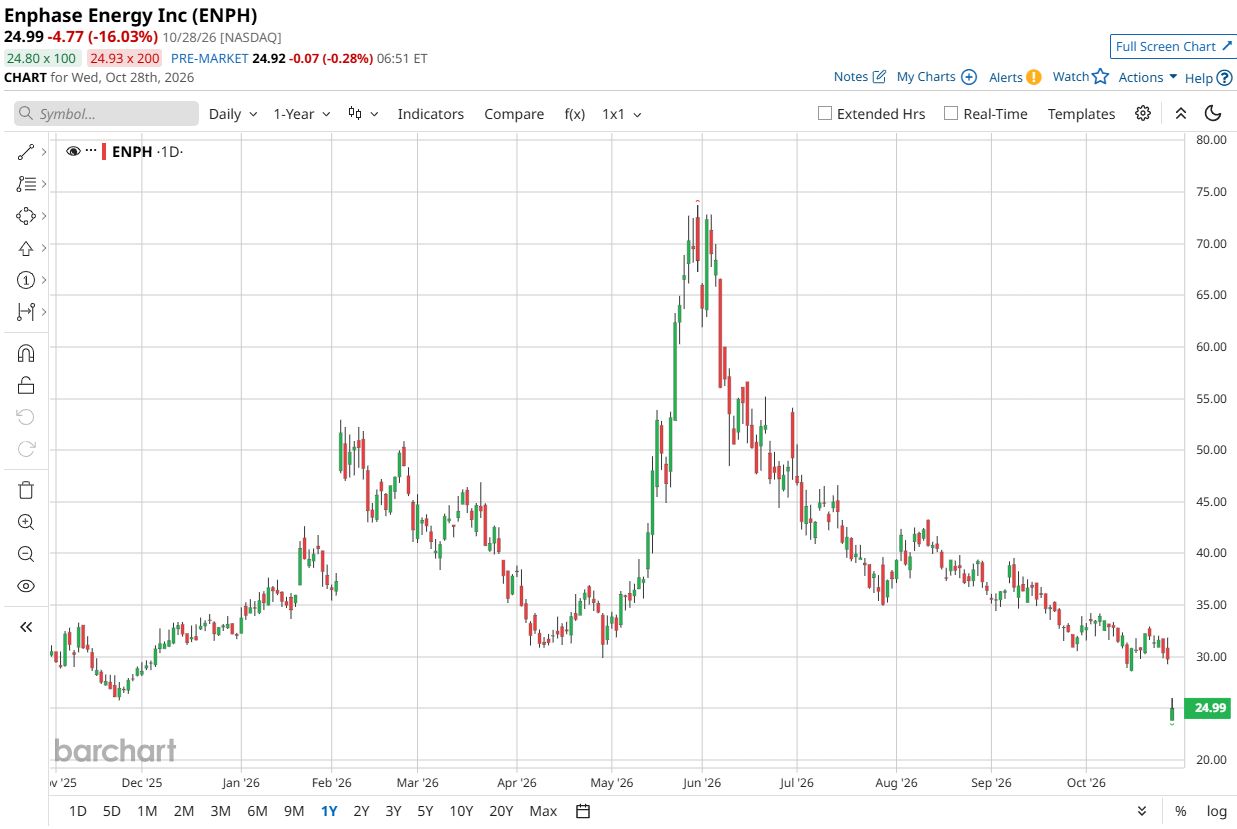
However, weaker household spending and expensive financing have created a difficult backdrop. ENPH stock has plunged 31.9% over the past 52 weeks and declined 22% year-to-date (YTD). Shares also lost 19.2% over the past month, extending a painful stretch for anyone hoping for a quick recovery.
 www.barchart.com
The prolonged decline has brought ENPH's valuation below its historical benchmarks. The stock is currently trading at 15.66 times forward adjusted earnings, a discount to both the industry average and its own five-year average multiple. The gap might attract bargain hunters, but a cheaper valuation alone cannot offset earnings pressure.
Enphase Misses on Q3 Earnings
Enphase's Q3 FY2026 report, released on Oct. 27, delivered a double disappointment. Revenue tumbled 28.5% year over year (YOY) to $293.3 million, missing analysts' expectations of $306.1 million. Non-GAAP EPS reached $0.41, down from the year-ago level and below Wall Street's estimate of $0.50.
Regional results revealed how uneven demand remains across the company's markets. U.S. revenue grew approximately 3%, but the increase fell short of expectations as residential solar installations remained subdued.
Europe faced greater pressure, with revenue declining approximately 11% amid summer seasonality and continued weakness in certain solar markets. Even non-GAAP operating income declined 56.6% from the year-ago level to $53.6 million, while non-GAAP net income fell 54% YOY to $54 million.
Battery shipments, however, provided one encouraging development. Enphase shipped 129.9 MWh of IQ Batteries in Q3, up from 113.8 MWh in Q2. Its certified installer network also expanded to more than 26,000 installers worldwide, up from more than 25,000 in the previous quarter.
But this progress could not offset the company's cautious Q4 outlook. Enphase expects current-period revenue to range from $225 million to $255 million, including shipments of 100 to 120 MWh of IQ Batteries. The guidance fell well below analysts' revenue estimate of $298.6 million, leaving little room for optimism about the immediate outlook.
On the other hand, analysts expect earnings to remain under pressure in the near term. Q4 EPS is expected to decline 36.4% YOY to $0.21, while full-year EPS is projected to drop 56.9% from the previous year to $0.66. However, FY2027 offers a more encouraging picture, with analysts forecasting a 30.3% YOY EPS increase to $0.86.
What Do Analysts Expect for Enphase Stock?
Analysts have already adjusted their expectations following the earnings miss and weaker outlook. JPMorgan analyst Mark Strouse reduced his price target to $29 from $35 while maintaining a “Neutral” rating. He pointed to softer economic conditions across Enphase's markets and the company's decision to cut distributor shipments ahead of Q1.
Oppenheimer adopted a more cautious position by downgrading Enphase Energy to “Perform” from “Outperform” and withdrawing its price target. Its assessment that a recovery in Enphase's core business "is not materializing" highlights the difficulty of making a convincing case for an immediate turnaround.
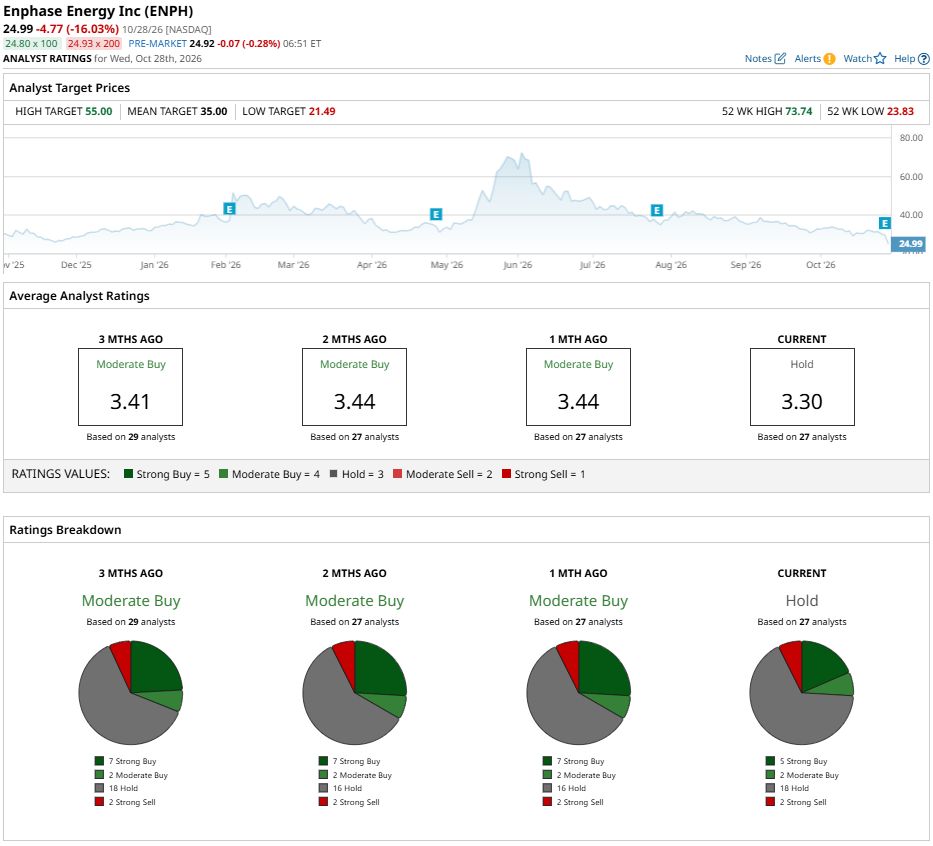
The broader analyst consensus reflects that uncertainty. Across Wall Street, the overall rating is a “Hold.” Of the 27 analysts covering ENPH stock, five assign it a “Strong Buy” rating, two recommend a “Moderate Buy,” 18 maintain a “Hold” rating, and two issue a “Strong Sell.”
As for price targets, the average estimate of $35 points to potential upside of 40.1%, while the Street-High target of $55 suggests a gain of 120.1% from current levels. These targets leave room for a rebound, although Enphase must deliver a stronger performance to turn Wall Street's optimism into reality.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Alphabet's Earnings Horror Show Continues, But GOOG Stock Is a Buy Below $300 Reddit Sinks as Google's AI Shift Takes a Bite Out of Search Traffic. What's Next for RDDT Stock. How to Play the Nasty Post-Earnings Selloff in Enphase Stock Oracle Surges 10% on Ambitious New Targets: 3 Questions to Answer Before Dumping ORCL Stock