

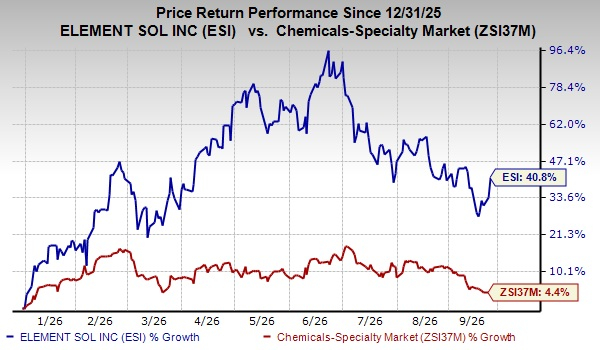
Element Solutions Inc.’s ESI shares have rallied 40.8% year to date. The company has also outperformed the Zacks Chemical - Specialty industry’s 4.4% rise over the same time frame.
ESI’s shares have soared on the stronger 2026 outlook, supported by higher EBITDA guidance and expectations for approximately 20% adjusted EPS growth. Strong AI-driven electronics demand, improving cash generation and continued operational efficiencies could further support investor sentiment.
Let’s take a look at the factors that are driving ESI stock.
AI-Driven Electronics Demand Supports Long-Term Growth
Element Solutions remains well-positioned in structurally growing end markets such as high-performance computing, data centers and advanced electronics, with the second quarter demonstrating continued strength in demand tied to AI infrastructure. Electronics organic sales increased 20% in the second quarter, led by Semiconductor Solutions, while demand remained strong for advanced semiconductor packaging, advanced PCB chemistries, engineered assembly materials and metallization solutions supporting data centers and high-performance computing.
The company is also benefiting from growing demand for thermal interface materials used in high-power AI GPUs and CPUs, highlighting its exposure to increasing power density and thermal-management requirements. Customer engagements continue to accelerate as technical requirements become more complex, reinforcing the company's positioning in innovation-led specialty chemistries and supporting durable long-term growth.
Operational Efficiency Supports Profitability
Element Solutions continues to benefit from operational efficiency initiatives, with procurement, supply-chain optimization and productivity improvements supporting profitability. The company is making progress in inventory management following several years of supply-chain disruption, while flexible supply-chain capabilities are helping improve cost efficiency and maintain customer service. Management also continues to focus on procurement discipline and productivity improvements, particularly within the Industrial business, where these initiatives have helped offset weaker volumes and preserve profitability.
Improved Cash Generation Strengthens Liquidity
Element Solutions concluded the second quarter of 2026 with cash and cash equivalents of $189.6 million, up from $177.3 million in the prior quarter. Cash flows from operating activities were $99.6 million in the second quarter, up from $72.6 million a year ago. Free cash flow rose to $73.7 million, demonstrating stronger quarterly cash generation.
Upbeat Outlook Adds to Optimism
Element Solutions, in July 2026, raised its 2026 adjusted EBITDA guidance to $690-$710 million from $665-$685 million, reflecting stronger organic growth, contributions from the Micromax and EFC acquisitions and progress on the Kuprion scale-up. The company expects adjusted EPS to grow approximately 20% in 2026 and projects third-quarter adjusted EBITDA of about $180 million.
Management said core markets remain healthy and customer engagement is accelerating. Continued operational execution and disciplined capital allocation are expected to support profit growth.
ESI’s Zacks Rank & Key Picks
ESI currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks in the Basic Materials space are Intrepid Potash, Inc. IPI, Innospec Inc. IOSP and Avient Corporation AVNT. IPI currently sports a Zacks Rank #1 (Strong Buy), while IOSP and AVNT carry a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for IPI’s current-year earnings stands at $1.86 per share, implying a 29.2% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in three of the trailing four quarters and missed once, with the average surprise being 37.4%. Shares of the company have risen about 34.2% year to date.
The Zacks Consensus Estimate for IOSP’s fiscal current-year earnings is pegged at $5.03 per share, implying a 4.55% year-over-year decrease. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average surprise being 12.9%. Shares of IOSP have gained around 25.5% year to date.
The Zacks Consensus Estimate for AVNT’s current-year earnings is pegged at $3.2 per share, indicating a 13.5% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average surprise being 3.4%. Shares of AVNT have surged around 32% year to date.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Element Solutions Inc. (ESI): Free Stock Analysis Report
Intrepid Potash, Inc (IPI): Free Stock Analysis Report
Innospec Inc. (IOSP): Free Stock Analysis Report
Avient Corporation (AVNT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).