

BWX Technologies, Inc. BWXT is expanding across defense and commercial nuclear markets, but the investment decision is less straightforward than the growth narrative alone suggests. The company is carrying a large backlog, raising guidance and adding capacity as demand builds.
Investors still have to weigh that momentum against a valuation near BWXT’s own five-year norm and an outlook that requires dependable second-half execution. The question is whether the growth profile justifies buying now or whether waiting for more operating evidence is prudent.
BWXT Growth Is Broadening Across Nuclear Markets
BWXT’s opportunity set spans naval propulsion, uranium enrichment, commercial nuclear equipment and lifecycle services. In May 2026, the company received more than $1.4 billion of U.S. Naval Nuclear Propulsion Program contracts, including nearly $1.29 billion for long-lead materials and $165 million for Ford-class carrier work.
The company is also advancing a planned defense uranium-enrichment facility tied to a previously announced $1.5 billion National Nuclear Security Administration contract. BWXT began Nuclear Regulatory Commission engagement in April 2026, with a license application expected in the first quarter of 2027. Curtiss-Wright Corporation CW offers a useful industry comparison because its Naval & Power segment serves both U.S. naval nuclear programs and commercial nuclear customers.
BWXT Valuation Sits Near Its Five-Year Median
BWXT trades at 27.10X forward 12-month earnings, almost in line with its five-year median of 27.46X. That is below the Zacks sub-industry multiple of 31.38X and the Zacks sector multiple of 28.51X.
The stock is therefore not priced near the high end of its historical range, but the current multiple does not indicate an obvious bargain either. The valuation still assumes that BWXT can convert nuclear demand and backlog into durable earnings growth. Huntington Ingalls Industries, Inc. HII, whose Newport News Shipbuilding division builds nuclear-powered aircraft carriers and submarines, underscores the long-cycle nature of the naval nuclear market that supports part of BWXT’s opportunity base.
BWXT Guidance Supports the Fundamental Case
Management raised its 2026 outlook after the first half. BWXT now expects revenues of about $3.80 billion, adjusted earnings of $4.70-$4.80 per share, adjusted EBITDA of $662-$672 million and free cash flow of $345-$360 million.
The higher outlook strengthens the fundamental case because the revisions span earnings, cash flow and operating profit. Yet, the guidance also keeps the focus on delivery. Approximately 55% of second-half 2026 earnings are expected in the fourth quarter, increasing the importance of execution late in the year.
BWXT Still Faces Margin and Award-Timing Risks
Commercial Operations is expanding quickly, but growth is capital intensive. BWXT lowered 2026 Commercial adjusted EBITDA margin guidance to about 13% from about 14% as it invests in U.S. capacity, the Precision Components Group acquisition and Canada.
New awards are another source of uncertainty. Management sees a credible opportunity to secure at least one new-build nuclear equipment order before year-end 2026, but customer, procurement and regulatory timing can shift. Government Operations can also experience quarterly variability from contract mix and favorable adjustments, so backlog should not be treated as guaranteed near-term earnings.
BWXT Signals Favor a Balanced Investment View
BWXT’s growth story is supported by diversified nuclear demand, higher guidance and a valuation below its sub-industry average. At the same time, a forward P/E near the company’s five-year median leaves less room for execution shortfalls than a deeply discounted valuation would.
The supported Neutral stance remains appropriate, balancing favorable nuclear demand and reasonable relative valuation against margin pressure, award timing and the concentration of second-half earnings in the fourth quarter.
BWXT Stock Price Movement
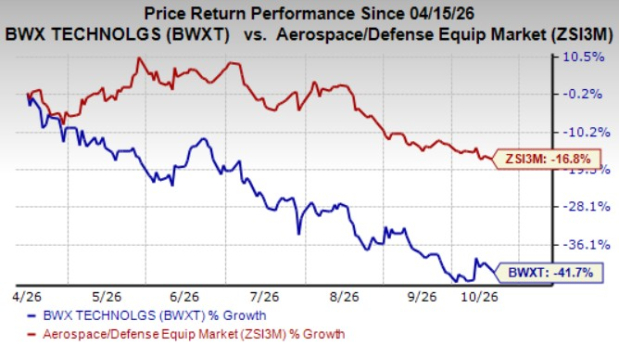
In the past six months, BWX Technologies shares have fallen 41.7% compared with the industry’s decline of 16.8%.
Image Source: Bigstock
BWXT’s Zacks Rank
BWX Technologies currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BWX Technologies, Inc. (BWXT): Free Stock Analysis Report
Huntington Ingalls Industries, Inc. (HII): Free Stock Analysis Report
Curtiss-Wright Corporation (CW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).