

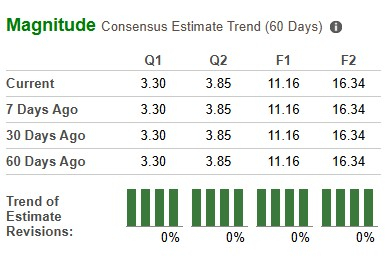
Silicon Motion Technology Corporation SIMO is scheduled to report third-quarter 2026 earnings after the closing bell on Oct. 28. The Zacks Consensus Estimate for sales and earnings is pegged at $532.8 million and $3.3 per share, respectively. Earnings estimates for SIMO for 2026 and 2027 have remained unchanged over the past 60 days.
SIMO Estimate Trend
Image Source: Zacks Investment Research
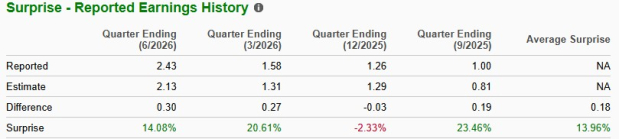
Earnings Surprise History
The leading NAND flash controller designer has a modest trailing four-quarter earnings surprise history, having exceeded expectations on three occasions. It delivered a four-quarter earnings surprise of 13.96%, on average. In the last reported quarter, the company delivered an earnings surprise of 14.08%.
Image Source: Zacks Investment Research
Earnings Whispers
Our proven model does not conclusively predict an earnings beat for SIMO for the third quarter. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. That is not the case here. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Silicon Motion currently has an ESP of 0.00% and carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping Upcoming Results
During the quarter, Silicon Motion unveiled its MonTitan SSD Reference Design Kit, targeting AI infrastructure with high-performance, scalable storage solutions. The kit helps accelerate SSD development, enabling faster data processing, improved efficiency and optimized storage performance for demanding AI workloads, data centers and next-generation computing systems.
The company is expected to benefit from growing demand for enterprise storage solutions, AI infrastructure and automotive applications in the third quarter of 2026. Management expects revenues to increase 15-20% sequentially, supported primarily by its Ferri automotive storage products, enterprise boot drive solutions and MonTitan enterprise SSD controllers. The ongoing commercial ramp of MonTitan, coupled with healthy customer order patterns across storage solutions, is expected to support the company's near-term performance.
SIMO's embedded storage business is another potential growth driver. The company continues to gain market share in eMMC and UFS controllers as NAND suppliers focus more resources on higher-priority memory products. However, rising NAND and DRAM prices remain a potential headwind. Higher component costs are making smartphones and PCs less affordable, particularly in lower-priced segments
Price Performance
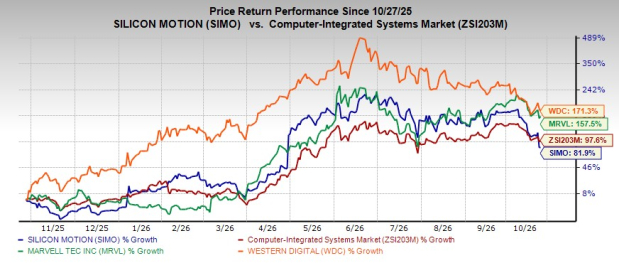
Over the past year, SIMO has surged 81.9% compared with the industry’s growth of 97.6%. It has underperformed peers like Marvell Technology, Inc. MRVL and Western Digital Corporation WDC over this period. While Marvell has gained 157.5%, WDC has jumped 171.3%.
Image Source: Zacks Investment Research
Key Valuation Metric
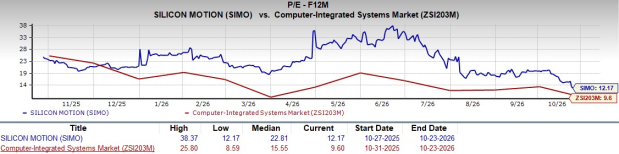
From a valuation standpoint, Silicon Motion appears to be trading at a premium relative to the industry and above its mean. Going by the price/earnings ratio, the company's shares currently trade at 12.17 forward earnings, higher than 9.6 for the industry but lower than the stock’s mean of 22.81.
Image Source: Zacks Investment Research
Investment Considerations
SIMO's expanding exposure to enterprise storage, automotive applications and AI infrastructure strengthens its long-term growth opportunity. The company's controller technology, established relationships with NAND manufacturers, and growing presence in higher-value storage solutions could help it capture demand as computing workloads become more storage-intensive. The increasing contribution of MonTitan and enterprise boot drive products also offers an opportunity to reduce dependence on consumer-oriented markets over time.
Profitability is another factor worth monitoring. Management expects the third quarter to benefit from a more favorable product mix, particularly the rising contribution of MonTitan and PCIe Gen5 controllers.
However, SIMO is exposed to volatility in the consumer market. Weak smartphone and PC demand, elevated memory prices, intense competition and uncertainty surrounding component availability could limit growth in established product categories.
End Note
Expanding enterprise storage operations, market-share gains in embedded controllers and increasing demand for automotive and AI-related storage solutions are major tailwinds as SIMO is set to release third-quarter results. Nevertheless, higher memory costs, weakness in consumer markets and the pace of enterprise product adoption remain key variables. SIMO’s diversification strategy boosts prospects for the long run, but in the near term, the company demonstrates a balanced outlook. Long-term investors should hold on to the stock, but new investors should wait for a better entry point.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Silicon Motion Technology Corporation (SIMO): Free Stock Analysis Report
Western Digital Corporation (WDC): Free Stock Analysis Report
Marvell Technology, Inc. (MRVL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).