

With a market cap of $65.4 billion, Apollo Global Management, Inc. (APO) is a global alternative investment manager specializing in credit, private equity, infrastructure, real estate, and hedge fund strategies across both private and public markets. The firm serves institutional and individual investors worldwide, deploying contrarian, value, and distressed investment approaches across a broad range of industries and regions.
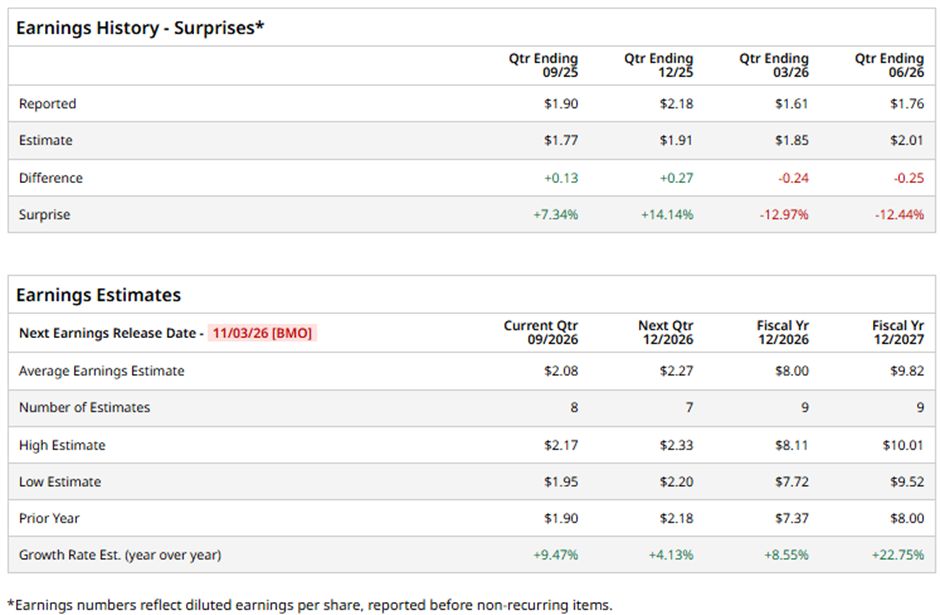
The New York-based company is expected to release its fiscal Q3 2026 results before the market opens on Tuesday, Nov. 3. Ahead of this event, analysts forecast APO to report an EPS of $2.08, up 9.5% from $1.90 in the prior year's quarter. It has surpassed Wall Street's bottom-line estimates in two of the past four quarters while missing on two other occasions.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts anticipate Apollo Global to post an EPS of $8, a 8.6% rise from $7.37 in fiscal 2025. Looking ahead, EPS is projected to increase 22.8% year-over-year to $9.82 in fiscal 2027.
 www.barchart.com
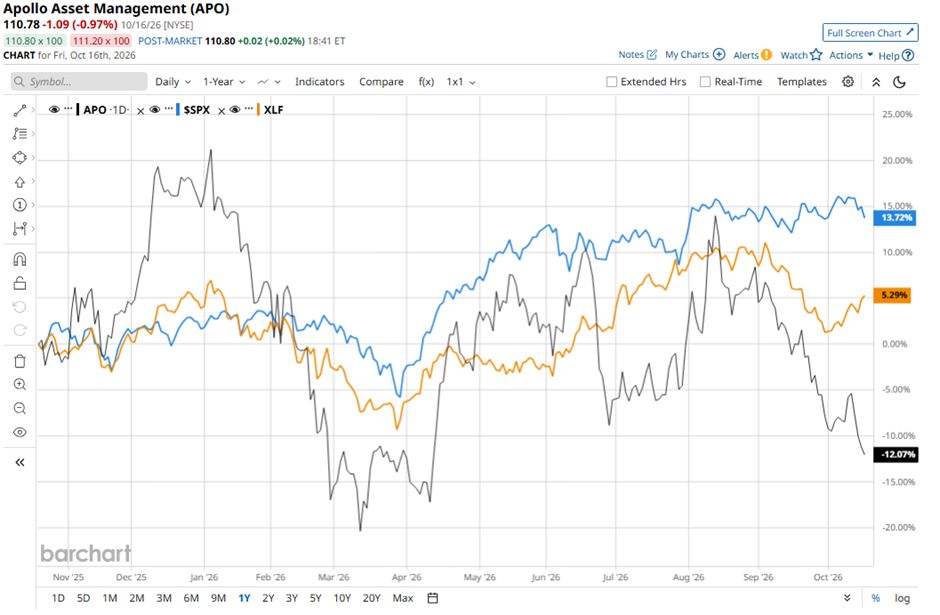
Shares of Apollo Global have decreased 8.3% over the past 52 weeks, underperforming both the S&P 500 Index's ($SPX) 15.5% gain and the State Street Financial Select Sector SPDR ETF's (XLF) 7.3% return over the period.
 www.barchart.com
Apollo Global Management shares rose 2.9% on Aug. 4 due to record earnings from its more stable lending and insurance businesses, despite Q2 2026 adjusted EPS of $2.11 falling short of analysts’ estimates. Fee-related earnings jumped 25% year-over-year to a quarterly record of $785 million and spread earnings rose 7% to a record $877 million, supported by strong deal-arranging activity and insurance investment income.
Sentiment was also supported by $38 billion in fresh capital raised by Apollo’s asset management arm and $12 billion secured for its latest flagship private equity fund through July, helping offset concerns that realized performance fees had dropped 41% to $130 million because the company prudently delayed asset sales amid challenging market conditions.
Analysts' consensus view on APO stock is cautiously optimistic, with a "Moderate Buy" rating overall. Among 23 analysts covering the stock, 14 recommend "Strong Buy," one suggests "Moderate Buy," and eight indicate “Hold.” The average analyst price target is $149.77, indicating a potential upside of 35.2% from the current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why 1 Analyst Is Cooling Their Stance on Red-Hot DELL Stock Intel vs. AMD: The CPU Comeback Has Become a 2-Stock Fight, But 1 Is the Better Buy Taiwan Semiconductor Could Partner With Elon Musk’s Terafab, but It Has 1 Condition Berkshire Hathaway Raised Its Stake in Bending Spoons to 4%. That’s a Big Vote of Confidence Retail Investors Should Follow.