

Integer Holdings Corporation ITGR has been gaining from its research and product development activities. The optimism, led by a mixed second-quarter 2026 performance and its strength in core product franchises, is expected to contribute further. However, new-product adoption concerns still persist.
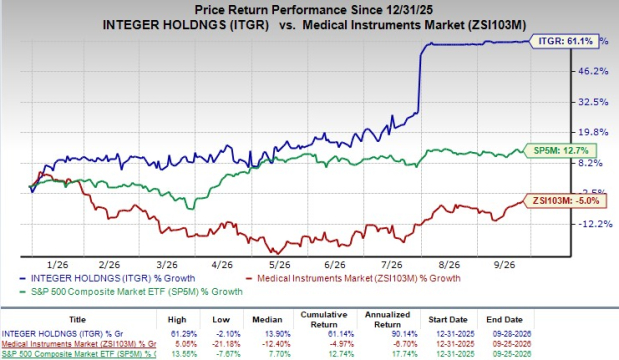
This Zacks Rank #3 (Hold) company’s shares have gained 61.1% in the year-to-date against the industry’s 5% decline and the S&P 500’s 12.7% rise.
The renowned medical device outsourcing manufacturer has a market capitalization of $4.3 billion. The company projects 8.6% growth for the next five years and expects to maintain its strong performance going forward. Integer Holdings’ earnings surpassed the Zacks Consensus Estimate in the last reported quarter, delivering a trailing four-quarter average surprise of 6.3%.
Image Source: Zacks Investment Research
Factors Favoring Integer Holdings’ Growth
Defined Acquisition Consideration Creates a Clear Transaction Catalyst: On Aug. 2, 2026, Integer Holdings entered into a definitive agreement to be acquired by affiliates of Kohlberg Kravis Roberts & Co. L.P. (“KKR”). Under the transaction, each eligible share would be converted into the right to receive $127 in cash at closing. The acquisition is not subject to a financing condition, and the buyer has obtained equity and debt financing commitments. Completion remains subject to customary conditions, including approval by holders of a majority of outstanding shares and required regulatory clearances.
The agreement also provides for a $307 million parent termination fee in certain circumstances involving a buyer breach or failure to complete the transaction when required. If completed, Integer Holdings would become a wholly owned subsidiary of the buyer and its shares would be delisted from the NYSE. The pending acquisition therefore provides a defined cash value for shareholders, although realization depends on successful closing.
Core Product Franchises Retain Underlying Demand: Integer Holdings’ second-quarter 2026 performance indicates that weakness remains concentrated in a few new product programs rather than broad-based across its portfolio. C&V sales fell 2% year over year to $280.3 million, primarily due to lower-than-expected adoption of two new electrophysiology products. However, first-half C&V sales declined only 1% to $542 million, with foreign exchange and acquisitions providing modest support. CRM&N remained more resilient, with sales rising 1% to $173.7 million in the quarter and 3% to $342 million in the first half, despite softness in one neuromodulation product.
The broader sales picture also reflects the impact of the planned exit from Portable Medical, which drove a 43% decline in Other Markets sales in the second quarter and a 45% decline in the first half. Integer Holdings’ 2026 outlook continues to point to lower-than-anticipated adoption of three new products as the key drag on growth, with these programs previously expected to reduce organic sales growth by roughly 3% to 4%. This suggests that the company’s established portfolio remains relatively supportive, although improving execution and market adoption of the newer offerings will be important to offset the near-term pressure.
Mixed Q2 Results: Integer Holdings exited the second quarter of 2026 with a mixed performance. Revenues declined year over year, reflecting continued pressure from previously communicated product-related headwinds and the strategic exit from Portable Medical. However, adjusted earnings per share (EPS) increased 3.2%, supported by a relatively stable adjusted net income despite the softer top line.
On the product-line front, performance remained uneven. Cardio & Vascular sales declined as two new Electrophysiology products continued to weigh on results, while Cardiac Rhythm Management & Neuromodulation posted modest growth despite the impact from one new Neuromodulation product.
Factor That May Offset ITGR’s Gains
New-product adoption and EP forecast resets: Integer Holdings continues to face lower-than-anticipated market adoption for three recently launched products, including two in electrophysiology and one in neuromodulation. Second-quarter 2026 sales declined 2.6% year over year to $464.1 million. C&V sales were down 2% in the quarter, and the latest earnings release again identified the three products as a primary factor affecting 2026 sales. Lower production volumes also reduced fixed-cost absorption, contributing to a gross-margin decline to 24.3% from 27.1% a year earlier. The persistence of the issue raises execution risk until adoption improves.
Estimate Trend
Integer Holdings is witnessing a stable estimate revision trend for 2026. In the past 30 days, the Zacks Consensus Estimate for earnings has remained stable at $6.09 per share.
The Zacks Consensus Estimate for the company’s third-quarter 2026 revenues is pegged at $457.3 million, indicating a 2.2% decline from the year-ago quarter’s reported number. The consensus mark for third-quarter earnings is pegged at $1.65 per share, implying a 7.8% decline from the year-earlier level.
Stocks to Consider
Some better-ranked stocks from the broader medical space are Globus Medical GMED, Veracyte VCYT and West Pharmaceutical WST.
Globus Medical, currently carrying a Zacks Rank #1 (Strong Buy), reported a second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%. You can see the complete list of today’s Zacks #1 Rank stocks here.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
Veracyte, currently flaunting a Zacks Rank #1, reported a second-quarter 2026 adjusted EPS of 54 cents, which surpassed the Zacks Consensus Estimate by 25.6%. Revenues of $150.3 million beat the Zacks Consensus Estimate by 4.1%.
VCYT has an estimated earnings growth rate of 8.4% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 41.8%.
West Pharmaceutical, carrying a Zacks Rank #2 (Buy) at present, reported second-quarter 2026 adjusted EPS of $2.37, which beat the Zacks Consensus Estimate by 13.9%. Revenues of $872.3 million surpassed the Zacks Consensus Estimate by 4.2%.
WST has an estimated long-term earnings growth rate of 16%. WST’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 17.4%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Integer Holdings Corporation (ITGR): Free Stock Analysis Report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Veracyte, Inc. (VCYT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).