

Salesforce (CRM) investors have an important date to watch as the company prepares to host its Investor & Analyst Session on Wednesday, Sept. 16, during Dreamforce 2026. The event comes at a critical time for Salesforce as investors look for greater clarity on how the company plans to turn rapid artificial intelligence (AI) adoption into sustainable revenue growth. Salesforce recently delivered a strong second-quarter fiscal 2027 report, with current remaining performance obligations rising 14% and management raising its full-year revenue guidance.
Against this backdrop, the Investor Day session could provide additional insight into Salesforce’s long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
With CRM stock having rebounded sharply in recent weeks, investors will be closely watching whether management can provide enough positive updates to support the company’s broader investment narrative.
About Salesforce Stock
Salesforce is a leading global provider of cloud-based customer relationship management (CRM) software, headquartered in the iconic Salesforce Tower in San Francisco, California.
Salesforce’s market cap stands at $210.4 billion, reflecting its status as one of the most valuable enterprise software companies globally. With its comprehensive platform, innovative technology, and scalable business model, Salesforce remains at the forefront of enterprise digital transformation.
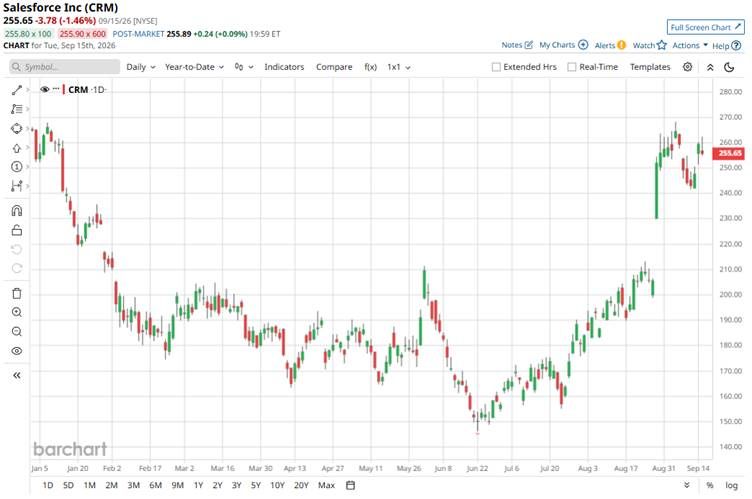
CRM has staged a sharp rebound in recent weeks, although the stock’s broader 2026 performance remains relatively muted. CRM closed the last session at $255.65, up 30.3% over the past month. On the other hand, the stock dropped 3.5% year-to-date (YTD), while it is up just 5.4% over the past year, highlighting how much of the recent rally has been a recovery from weakness earlier in the year.
The latest momentum has been particularly notable following Salesforce’s second-quarter fiscal 2027 results and growing investor enthusiasm around its AI strategy. Shares have also benefited from expectations surrounding Dreamforce, taking place in San Francisco from Sept. 15–17, bringing together customers, partners, and technology leaders as the company showcases its latest developments across artificial intelligence, Agentforce, and Data 360.
The company is also using Dreamforce to highlight its broader vision of an “Agentic Enterprise,” making the event an important backdrop for investors assessing Salesforce’s AI monetization strategy and future growth opportunities.
CRM currently trades at a discount compared to the sector median and its own historical average at 19.31 times forward earnings.
 www.barchart.com
Steady Q2 Results
Salesforce released its second-quarter fiscal 2027 results on Aug. 26, for the quarter ended July 31, delivering stronger profitability and continued momentum in its AI and data businesses.
Revenue increased 11% year-over-year (YoY) to $11.3 billion, while subscription and support revenue, Salesforce’s core revenue stream, rose 12% to $10.8 billion. The company’s cRPO increased 14% YoY to $33.5 billion, compared with $29.4 billion a year earlier, while total RPO rose 11% to $66.3 billion.
Profitability also improved substantially. Non-GAAP net income increased to $4.8 billion, and adjusted EPS rose 103% to $5.90. Salesforce reported a non-GAAP operating margin of 34.1%, compared with 34.3%. Cash generation was notably stronger, with operating cash flow rising 71% to $1.3 billion and free cash flow increasing 81% to $1.1 billion.
AI remained a major focus of the quarter. Agentforce and Data 360 ARR reached nearly $3.9 billion, up more than 210% YoY, while Agentforce ARR exceeded $1.5 billion, representing growth of more than 240%. Salesforce also reported 3.2 billion Agentic Work Units delivered during the quarter and said Data 360 processed 104 trillion records, up 355% YoY. These metrics provide additional context for investors assessing whether Salesforce’s AI investments are translating into measurable commercial adoption.
For the outlook, Salesforce raised its fiscal 2027 revenue guidance to $46.1 billion-$46.4 billion. The new forecast implies 11%-12% YoY growth.
Subscription and support revenue growth guidance was raised to slightly above 12%, while full-year non-GAAP operating margin guidance was maintained at 34.3%. Salesforce maintained its operating cash flow and free cash flow growth outlook at approximately 4%-5% YoY.
For the third quarter of fiscal 2027, Salesforce guided for revenue of $11.42 billion-$11.50 billion, representing 11%-12% YoY growth. The company expects non-GAAP EPS of $3.42-$3.44, while cRPO growth is expected to be approximately 14% YoY.
Analysts predict EPS to rise 32.3% YoY to $12.83 in fiscal 2027 but slide by 12.3% annually to $11.25 in fiscal 2028.
What Do Analysts Expect for CRM Stock?
Needham analyst Scott Berg reiterated a “Buy” rating on Salesforce on Sept. 2, while maintaining his $400 price target.
Furthermore, Cantor Fitzgerald maintained an “Overweight” rating on Salesforce while raising its price target to $300 from $250. The firm’s update followed a Product Adoption & Momentum Webinar that provided additional insight into Salesforce’s AI momentum, headless platform strategy, Slackbot, Claudeforce, and evolving pricing and packaging.
On the other hand, UBS maintained a “Neutral” rating on Salesforce while raising its price target to $240 from $210 last month.
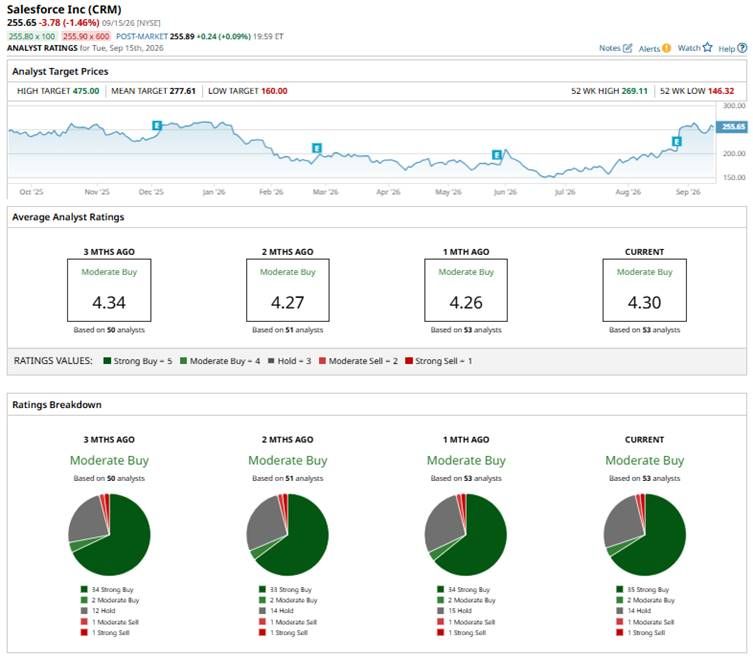
Wall Street is cautiously bullish on CRM. Overall, CRM has a consensus “Moderate Buy” rating. Of the 53 analysts covering the stock, 35 advise a “Strong Buy,” two suggest a “Moderate Buy,” 14 analysts are on the sidelines, giving it a “Hold” rating, one recommends it a “Moderate Sell,” and one rates it as a “Strong Sell.”
The average analyst price target for CRM is $277.61, indicating a potential upside of 8.6%. The Street-high target price of $475 suggests that the stock could rally as much as 85.8%.
 www.barchart.com
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.