

Meta Platforms (META) unveiled its Meta One subscription to monetize its massive artificial intelligence (AI) spending. This opens new revenue streams, as Meta has devised plans starting at $2.99 per month and rising to $14.99 for creator and business bundles. As the first sign of monetizing its massive AI-based capex, this shift signals a transition to a multi-product, multi-revenue platform where AI services and subscriptions complement its core ad business.
Last week, the company also launched its personal AI agent, Muse, to help users with day-to-day tasks. This suggests Meta is trying to gain ground on Google (GOOG) (GOOGL) and OpenAI. Its wearables business has also come under scrutiny, as the latest smart glasses have been criticized for their recording capabilities. Reports suggest Meta will launch a camera-free pair of smart glasses, internally code-named Luna, this fall.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
At the significant juncture of AI monetization, Meta might be a stock worth watching now.
About Meta Platforms Stock
Meta Platforms, headquartered in Menlo Park, California, operates a global family of social apps, Facebook, Instagram, Messenger, and WhatsApp, alongside Reality Labs hardware and software. The business is transforming from a metaverse-centric strategy to an AI-first ecosystem, scaling data center infrastructure, launching AI-powered wearables, and developing personal and business agents while trimming Reality Labs investments. It has a market capitalization of $1.71 trillion.
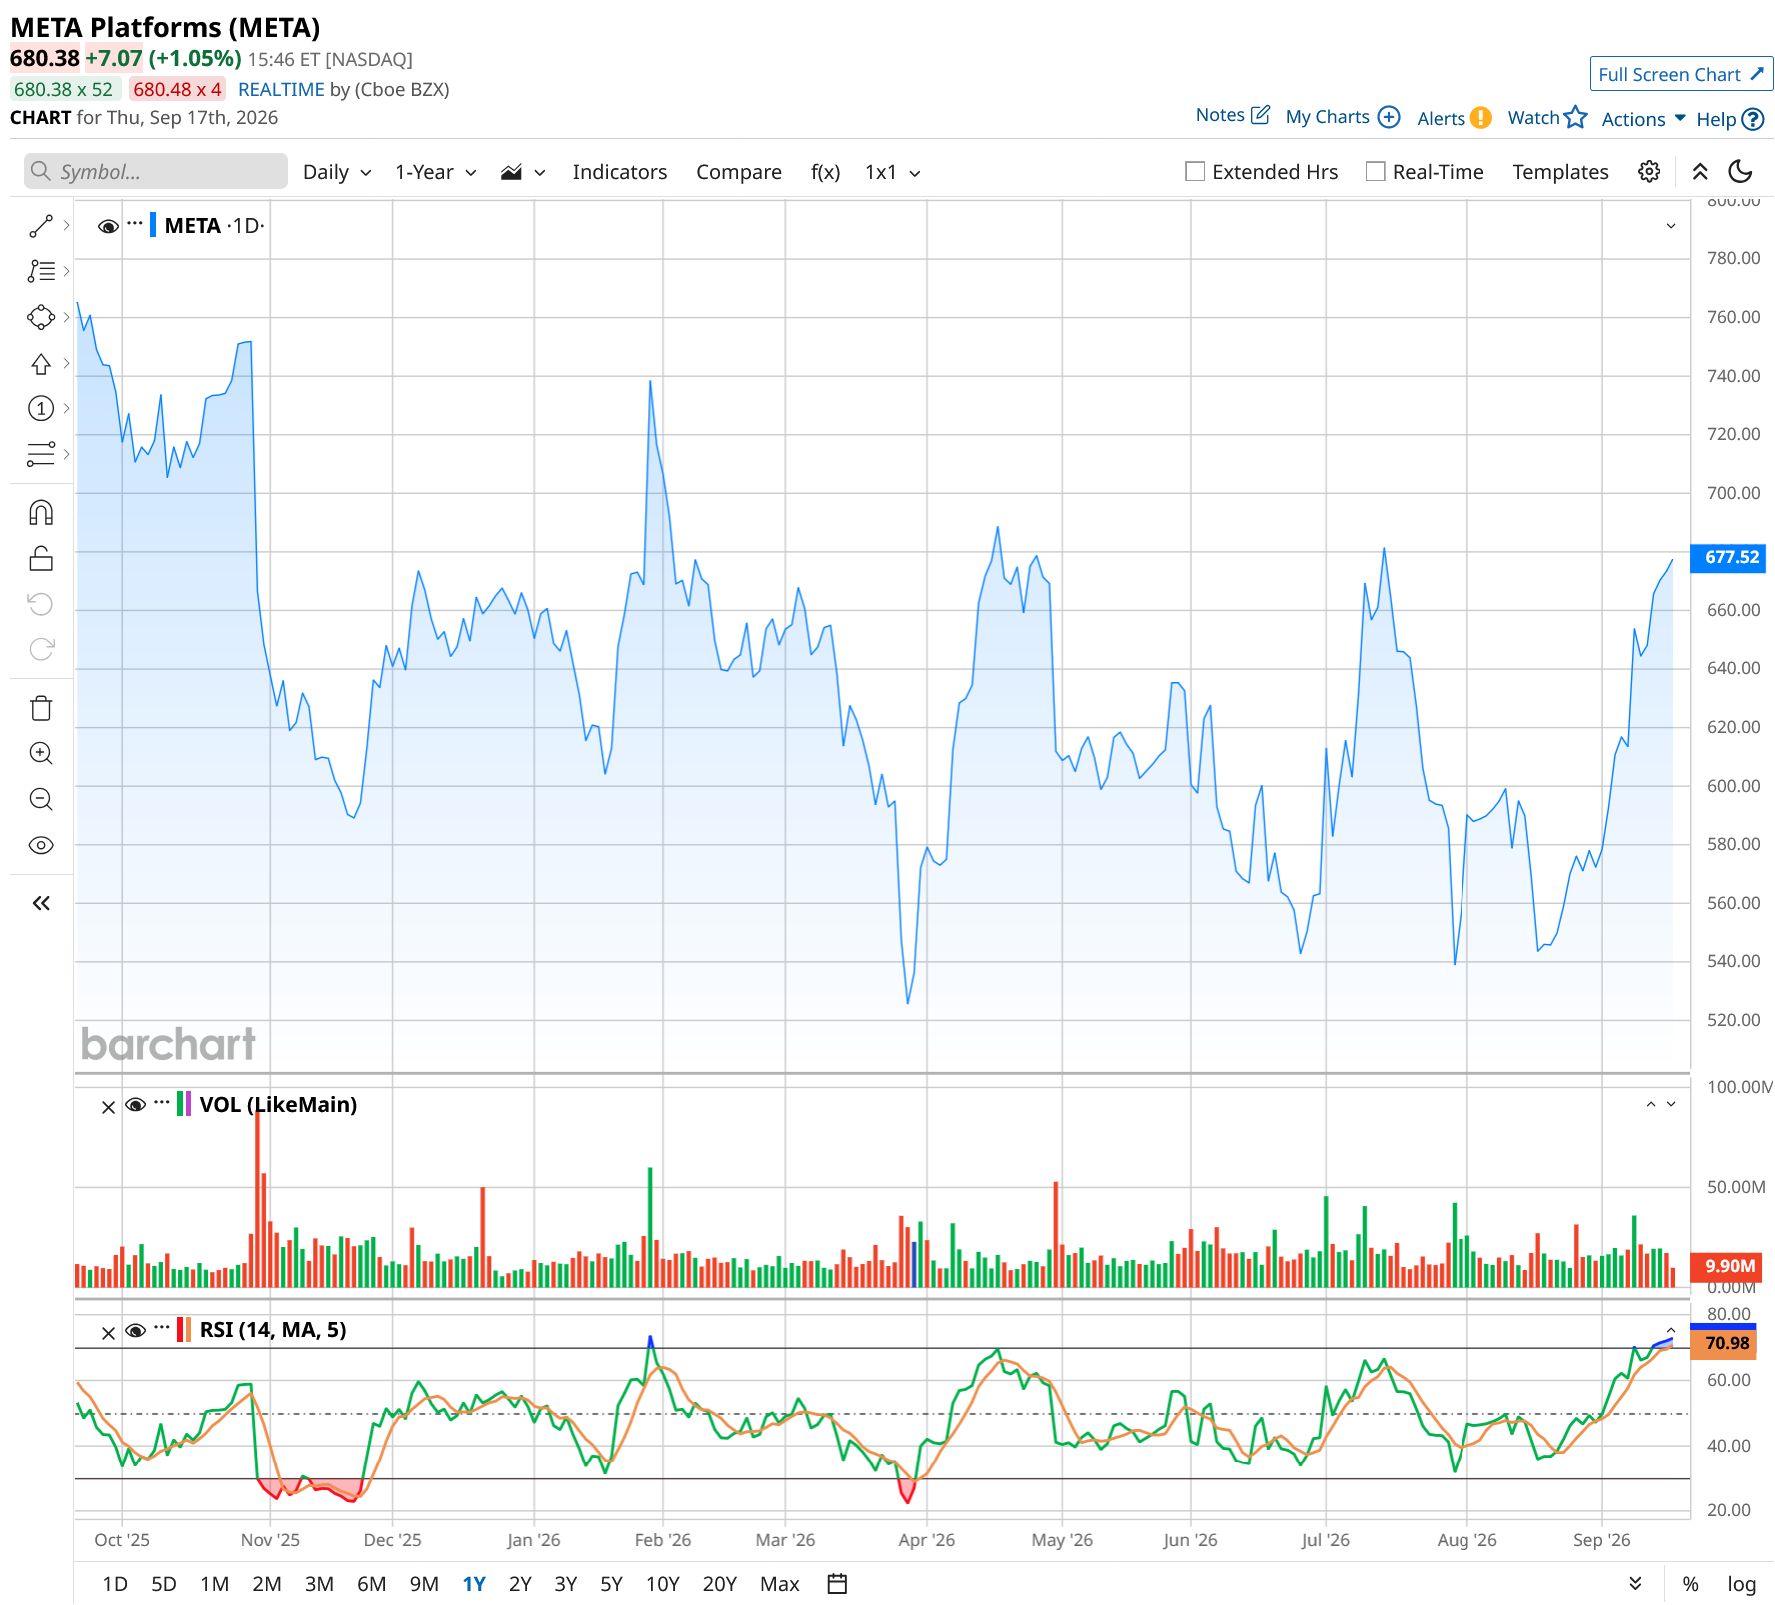
Meta has been down over the past year as investors have become more cautious about heavy AI spending. Over the past 52 weeks, META stock has dropped 13%, but it is up 2.5% year-to-date (YTD). The company’s shares reached a 52-week low of $520.26 on March 27 but are up 30% from that level.
 www.barchart.com
Meta’s 14-day relative strength index (RSI) of 72.60 is now in the overbought territory. The selloff has also brought down its valuation. On a forward-adjusted basis, the stock’s non-GAAP PEG ratio of 1.07x is lower than the industry average of 1.33x.
Q2 Revenue Jumps, Profit Misses on Heavy AI Spend
For the second quarter of fiscal 2026, Meta’s revenue increased by 28% year-over-year (YoY) to $60.80 billion. The Family of Apps segment led growth, rising 28% to $60.37 billion. Family Daily Active People (DAP) averaged 3.6 billion in June 2026, up 3% YoY, while ad impressions across its Family of Apps rose 14% YoY.
However, Meta’s profitability has come under pressure as costs and expenses rose 55% from the prior-year period to $42.03 billion. Capital expenditures, including principal payments on finance leases, were $31.08 billion for the quarter as it pursues aggressive AI spending. Meta’s quarterly EPS declined by 13% YoY to $6.18.
Wall Street analysts have mixed feelings about Meta’s future earnings. For the current fiscal year, EPS is projected to decrease 5.1% to $28.17, followed by 21.4% growth to $34.19 in the next fiscal year. Moreover, analysts expect the company’s EPS to decline 12.7% YOY to $6.33 for the current quarter.
Here’s What Analysts Think About META Stock
A few days ago, Wedbush analyst Ygal Arounian maintained META stock's price target at $650 and a “Hold” rating. JPMorgan analysts made the biggest pivot, upgrading Meta Platforms from “Neutral” to “Overweight” and raising the price target from $640 to $820. The bank's analysts noted the company is just beginning to roll out frontier AI models and new products outside advertising, such as the Muse AI agent and access to its Meta Model API.
JPMorgan forecasts 2027 capital spending of $243 billion, up 70%, and 2028 capex of $284 billion, up 17%. However, the bank expects free cash flow to turn negative by $65 billion to $70 billion in each of those years.
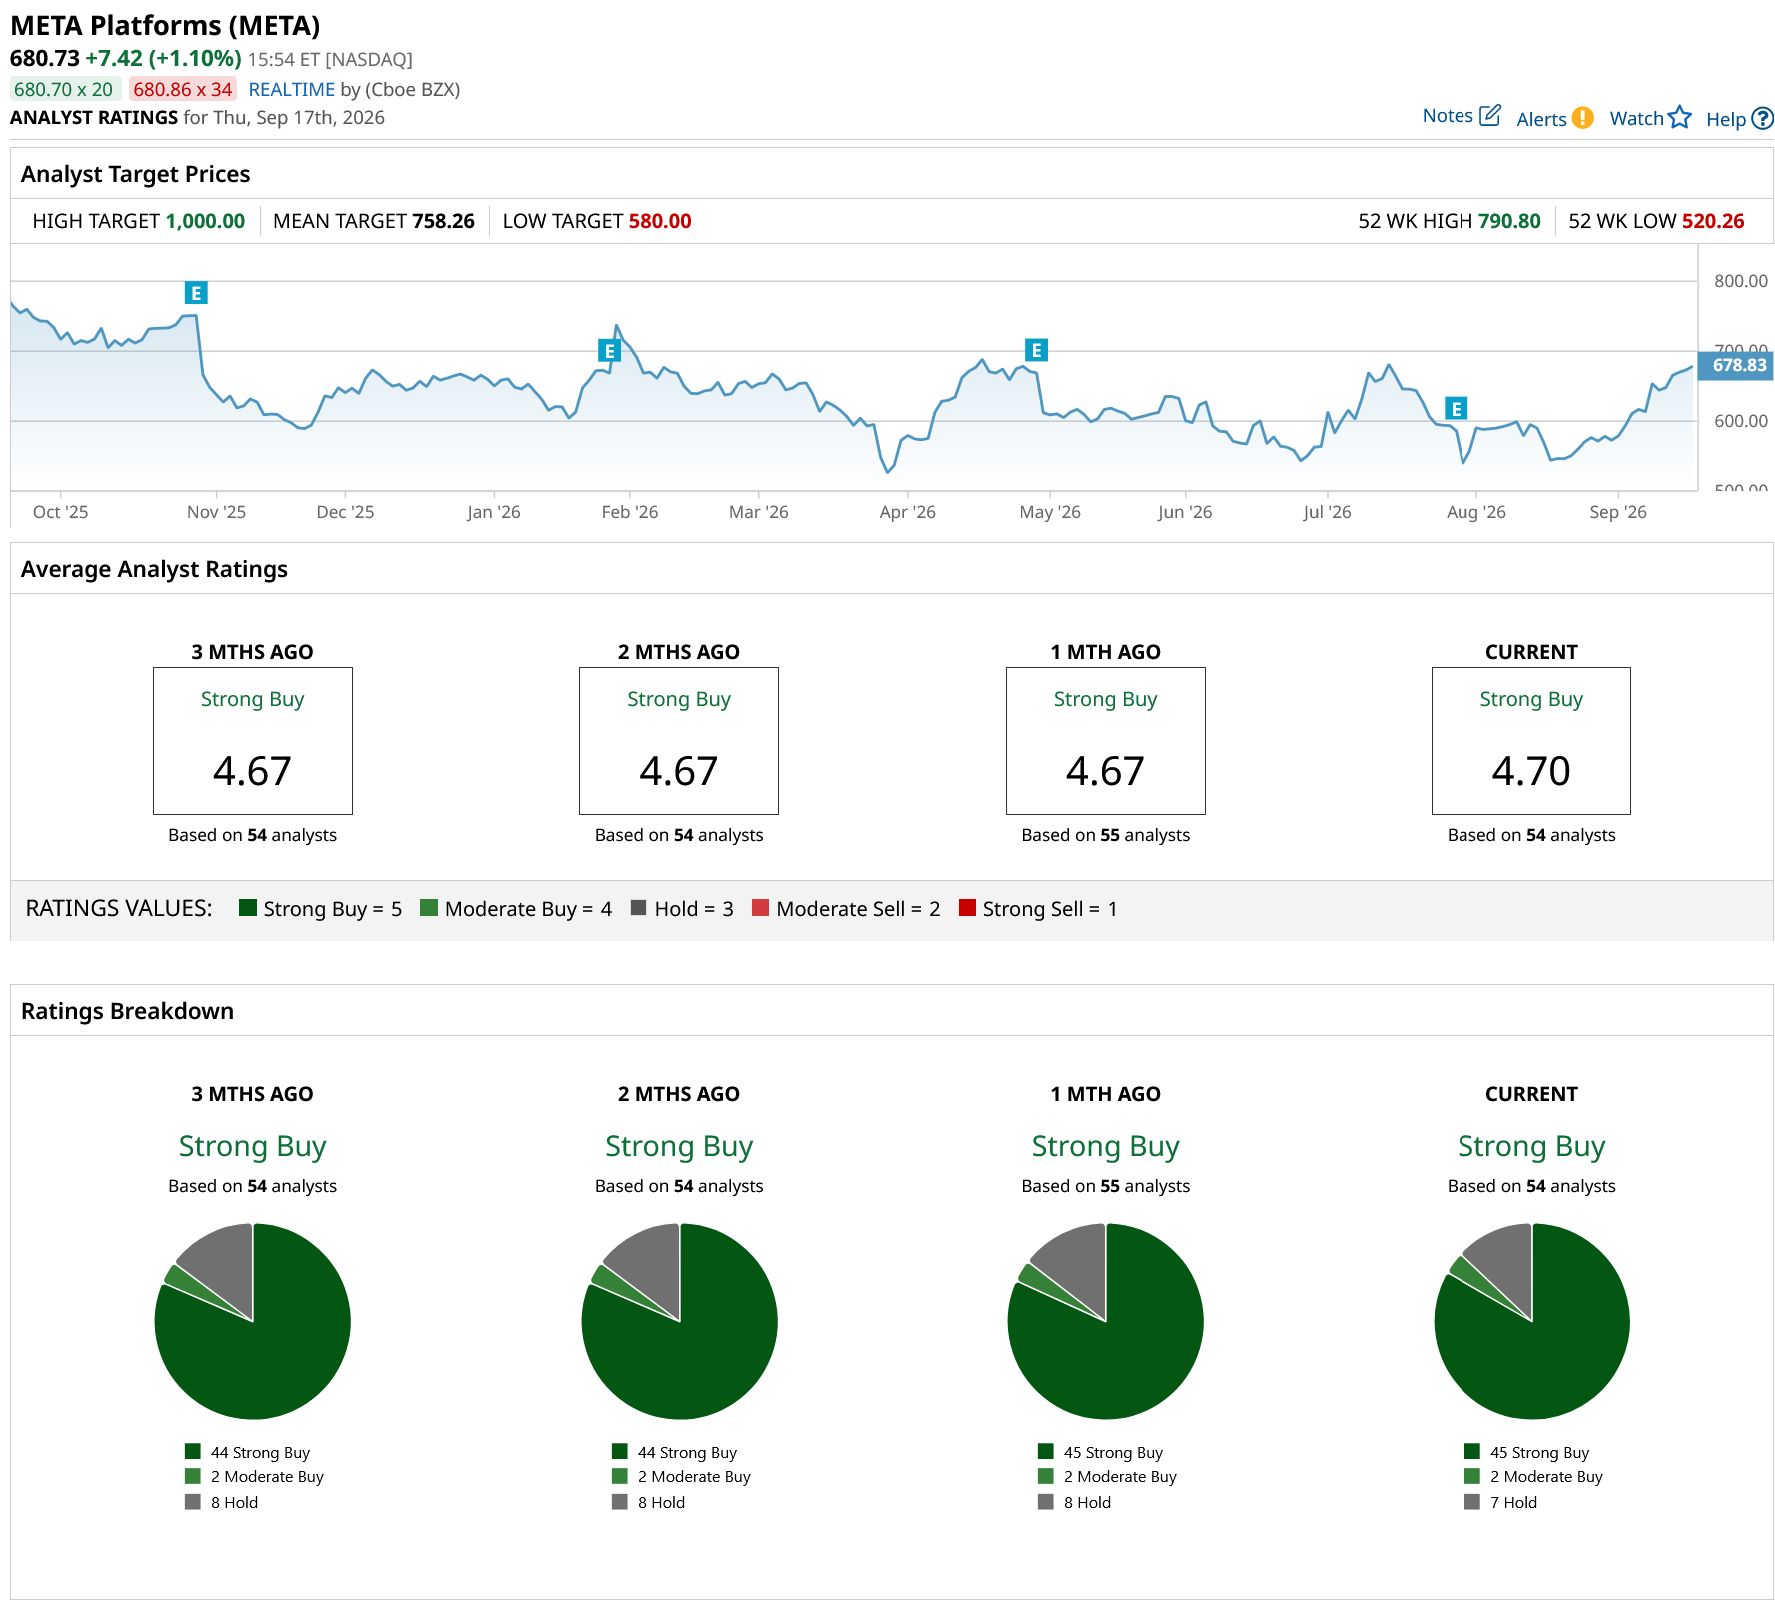
META stock has been in the spotlight on Wall Street, with analysts awarding it a consensus “Strong Buy” rating. Of the 54 analysts rating the stock, a majority of 45 analysts have rated it a “Strong Buy,” two analysts suggest a “Moderate Buy,” while seven analysts are playing it safe with a “Hold” rating. The consensus price target of $758.26 represents an 11% upside from current levels. The Street-high price target of $1,000 indicates a 47% upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Meta Launches New Meta One Subscription, Here’s How You Should Play META Stock Bank of America Stock Just Suffered Its Worst Drop Since April 2025. Here’s Why. LCID Stock Surges as Lucid Unveils New European Robotaxi Partnership A $2.4 Billion Reason Why Generac Stock Is Up Today