

Tech giants are increasingly pushing into the wearables segment, and popular social media company Snap (SNAP) has pitched in with its Specs product. The company revealed the AR glasses in June, pitching them as catering to consumers rather than developers. Evan Spiegel, Snap’s CEO, said the company’s Specs AR glasses are better suited for tasks such as helping field technicians troubleshoot equipment issues by overlaying digital instructions and enabling interaction with workers.
Now, Snap has partnered with Nvidia (NVDA), Amazon (AMZN) Web Services, and Salesforce (CRM) to enter the enterprise market as competition in the wearables category grows. Aiming at this new market space, Snap expects Nvidia and Salesforce to make it easier for businesses to benefit from those agentic platforms. Snap is also planning to launch Specs Intelligence, a consumer-focused AI service that acts as a digital assistant capable of performing tasks across its AR glasses as well as iPhones and Mac computers.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
This new product, along with the company’s cost adjustments well underway, SNAP stock may be worth watching.
About Snap Stock
Snap Inc. is a technology company best known for Snapchat, a visual messaging and social networking app built around camera-first communication. The platform lets users share photos, videos, and augmented-reality Lenses through private Snaps, Stories, Spotlight short-form video, and Snap Map.
Snap generates most of its revenue from digital advertising displayed across these features, with a growing share from its Snapchat+ subscription service. The company also develops AR tools like Lens Studio and has explored hardware with Spectacles AR glasses. Snap is headquartered in Santa Monica, California, and has a market capitalization of $9.56 billion.
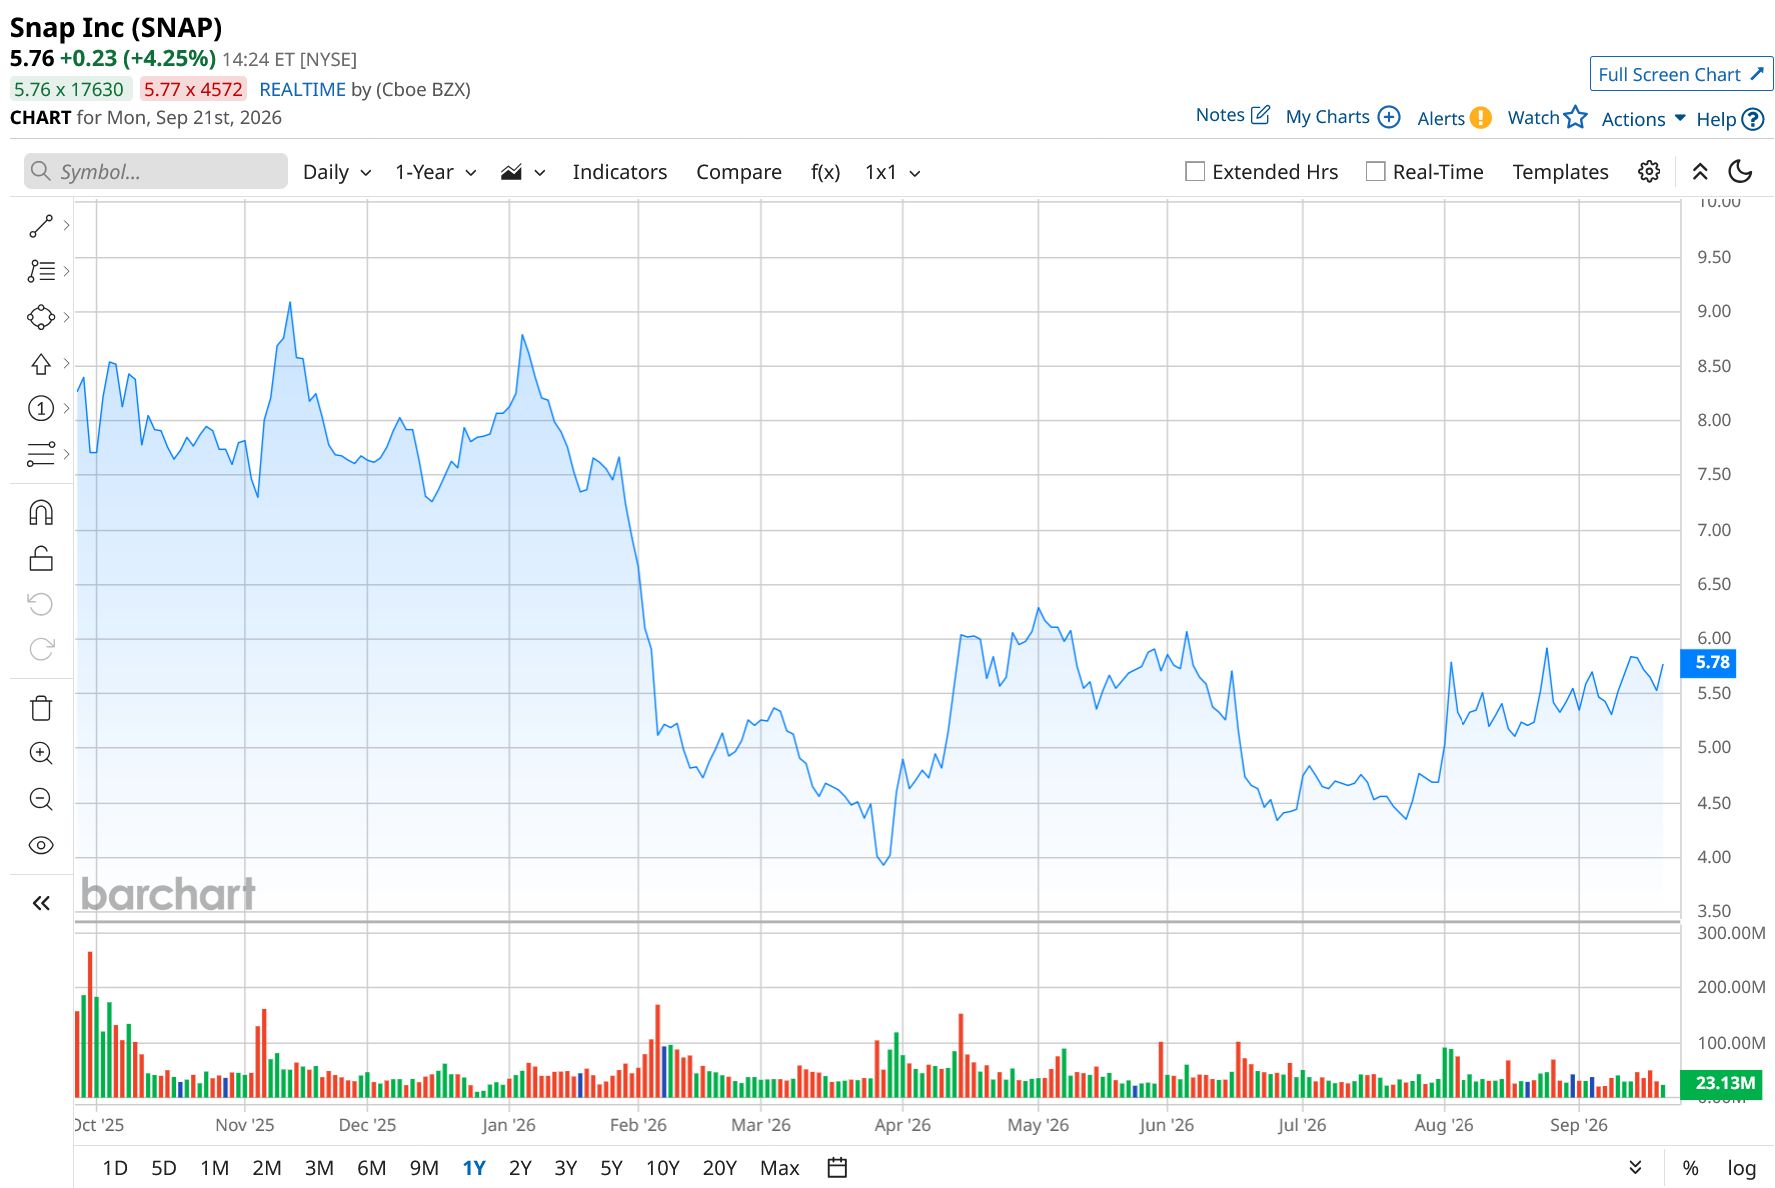
Investors have been concerned about Snap’s user growth and its GAAP-based unprofitability despite revenue growth. Over the past 52 weeks, SNAP stock has declined 29% and is down 28% year-to-date (YTD). It reached a 52-week low of $3.81 on March 27 but is up 51% from that level.
Snap’s selloff has lowered its valuation compared to its peers. Its forward-adjusted price-to-earnings (non-GAAP) ratio of 9.21x is lower than the industry average of 13.10x.
 www.barchart.com
Snap Reported Double-Digit Revenue Growth and Sharp EBITDA Gain in Q2
Snap reported solid second-quarter results. The platform’s monthly active users grew to 971 million, and daily active users reached 493 million. Broad-based growth in North America, particularly with large advertisers; broader adoption of its AI-powered Smart Campaign Solutions; continued SMB momentum; and growth in Snapchat+, Memories Storage, and our Lens+ subscription. This drove 19% year-over-year (YoY) revenue growth to $1.6 billion.
Cost-structure adjustments have also helped Snap regain some ground. Its operating loss declined by 34% YoY. Moreover, adjusted EBITDA rose sharply by 505% to $249.62 million. Snap has generated positive free cash flow for eight consecutive quarters while limiting fully diluted share count growth to approximately 2% over the past five years through its share repurchase program. Its quarterly free cash flow increased by 407% YoY to $120.54 million.
For the current year, Wall Street analysts expect Snap to report a $0.02 loss per share, a 92.6% YoY improvement, followed by 550% growth to an EPS of $0.09 next year.
Here’s What Analysts Think About SNAP Stock
Wall Street analysts have recently taken a more cautious view of SNAP stock. Recently, analysts at RBC Capital maintained a “Sector Perform” rating and an $8 price target. This stance reflects the challenges the company faces in a competitive landscape dominated by larger social media platforms.
Post its second-quarter earnings, Citigroup analysts maintained a “Neutral” rating on Snap but raised the price target from $6.50 to $6.75. This reflects cautious optimism about its potential growth, despite profitability challenges. UBS analyst Stephen Ju maintained a “Neutral” rating and raised the price target from $5 to $5.70.
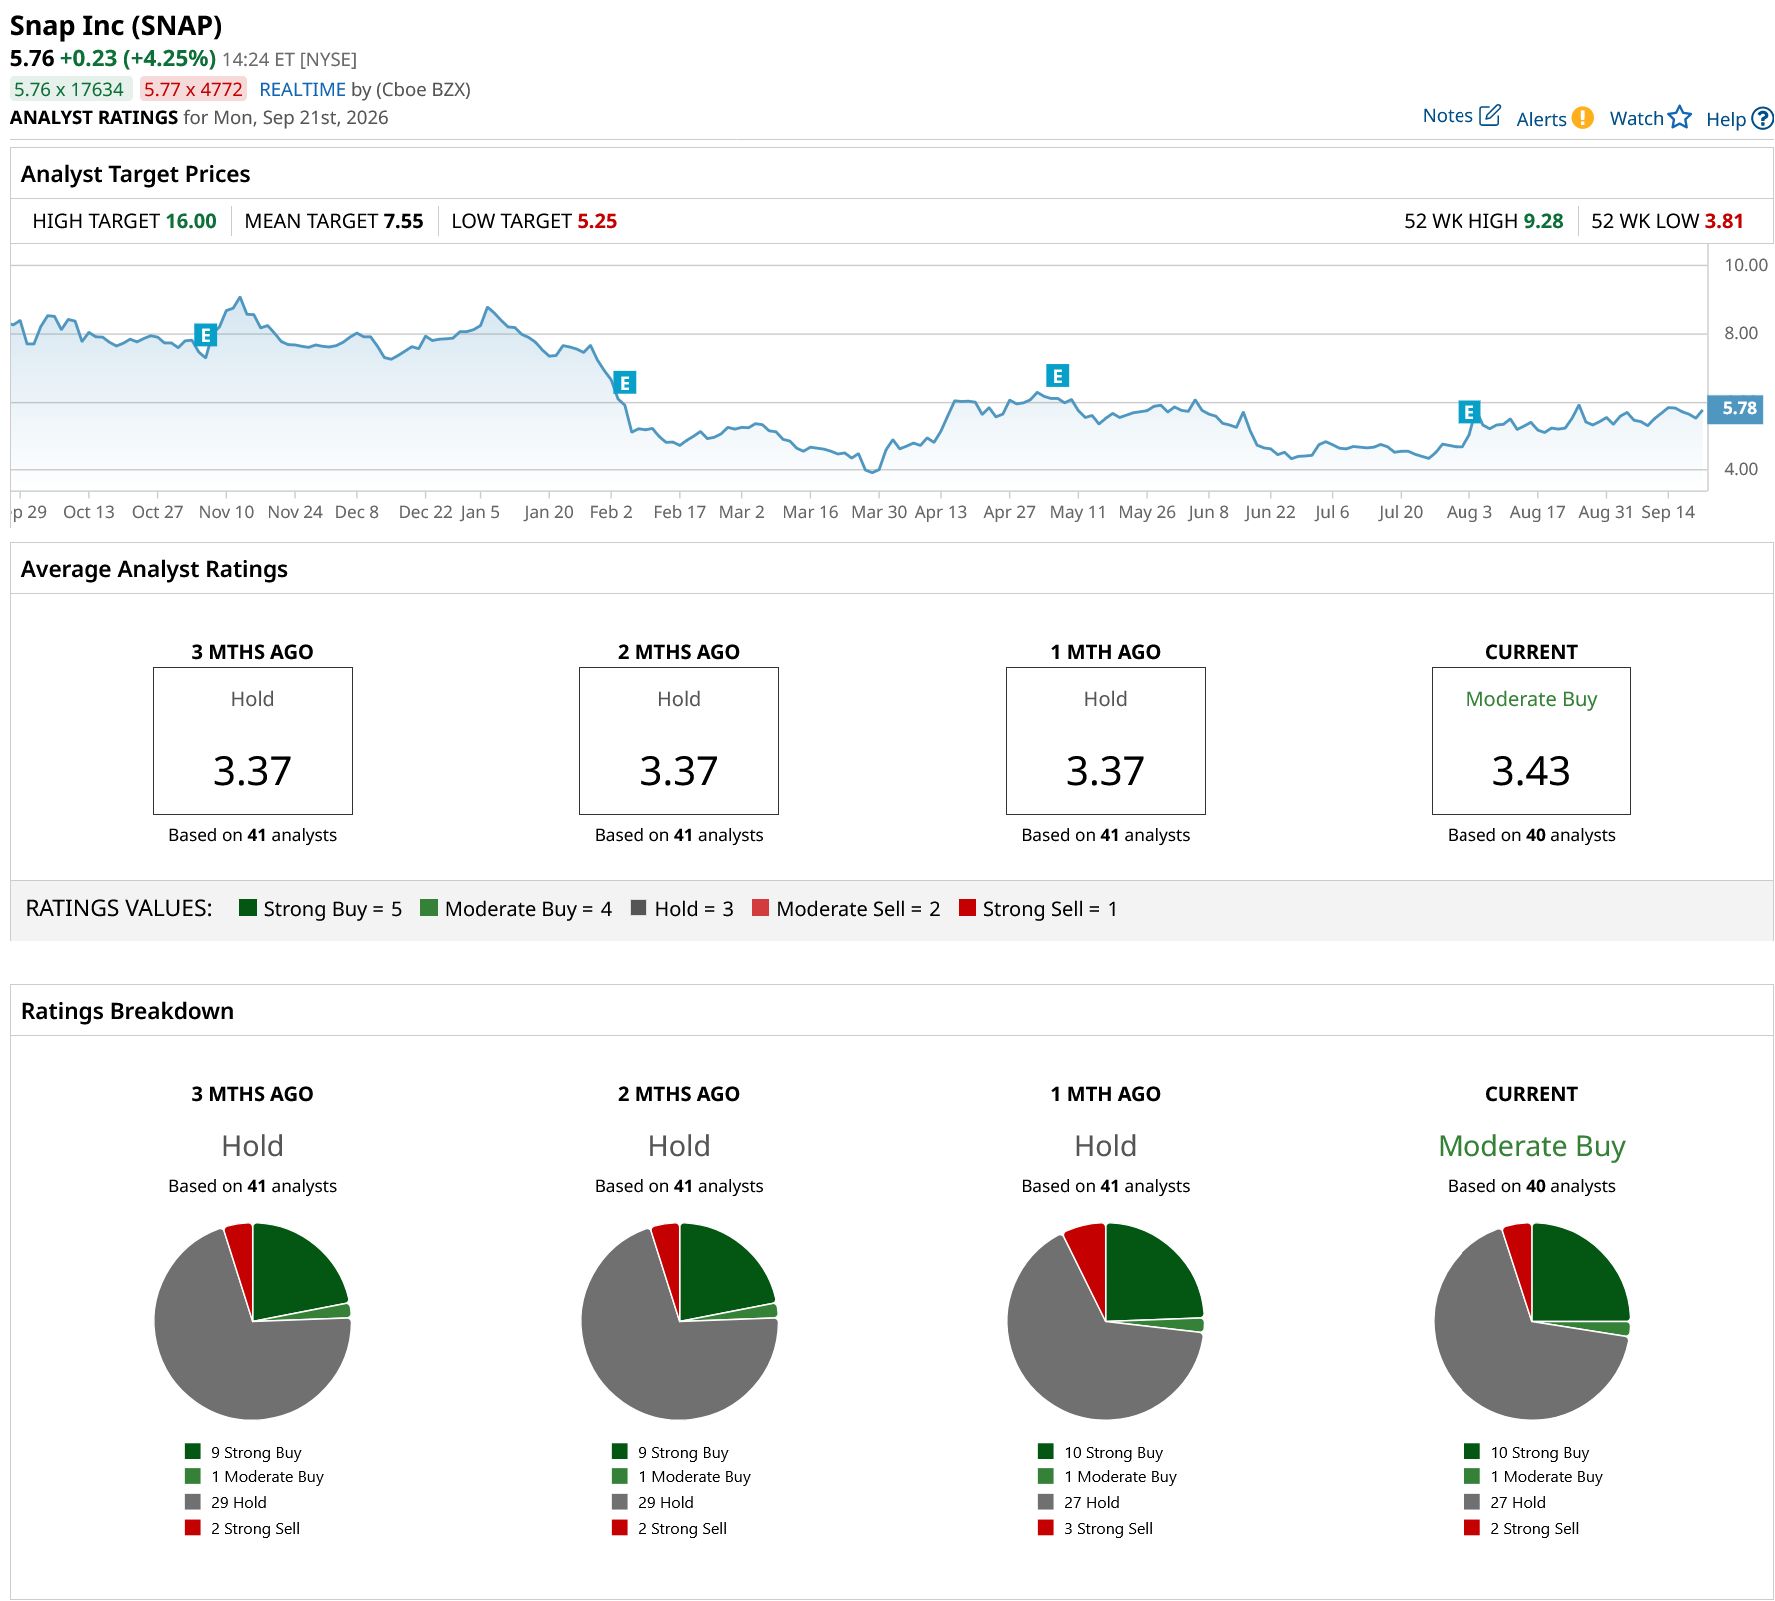
SNAP stock finds favor on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating. Of the 40 analysts rating SNAP, 10 analysts have given it a “Strong Buy” rating, and one analyst has given a “Moderate Buy” rating, while 27 analysts are taking the middle-of-the-road approach with a “Hold” rating, and two analysts suggest a “Strong Sell.” The consensus price target of $7.55 represents a 31% upside from current levels. Moreover, the Street-high price target of $16 reflects a 178% upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Substantially Higher Than a Car’: XPeng’s CEO on What Each Robot Could Earn. First It Has to Survive a Brutal Price War. Needham Just Upped Its Price Target on OKTA Stock. Here's Why. Why It’s Time to Load Up on Meta Stock As Snap Partners With Nvidia on Its Specs, Here’s How You Should Play SNAP Stock