

With a market cap of $13.8 billion, Mid-America Apartment Communities, Inc. (MAA) is a real estate company focused on delivering long-term investment performance through the ownership, management, acquisition, development, and redevelopment of quality apartment communities. The company primarily operates across the Southeast, Southwest, and Mid-Atlantic regions of the United States.
Companies worth more than $10 billion are generally labeled as “large-cap” stocks and MAA fits this criterion perfectly. As of June 30, 2026, MAA had ownership interests in 104,698 apartment units across 16 states and the District of Columbia, including communities under development.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
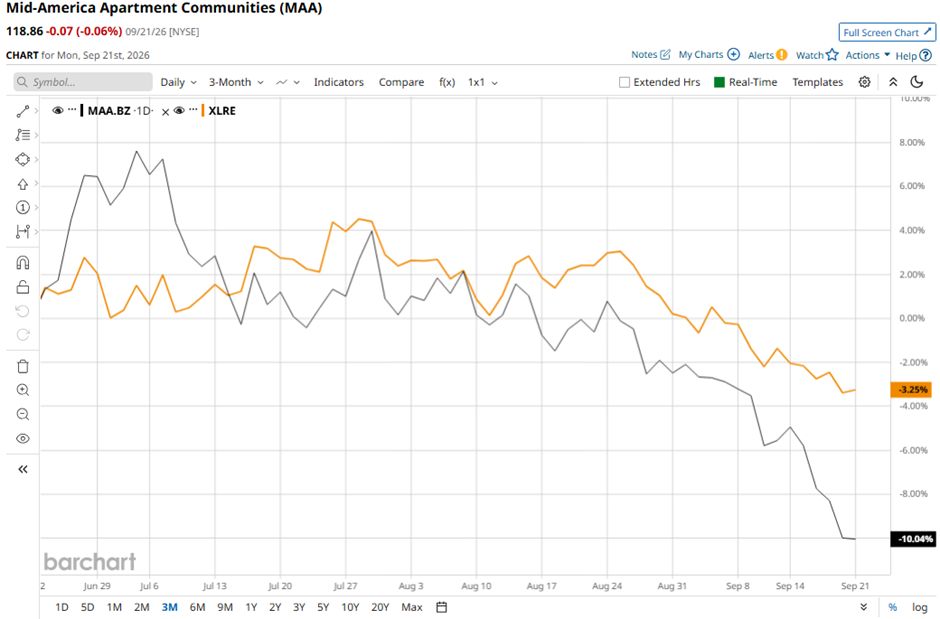
Shares of the Germantown, Tennessee-based company have dipped 17.7% from its 52-week high of $144.41. MAA stock has decreased 10.3% over the past three months, a more pronounced decline than the State Street Real Estate Select Sector SPDR ETF’s (XLRE) 3.1% drop during the same period.
 www.barchart.com
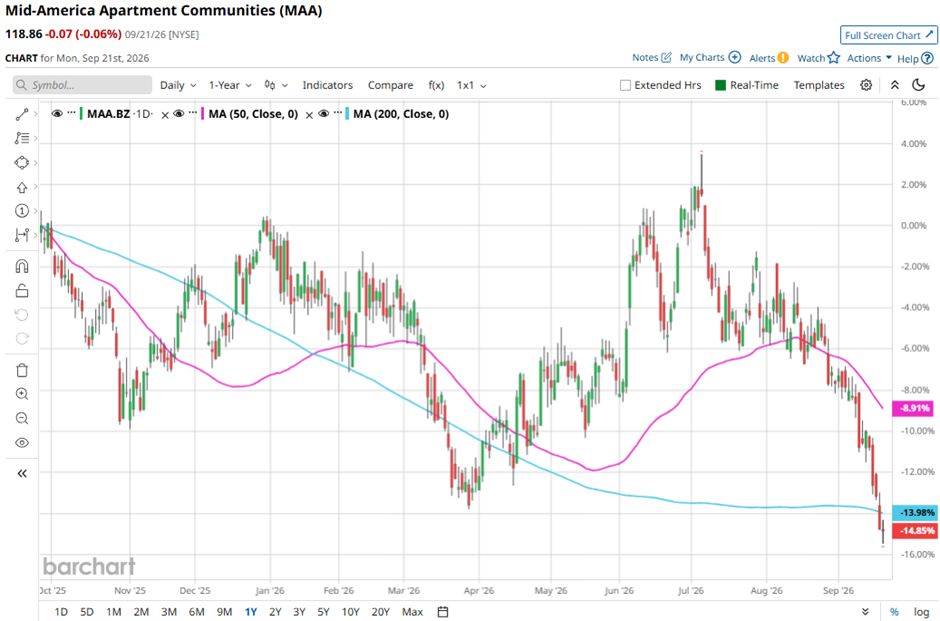
The stock has fallen 14.4% on a YTD basis, lagging behind XLRE's 5.7% gain. Moreover, shares of the REIT have declined 15.6% over the past 52 weeks, compared to XLRE's 2.4% return over the same time frame.
MAA stock has been trading below its 50-day moving average since late August.
 www.barchart.com
MAA shares fell nearly 3% following its Q2 2026 results on Jul. 29. The company lowered its 2026 EPS guidance to $3.96 - $4.20 and cut its Same Store NOI growth outlook to negative 1.70% to 0.10% from negative 1.70% to 0.30%. Q2 Core FFO per share declined to $2.08 and Same Store NOI fell 1% as property revenue declined and expenses rose.
Despite improving lease pricing, with blended lease-rate growth accelerating to 0.7% and new lease pricing improving 170 basis points sequentially, effective new lease rates remained down 5.3%, highlighting continued pressure on rent growth.
In comparison, rival Essex Property Trust, Inc. (ESS) has outperformed MAA stock. ESS stock has gained 3.7% on a YTD basis and 1.4% over the past 52 weeks.
Despite the stock’s underperformance relative to the sector, analysts are moderately optimistic, with a consensus rating of "Moderate Buy" from 27 analysts. The mean price target of $141.23 suggests a premium of 18.8% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Okta Stock Fans, Mark Your Calendars for September 22 US Legislators Are Debating a Diesel Export Ban Ahead of Midterms — Here's Why Carnival Corp Stock Looks Cheap to Value Investors Ahead of Earnings Next Week Why Cathie Wood Says SpaceX Stock Could Be a Deep-Value Buy