

When investors think about the AI boom, chipmakers like Nvidia (NVDA) and AMD (AMD) usually come to mind first. But behind them sits another group: the companies that build the equipment needed to manufacture those advanced chips. Applied Materials (AMAT) and Lam Research (LRCX) are two of the most important players in that overlooked corner of the AI supply chain, and neither gets the attention their chipmaking customers do.
Both companies benefit as chipmakers pour money into AI data centers, high-bandwidth memory (HBM), and advanced chip manufacturing. So the real question for investors is where that spending creates the better long-term investment. Applied Materials offers broader exposure across semiconductor manufacturing, while Lam Research has built a stronger position in specialized processes that become more important as chips grow more complex.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
Applied Materials Offers Broader Exposure Across Chipmaking
 Screenshot courtesy of www.barchart.com
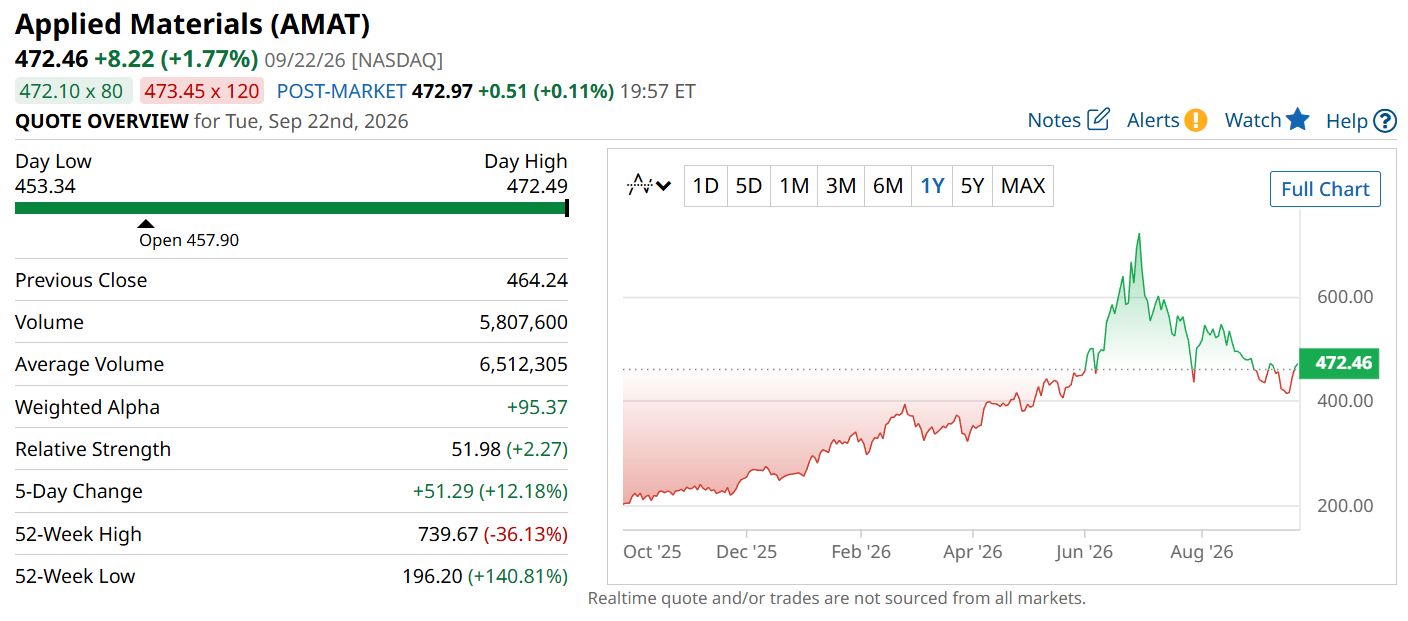
Applied Materials reaches more parts of chip manufacturing than Lam Research does. It covers materials engineering, deposition, ion implantation, inspection, and other steps that become more critical as chipmakers push features toward the atomic scale.
AI is opening up more opportunities because advanced chips need better power efficiency, faster memory, and more sophisticated packaging. For example, the growth of high-bandwidth memory, advanced logic, and chiplet designs requires more complex manufacturing steps, creating additional demand for equipment suppliers. Applied Materials sells into logic, memory, foundry, and services. As a result, this broader mix helps offset weaknesses in one area with strengths in another.
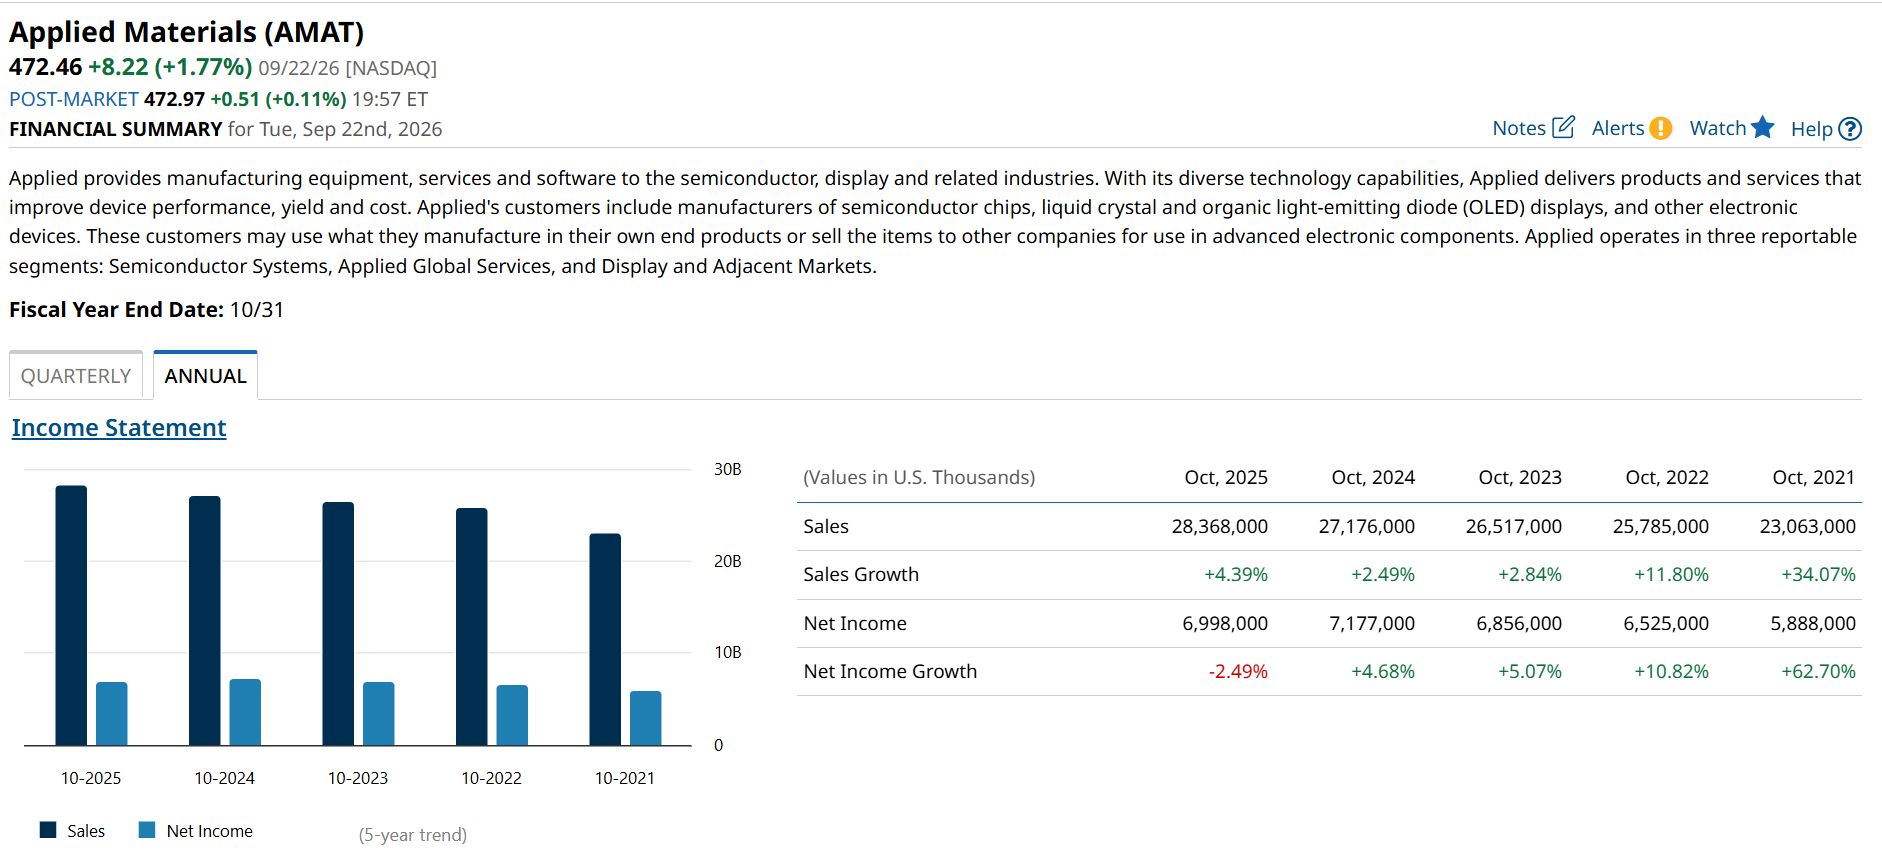
On top of that, its Applied Global Services segment adds another layer of stability. In fiscal 2025, the segment generated $6.4 billion in revenue from equipment maintenance, upgrades, and customer support, giving Applied Materials a large revenue stream beyond new equipment sales.
Meanwhile, its financial base looks strong overall. It generated $28.4 billion in full-year revenue and nearly $7 billion in net income, though that number’s 2% lower than in 2024.
 Screenshot courtesy of www.barchart.com
Plus, the company pays an annual forward dividend of $2.12, which translates to an approximate 0.45% yield.
However, investors are already paying for that mix of scale, diversification, and income, with the stock trading at 35x forward earnings.
Lam Research Brings a Sharper Specialized Edge
 Screenshot courtesy of www.barchart.com
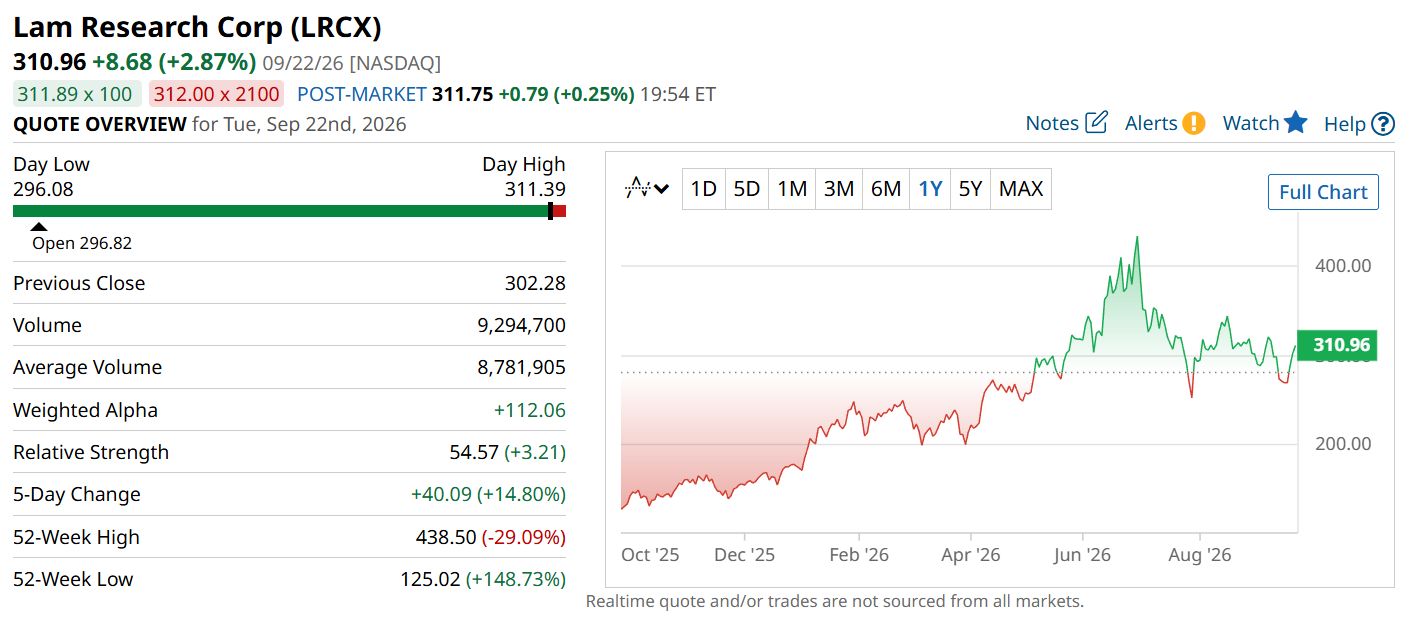
Lam Research, on the other hand, focuses more on etch and deposition. These two processes get harder as chipmakers build more complex three-dimensional chips, giving the company a strong position as manufacturers add more layers and need tighter control at each step.
While both companies compete in areas like deposition, their competitive advantages come from different parts of the manufacturing process.
A big part of Lam's opportunity comes from memory chips. For example, NAND and DRAM designs demand more precise etching and deposition, while HBM adds another source of demand as AI systems require faster, more efficient memory architectures.
On top of that, Lam has room to grow in logic and foundry work, with additional avenues for expansion in areas such as gate-all-around transistors, backside power delivery, and advanced packaging.
However, that same focus comes with risks. The company can benefit when memory spending accelerates, but it can also directly feel the slowdown when customers pull back on NAND or DRAM spending.
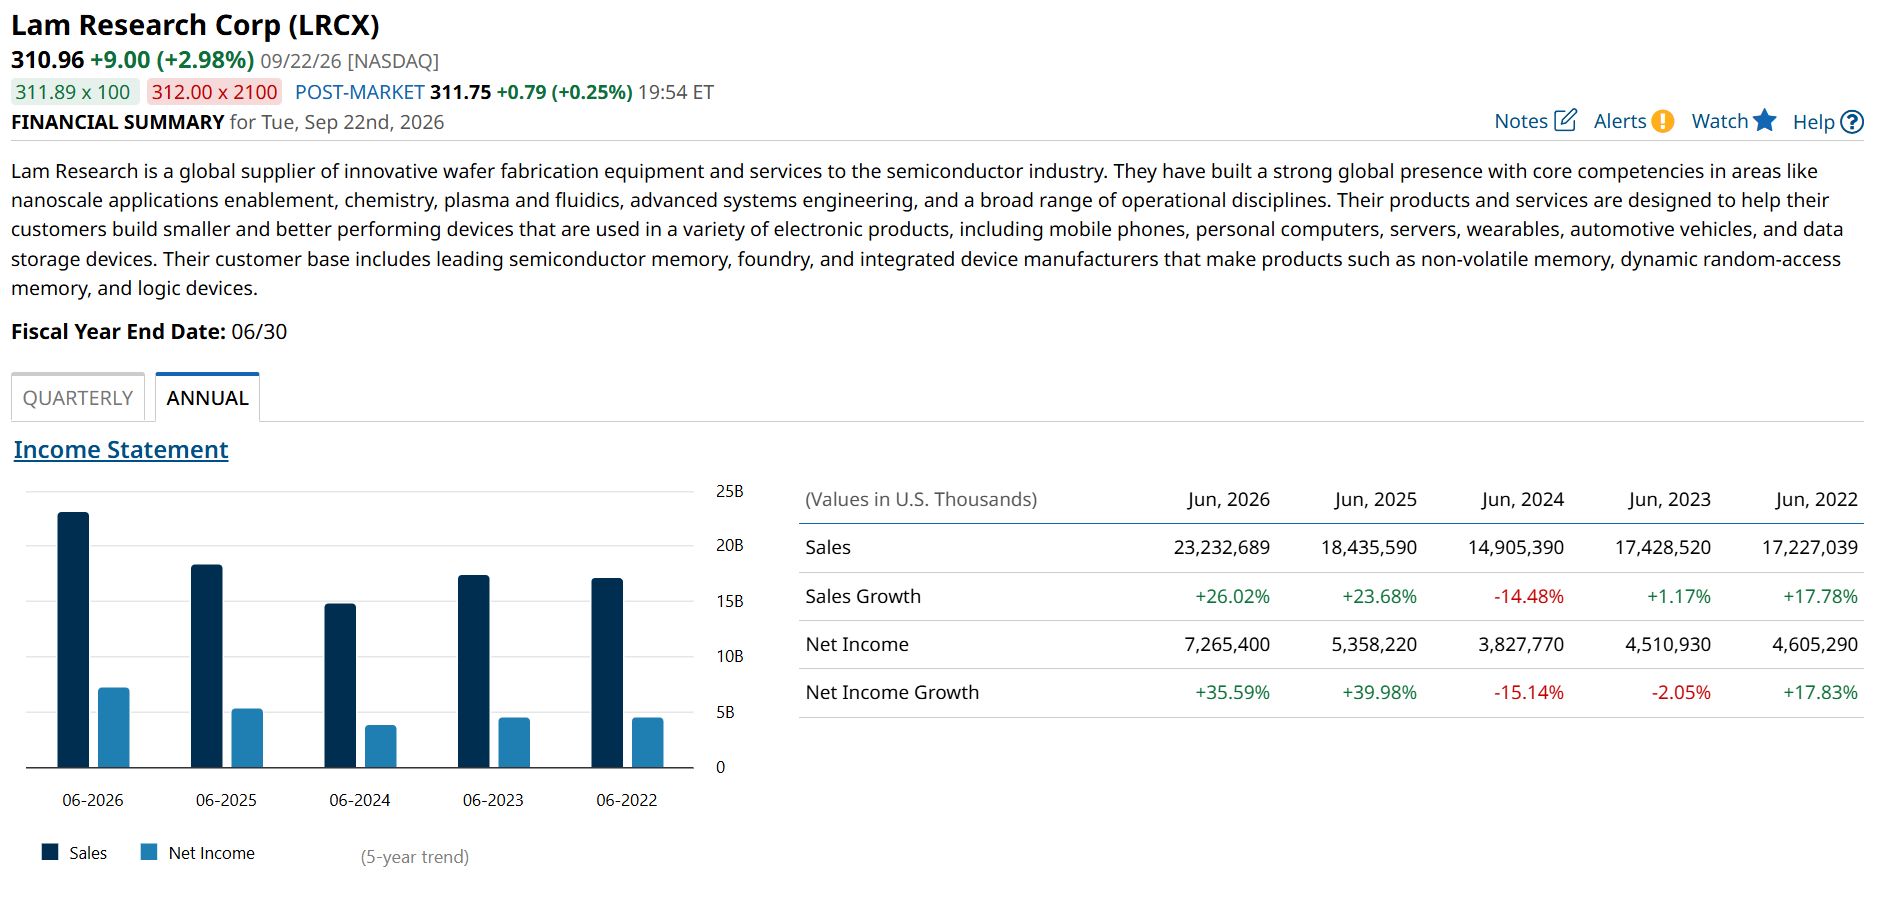
On the numbers, Lam Research generated $23.2 billion in fiscal 2026 revenue and $7.3 billion in net income, representing an impressive 35% growth.
 Screenshot courtesy of www.barchart.com
Lam Research also pays investors $1.04 per share annually, translating to a forward yield of 0.3%.
But at 31 times forward earnings, Lam Research is only modestly cheaper than Applied Materials. This small valuation gap means the company needs its stronger exposure to HBM, memory, and complex chip structures to translate into faster earnings growth for the stock to justify a higher price. So the choice between these two stocks comes down to which side of that tradeoff investors want to be on.
What Does Wall Street Say About AMAT and LRCX Stock?
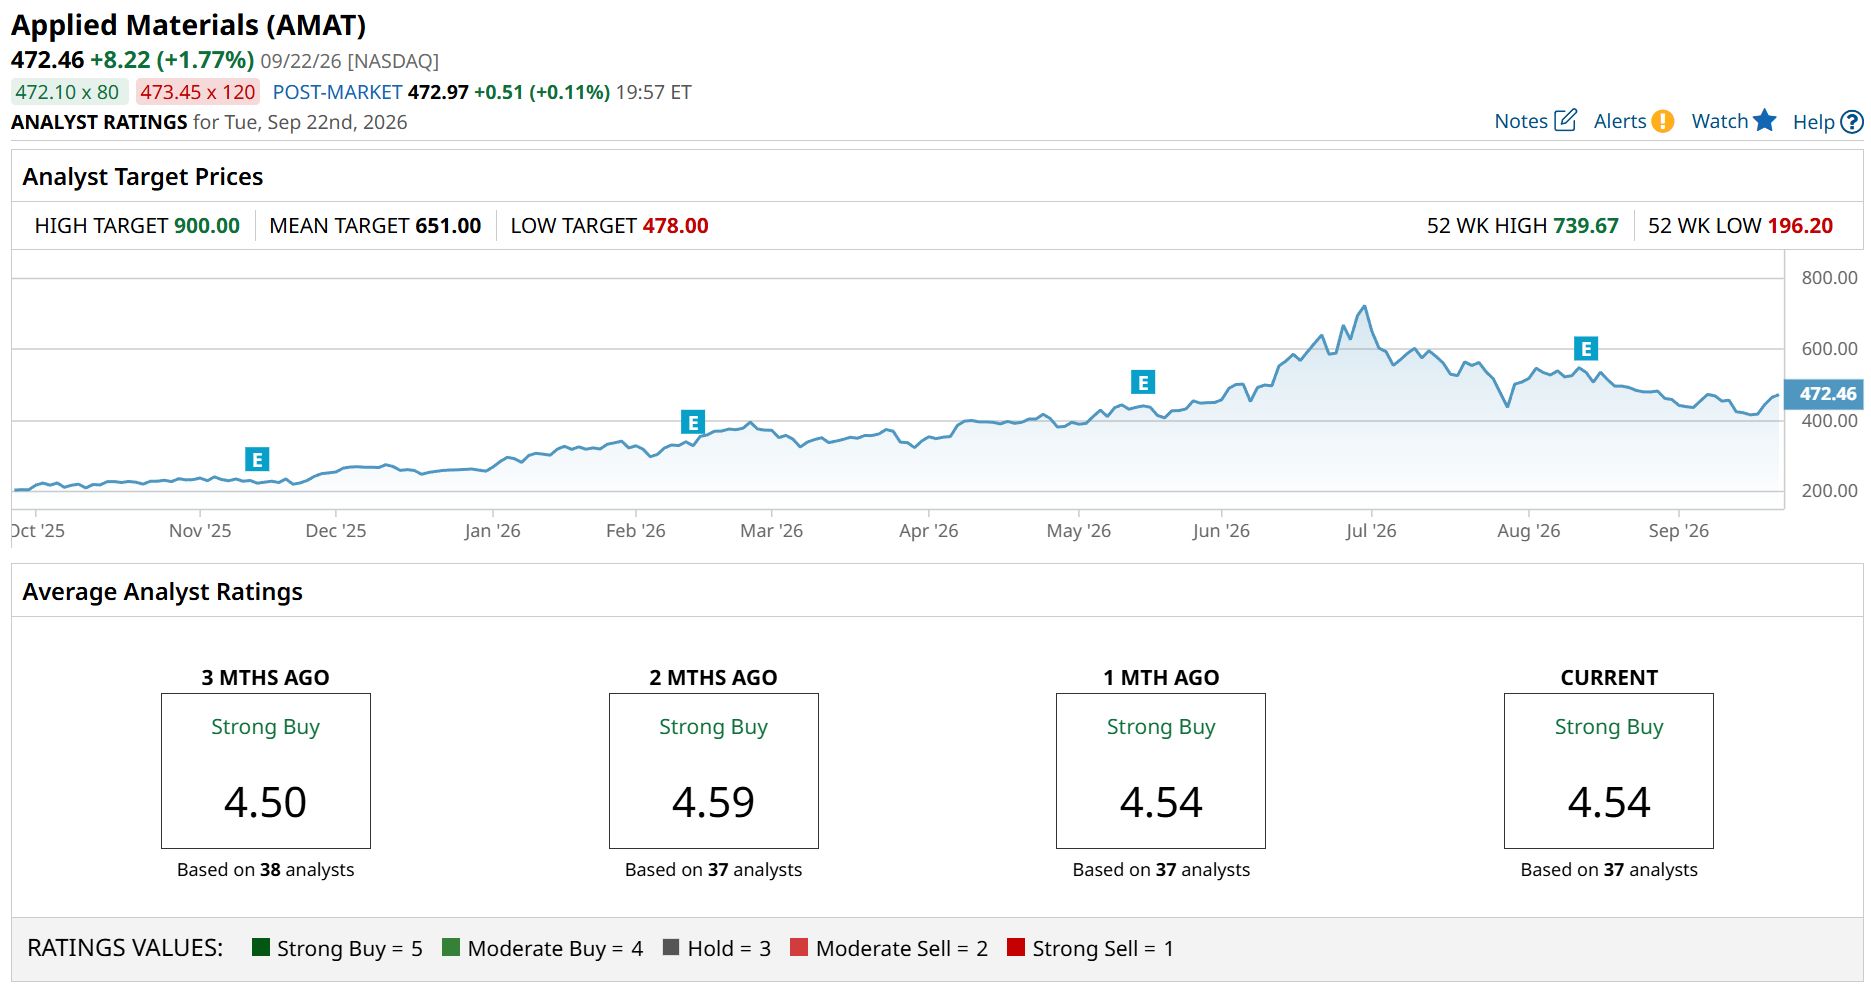
Applied Materials has a consensus “Strong Buy” rating from 37 analysts. Its high target price is $900, representing 90% potential upside.
 Screenshot courtesy of www.barchart.com
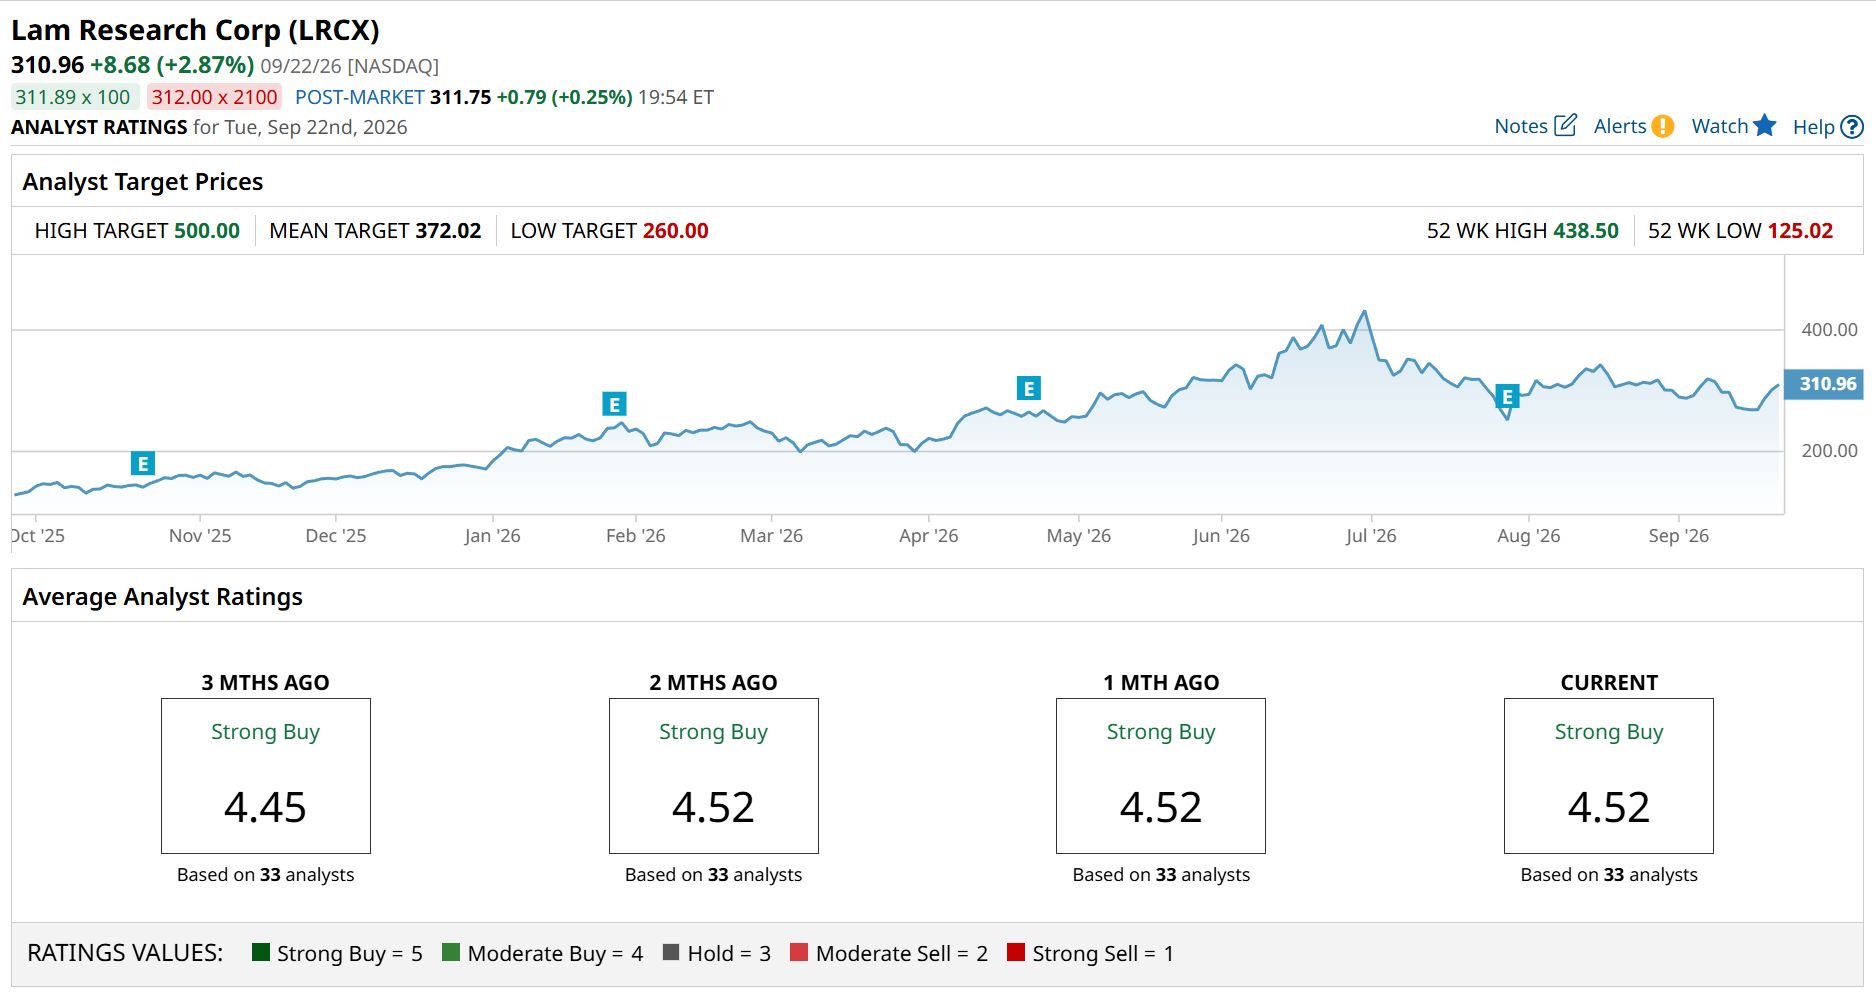
Similarly, a consensus among 33 analysts rates Lam Research a “Strong Buy,” with the $500 high target price representing a 61% potential upside.
 Screenshot courtesy of www.barchart.com
So, both stocks are rated similarly, but Applied Materials has more potential upside.
Which Chip Equipment Stock Fits Investors Best
Applied Materials' broader exposure across logic, memory, foundry, advanced packaging, and services gives investors several sources of growth and helps reduce the impact of weakness in any one part of the semiconductor cycle. Lam Research has a stronger specialized position, and as chipmakers use more complex designs and increase production of HBM and other advanced memory, its etch and deposition expertise becomes more valuable.
For long-term investors, this overlooked rivalry offers two credible ways to benefit from AI infrastructure growth. Applied Materials looks better suited to those who value diversification and steadier exposure to semiconductor manufacturing demand, while Lam Research offers a more focused upside tied to the growing complexity of advanced chips.
On the date of publication, Rick Orford did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Nvidia and AMD Get the Headlines. The Real AI Winners Might Be Applied Materials and Lam Research. Costco Earnings Bull Put Spread has a High Probability of Success As Amazon Strikes a Blow Against the New Muse Bot, Here’s How You Should Play META Stock How to Play MicroStrategy Stock as Bitcoin Prices Surge Higher Again