

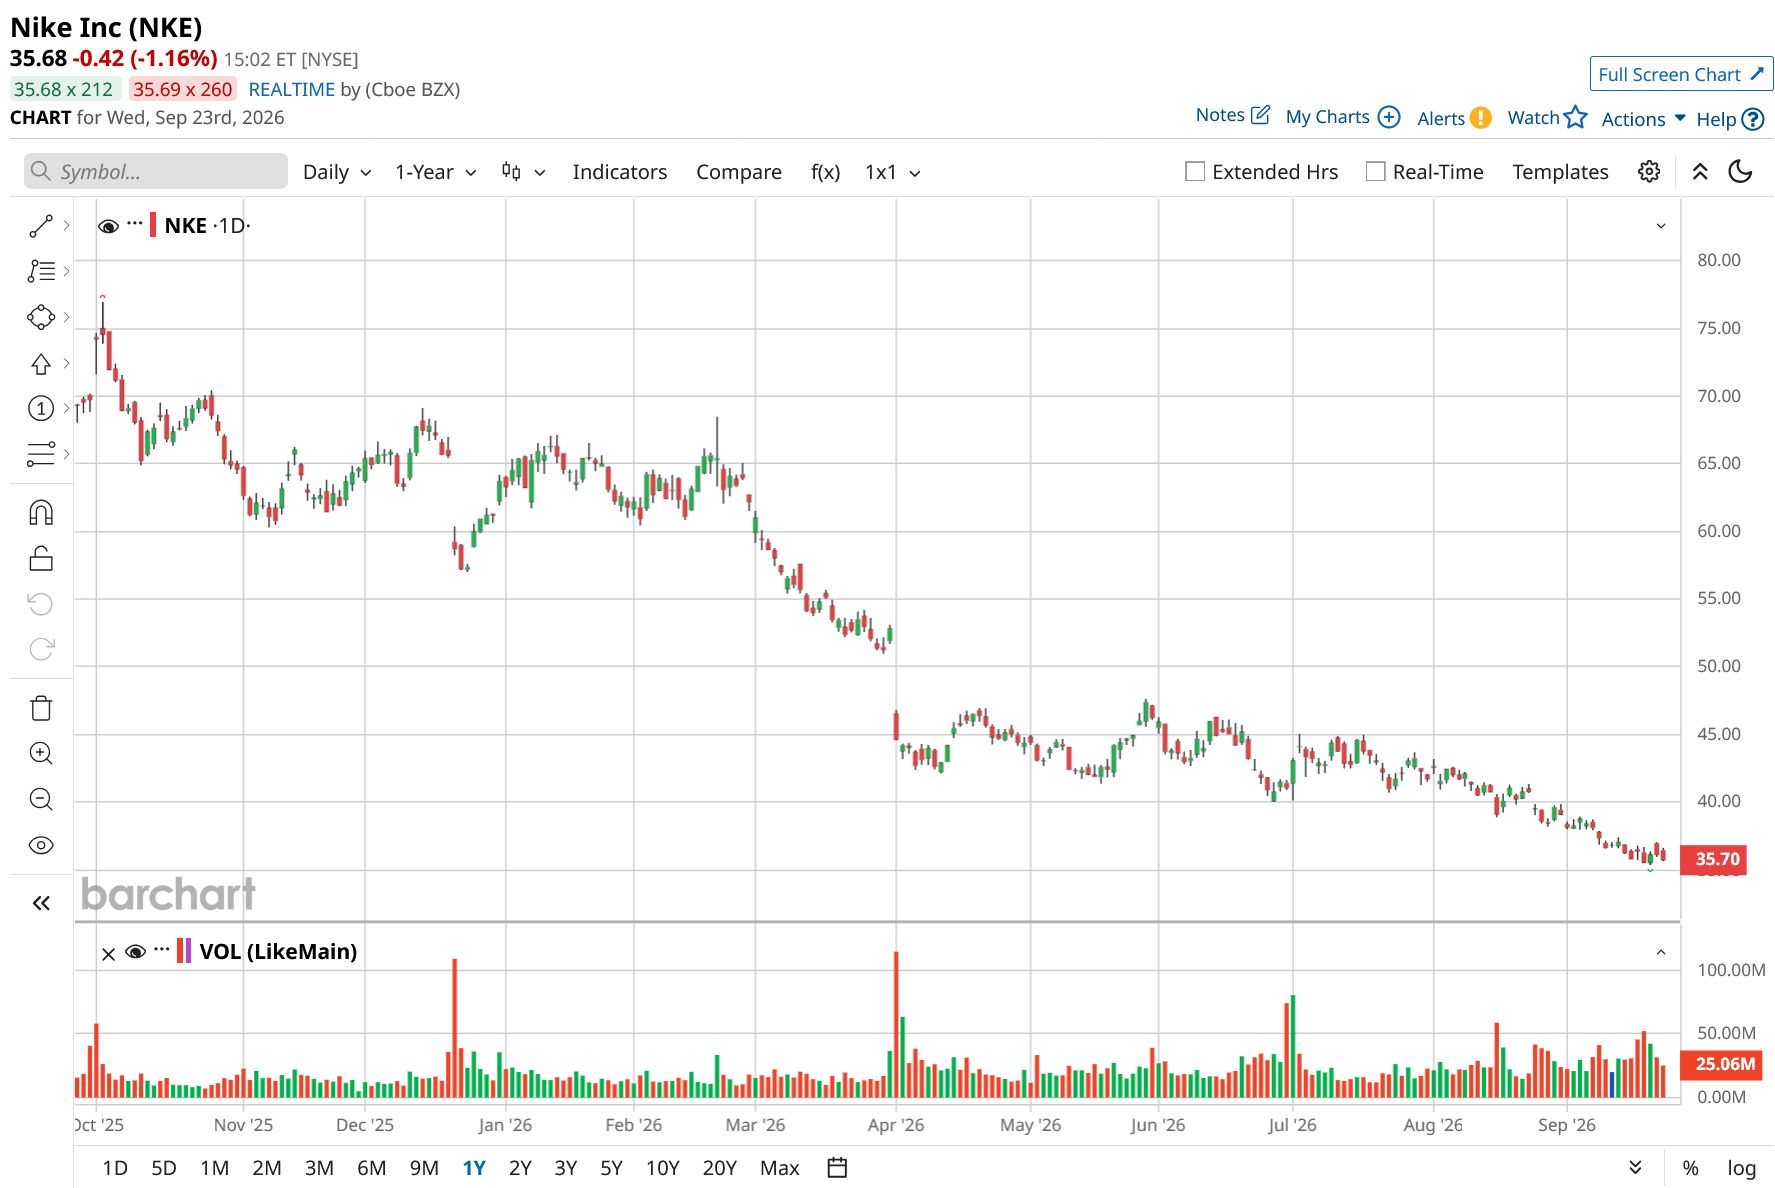
Nike’s (NKE) recent stock performance reflects the scale of the challenges the company faces. Shares have declined about 53% from their 52-week high. Moreover, Nike stock has underperformed the broader market by a significant margin as the company contends with macroeconomic pressures, changing consumer demand, and intensifying competition.
Although NKE stock has lost significant value and has initiated a significant operational reset aimed at restoring growth and strengthening its competitive position, now is not the time to buy Nike stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Nike Faces Challenges Ahead
Nike continues to operate in a challenging business environment, with its near-term recovery constrained by weakening consumer demand, subdued retail activity, regional pressures, and elevated promotional requirements.
During its Q4 earnings call, management said financial results were broadly consistent with internal expectations. However, the company also acknowledged that market conditions deteriorated as the quarter progressed. Retail trends initially showed greater resilience, particularly in North America, but that momentum weakened by mid-April, when Nike began experiencing a noticeable slowdown in retail sales.
The broader decline in discretionary consumer spending matters for Nike because sportswear is a substantial part of its business. The double-digit decline in sportswear during the fourth quarter suggests that consumers are becoming more selective in their purchases, creating additional pressure on sales volumes and revenue growth.
 www.barchart.com
Regional Performance to Remain Uneven
Nike’s regional performance further illustrates the uneven nature of its recovery. North America initially demonstrated stronger retail trends, but sustained weakness in other major markets could offset this improvement. Greater China remains a key concern, as subdued demand and efforts to reduce promotional activity are likely to constrain short-term sales. While reducing promotions may support healthier pricing and margins over time, it can also limit near-term sales growth as the company balances profitability with inventory management.
NIKE Direct is also expected to remain under pressure, with weakness across both digital channels and physical stores. This is strategically significant because the direct-to-consumer model has been an important part of Nike’s efforts to strengthen its relationship with consumers and improve margins. Continued declines in direct sales could, therefore, slow the company’s broader efforts to improve its business mix.
The EMEA region presents additional challenges. Nike is still managing relatively high inventory and promotional levels, while disruptions in the Middle East have created further operational uncertainty. Moreover, the region has relatively high exposure to sportswear, which is currently under pressure. These factors could increase the need for discounting and promotions, potentially putting further pressure on profitability.
Nike’s Guidance Indicates Continued Weakness
Nike’s forward guidance strengthens the view that the recovery will take time and the company will likely face challenges in the near future. Management expects revenue to decline by a low- to mid-single-digit rate in the near term. Moreover, the second quarter is expected to experience sequential deceleration from the first quarter.
Overall, Nike’s near-term financial performance is likely to remain under pressure, led by weak sportswear demand, softer retail traffic, regional weakness, primarily in Greater China and EMEA, and promotional pressures. In addition, a weak broader consumer spending environment will likely hurt traffic and Nike’s growth.
Analysts Maintain a “Hold” Ahead of Q1
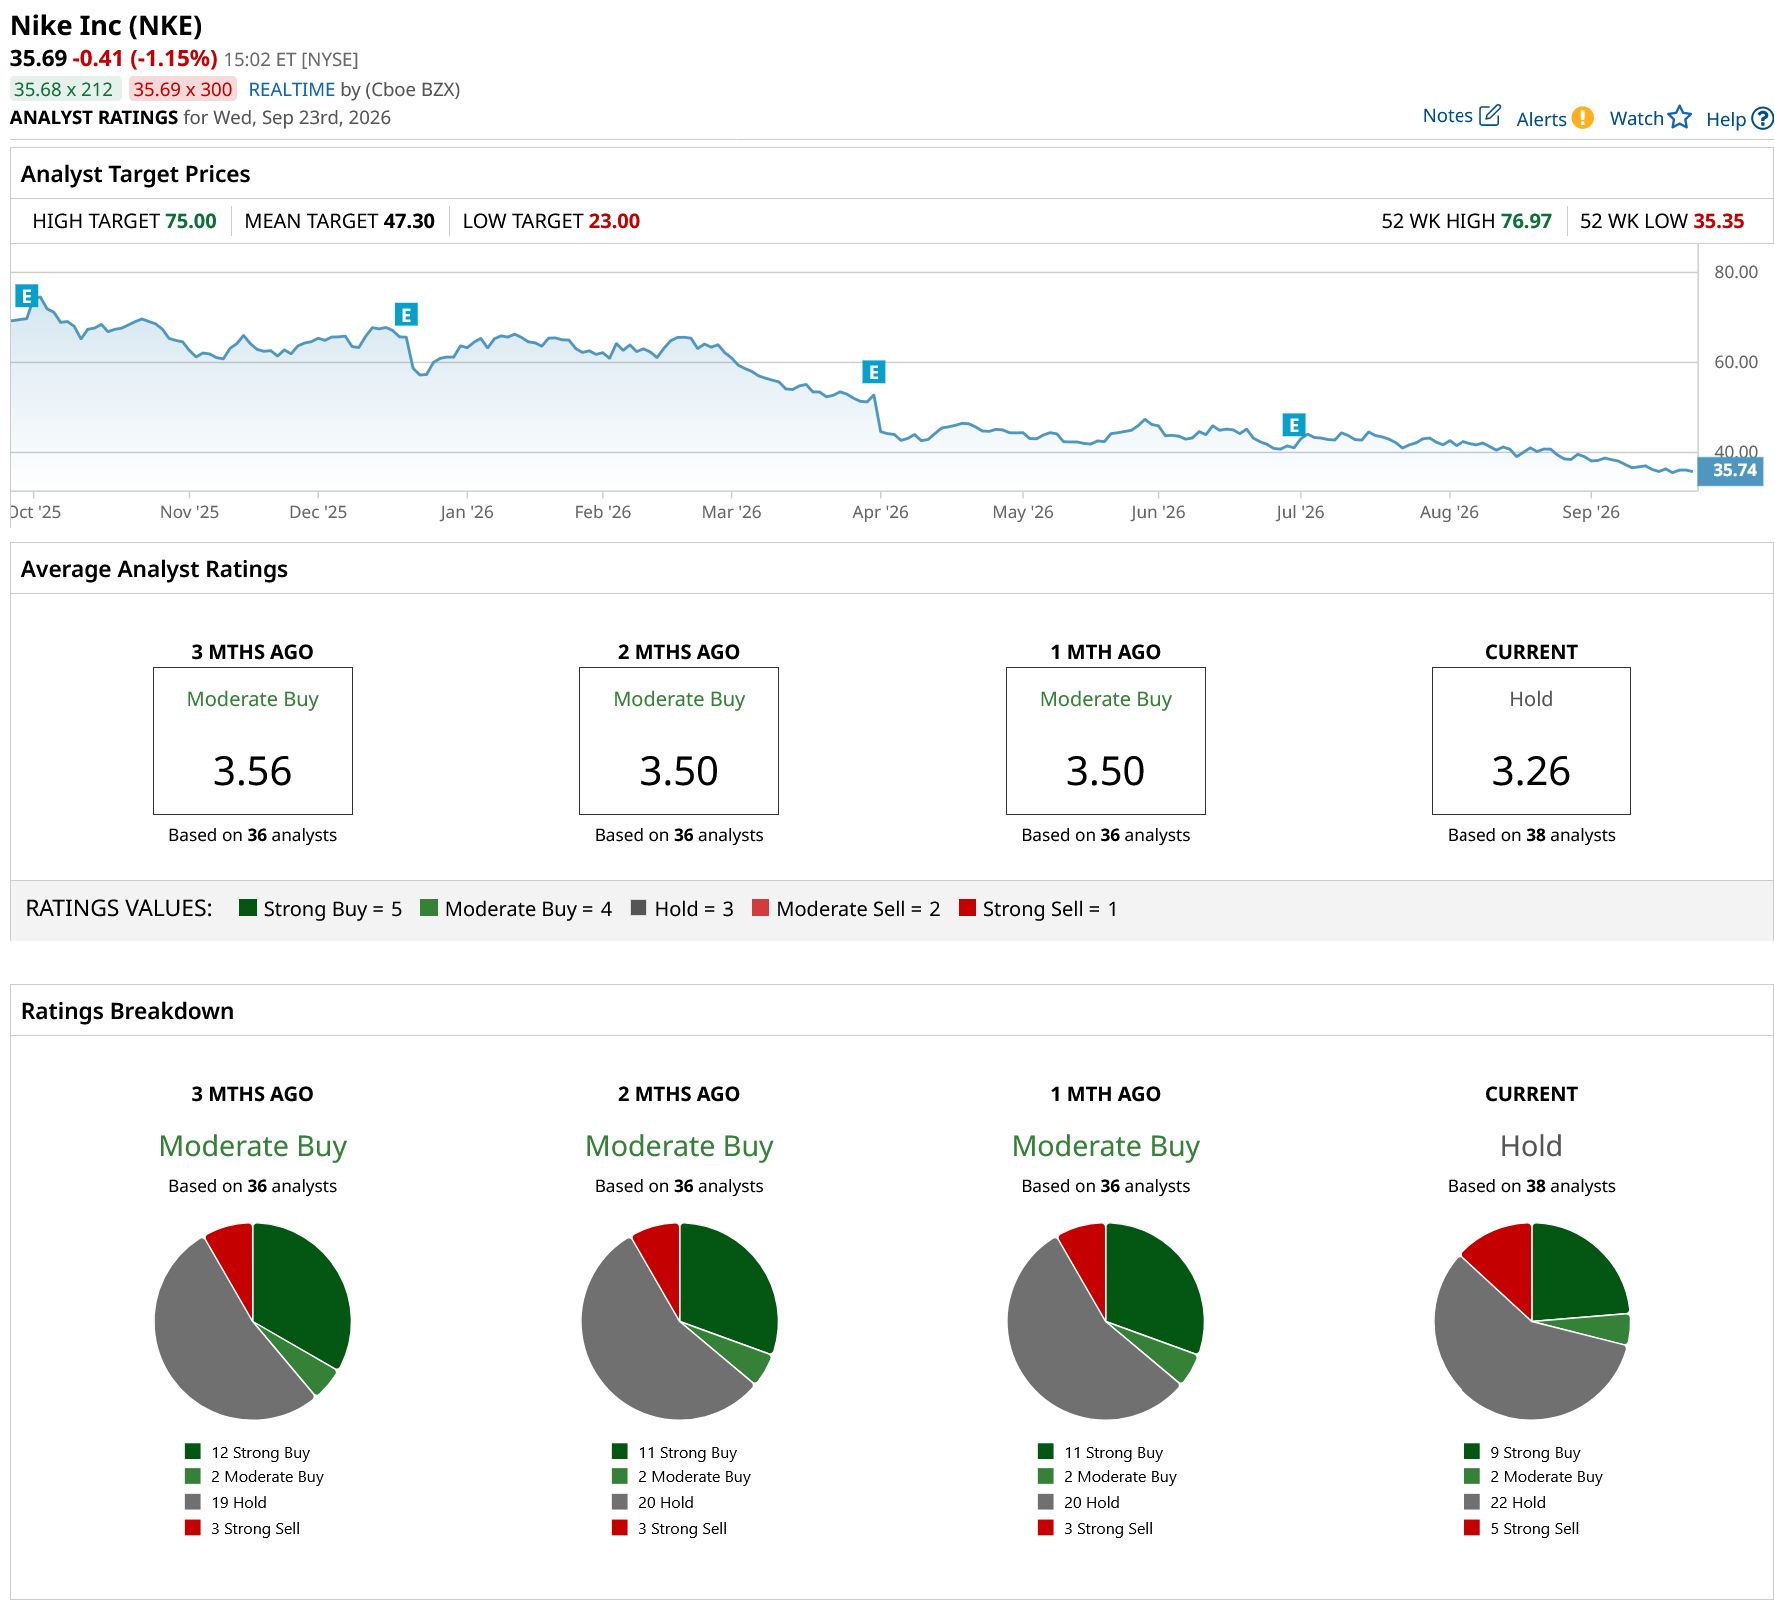
The market’s attention is turning to Nike’s upcoming first-quarter fiscal 2027 earnings report, scheduled for Oct. 1. However, analyst sentiment toward the athletic apparel giant has weakened. The number of analysts assigning NKE stock a “Strong Buy” rating has fallen to nine from 11 a month earlier. At the same time, a majority of analysts continue to recommend a “Hold.”
The shift in ratings suggests that analysts are becoming more cautious about Nike’s near-term prospects.
NKE Stock Is Still Not a Buy
Nike’s operational reset provides a potential path toward recovery, but the company is likely to remain under pressure in the near term. Weak consumer demand, uneven regional performance, elevated promotions, and declining direct sales are likely to limit revenue and earnings improvement in the quarters ahead. With management already signaling continued revenue declines and analyst sentiment remaining cautious ahead of the fiscal 2027 first-quarter results, the risk-reward profile does not yet justify buying NKE stock.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
AMD Becomes the 14th Company to Cross $1 Trillion In Market Cap. What This Means for AMD Stock. Surf Air Mobility Stock Jumps on a SkyDance Air Deal. How to Play SRFM Here. IonQ Just Nabbed a Quantum Computing Partnership with Nvidia. How to Play IONQ Stock Here. Lumentum Shares Are Up After an AI Optical Tech Partnership With Corning and Qualcomm. What This Means for LITE Stock.