

According to independent energy research and business intelligence firm Rystad Energy, the U.S. faces a 98-gigawatt accredited capacity shortfall by 2035. The key demand drivers are growth in data centers and the revival of domestic manufacturing. Yet, when clean power provider Fervo Energy (FRVO) held its IPO in May, the $7.7 billion valuation assigned was for a company that has yet to generate significant revenue.
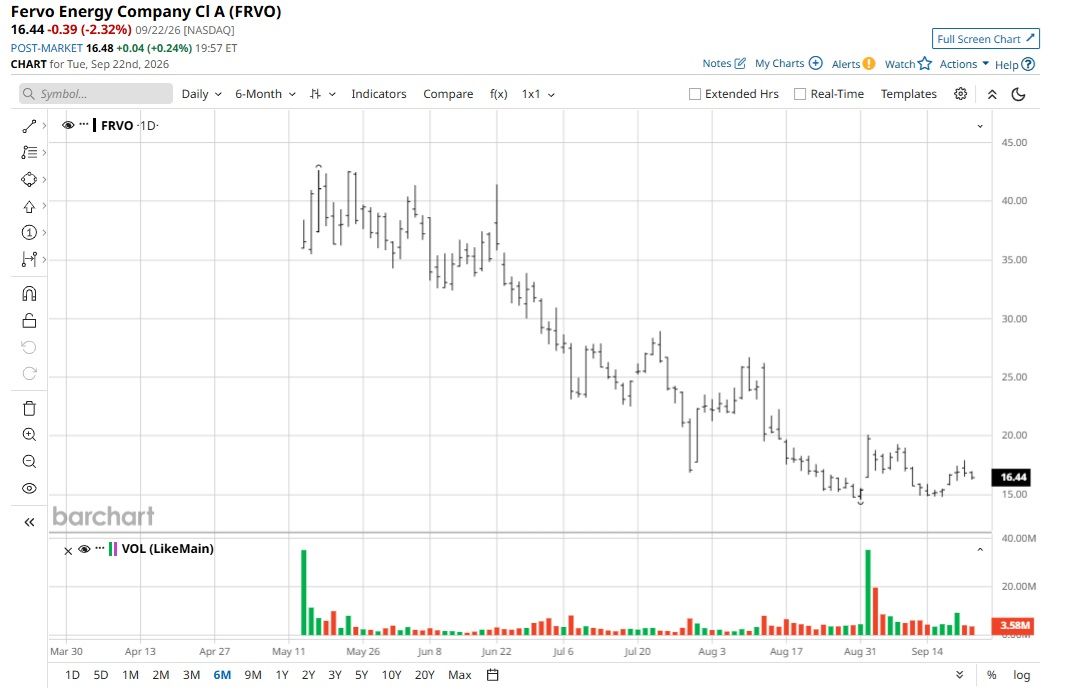
Its shares subsequently suffered a sustained correction, as valuation concerns overshadowed the listing euphoria. Despite the stock's sharp decline, positive business developments make it a good time to gradually accumulate FRVO stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Notably, Fervo Energy received two orders totaling $20 million from the U.S. Department of Energy. The objective is to “accelerate the development of enhanced geothermal systems (EGS) in Idaho and Nevada and to expand next-generation geothermal across the western United States.” These awards offer strong validation of the company’s technology.
Contracted revenue is also rapidly expanding. According to its April prospectus, Fervo Energy had $7.2 billion in contracted backlog revenue under its power purchase agreements. By September, contracted revenue had swelled to $11.9 billion, a 65% increase. This includes a 3GW framework agreement to power Google (GOOG) (GOOGL) data centers. This long-term growth visibility makes FRVO stock worth considering.
About Fervo Energy Stock
Headquartered in Houston, Fervo Energy is a geothermal energy company with a focus on large-scale deployment of enhanced geothermal systems. The company is applying proven technologies like horizontal drilling and multi-stage hydraulic fracturing to transform geothermal energy from a niche resource to a utility-scale power solution that is clean, reliable, and cost-competitive.
The company’s 3 MW pilot project using an enhanced geothermal system has been active since 2023. Fervo Energy also has 500 MW under construction that is expected to first deliver power in late 2026, with the operating capacity expected to reach approximately 100 MW by early 2027.
Additionally, the company has 550 MW that is ready-to-build, positioning Fervo Energy for 1 GW in operational capacity by 2030. It’s worth adding here that as of June, the company had a 650,000-acre land position at Cape Station, Utah. Currently, Fervo estimates it has advanced development of 4.1 GW of capacity potential at this site.
While the long-term outlook seems promising, Fervo Energy stock carries steep valuations considering its revenue is minuscule, and projects are in a development stage. It’s therefore not surprising that FRVO stock has declined by 61% from its $42.65 high following its IPO.
 www.barchart.com
Significant Development Potential
The company’s 3 MW pilot plant is the tip of the iceberg. To put things into perspective, Fervo Energy has 500 MW under construction and another 550 MW that’s ready-to-build. Additionally, the company has 3 GW of capacity in the advanced development stage.
Fervo Energy has also commissioned and received independent HIIP studies for 48.6 GW that are in early-stage development. If this is included, the potential capacity from the current land bank is in excess of 50 GW. Given the impending demand-supply mismatch in the power sector, it’s likely that capacity will be contracted well before it’s commissioned.
Therefore, there is sustained growth visibility. On the flip side, the commissioning of this capacity will require meaningful capital expenditure. It’s therefore likely that Fervo Energy will pursue equity dilution in the coming years. This risk is likely to be offset by industry tailwinds and sustained growth.
What Do Analysts Say About FRVO Stock?
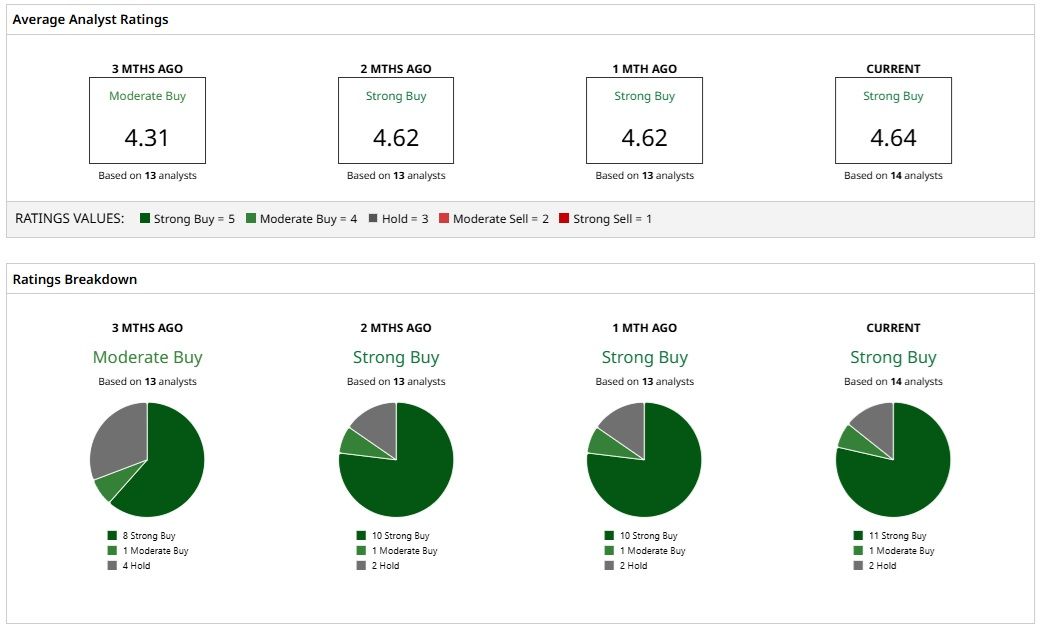
Based on 14 analysts with coverage, FRVO stock has a consensus “Strong Buy” rating. While 11 analysts have a “Strong Buy” rating for the stock, one has a “Moderate Buy,” and two have a “Hold” rating.
The mean price target of $40.75 represents potential upside of 147.9% from current levels. Further, the most bullish price target of $51 suggests that FRVO stock could climb as much as 210.2% from here.
 www.barchart.com
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Deep Correction in Fervo Stock Provides an Opportunity to Accumulate McDonald’s Increased Its Dividend by Nearly 4%. How to Play MCD Stock Here. Billionaire Mark Cuban Said He’d Trust a Seeing-Eye Dog Over a Self-Driving Car, ‘A Dog Will Recognize Adversarial Situations Better Than AI Can’ CoreWeave Priced an Upsized $3.7 Billion Convertible Note as Capex Spending Spikes. What That Means for CRWV Stock Fans.