

Dividend-paying stocks are a reliable source of passive income, especially when a company has a long history of increasing its payouts. Enterprise Products Partners (EPD) is an attractive option in this category, offering a relatively high dividend yield with nearly three decades of consecutive distribution growth.
To be precise, EPD currently offers an annualized yield of approximately 6% and has raised its dividend for 28 consecutive years.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
EPD’s ability to maintain and grow its distributions is supported by a broad portfolio of midstream infrastructure and relatively dependable cash flows. Enterprise Products Partners operates an integrated network linking major U.S. natural gas, natural gas liquids (NGL), and crude oil producing regions with domestic consumers and international export destinations. The scale and connectivity of this network help maintain strong asset utilization and contribute to steady distributable cash flow.
Another important source of stability is the company’s reliance on long-term, fee-based agreements. Because much of its revenue is tied to contracted services rather than directly to commodity prices, EPD’s operations can be less exposed to fluctuations in oil and natural gas prices.
Enterprise Products Partners also maintains a broad customer base to reduce its dependence on any individual client. Its 200 largest customers accounted for 96.7% of consolidated revenue in 2025, while no individual customer contributed 10% or more of total consolidated revenue. This customer diversification supports the company’s revenue base.
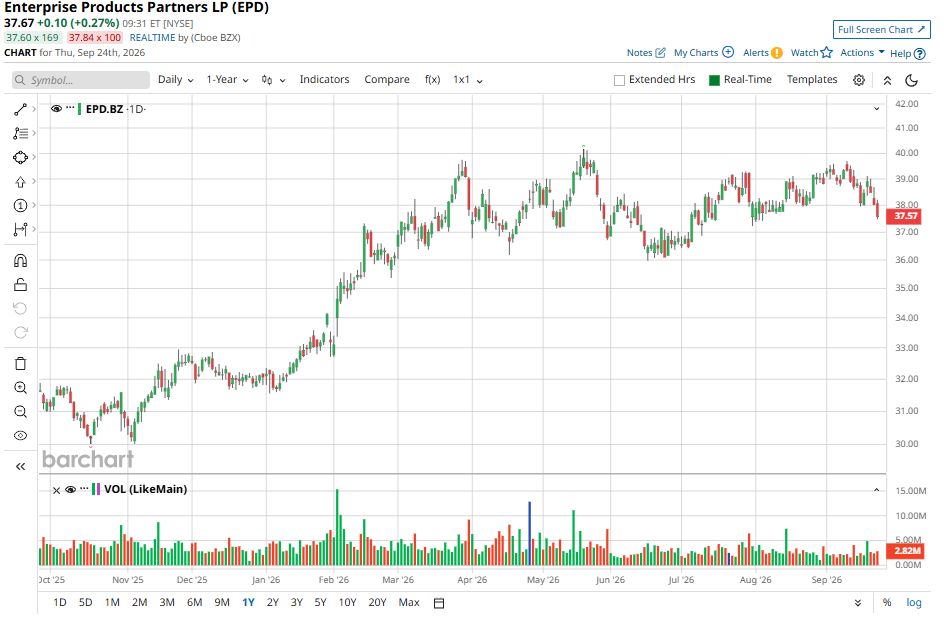 www.barchart.com
EPD Is Positioned to Sustain and Increase Its Dividend
Enterprise Products Partners appears well-positioned to maintain its dividend and continue raising distributions over the coming years. EPD’s recent operating performance indicates that its integrated midstream infrastructure continues to benefit from strong demand for U.S. energy commodities. Higher throughput, earnings, and cash generation during the second quarter suggest that EPD is converting favorable market conditions into stronger financial performance.
EPD’s large-scale and vast infrastructure network position it well to capitalize on demand. This broad infrastructure footprint allows the company to capture economic value at several stages of the energy value chain. The ability to redirect and utilize its assets across different markets remains an important competitive advantage for Enterprise.
It generated approximately $2.8 billion in EBITDA, a 17% increase from the prior-year period, which provided 1.0x coverage of its distributions.
Volume growth was also significant. Its pipeline throughput increased 8% year-over-year (YoY), while marine terminal volumes rose 33%. Total volumes handled by EPD reached approximately 14.7 million barrels of oil equivalent per day. Taken together, these numbers indicate that higher activity across EPD’s network is translating into meaningful earnings and cash flow growth.
The broader U.S. energy outlook remains favorable for the company. Continued U.S. production growth should sustain demand for transportation, processing, storage, and export infrastructure. At the same time, global energy consumption remains an essential driver of U.S. export opportunities. Geopolitical disruptions and conflicts in Europe and the Middle East could further strengthen the strategic importance of reliable U.S. energy supplies and export infrastructure.
Natural gas represents another potentially significant source of incremental demand for EPD’s infrastructure. U.S. electricity consumption is expected to increase as manufacturing and industrial activity increase and power-intensive data centers expand. Growing power demand could support higher natural gas consumption, creating additional opportunities for infrastructure owners involved in gathering, processing, transportation, storage, and exports.
Earn 6% Yield With EPD Stock
Enterprise Products Partners offers a high 6% yield and has an exceptional 28-year record of distribution growth, supported by diversified energy infrastructure, fee-based contracts, and resilient cash generation.
Its solid EBITDA growth and increase in pipeline and terminal volumes indicate that EPD continues to benefit from growing U.S. energy production and export demand.
While no dividend is guaranteed, EPD’s scale, an integrated asset base, and exposure to long-term energy infrastructure demand provide a solid foundation for sustaining and potentially increasing distributions over time.
Analysts maintain a “Moderate Buy” consensus rating on EPD stock.
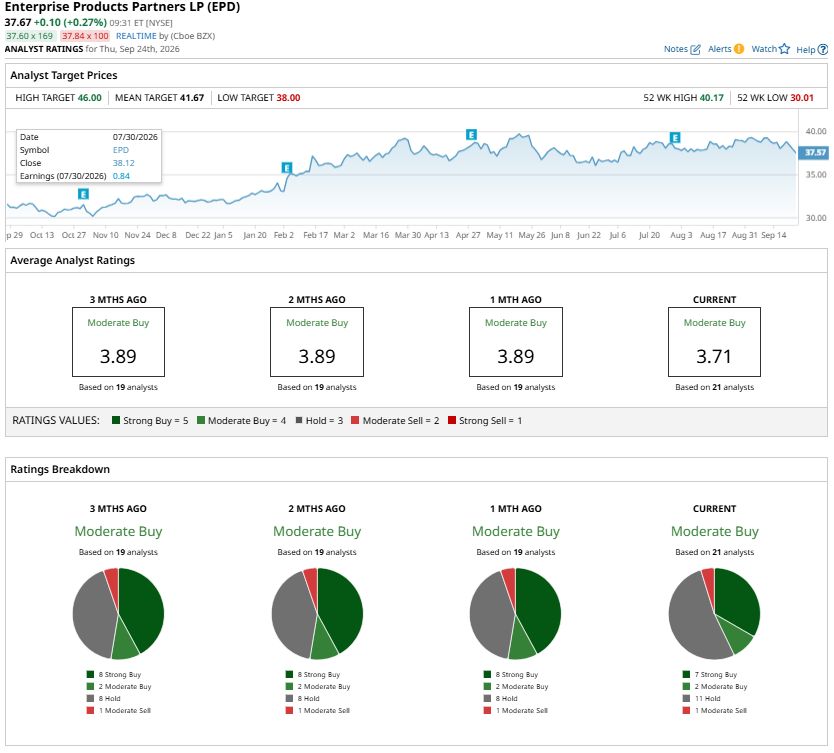 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Stock Pays a 6% Yield — and Has Raised Its Dividend for 28 Straight Years Palantir vs. Salesforce: One Trades at 144x Earnings. Only One Pays You to Own It. McDonald’s Increased Its Dividend by Nearly 4%. How to Play MCD Stock Here. An $8.5 Billion Catalyst Is Rocking McDonald’s Stock