

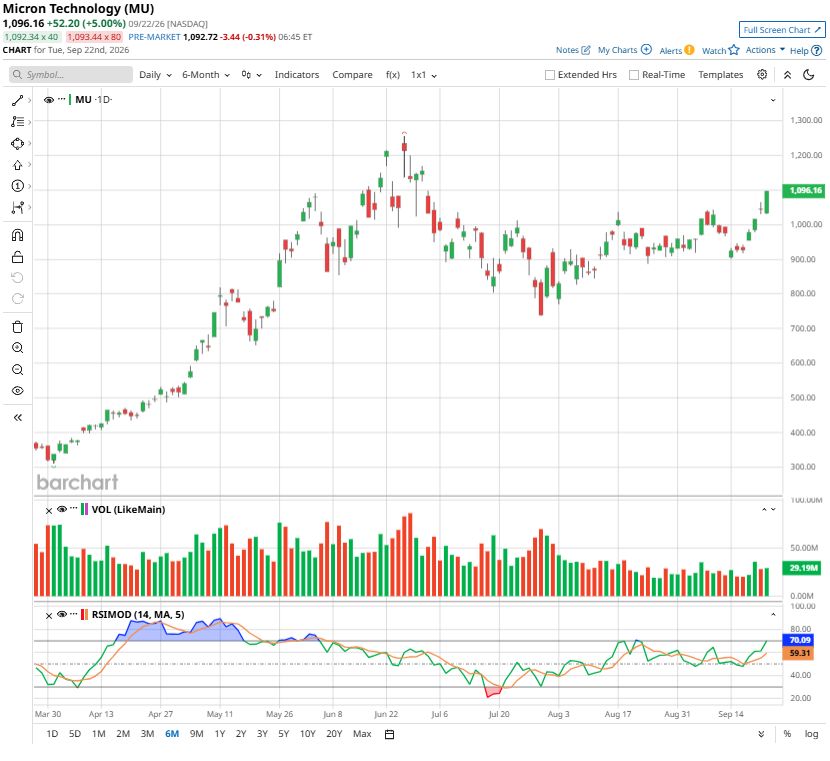
Micron Technology (MU) is scheduled to report its fiscal fourth-quarter results on Sept. 30. MU stock surged more than 15% following its fiscal Q3 results, and Q4 could be no different, as the favorable operating environment is likely to translate into strong growth.
Micron is expected to benefit from the ongoing strength in its data-center business. In addition, higher average selling prices (ASPs) should translate into meaningful margin expansion and earnings growth, supporting its share price.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The valuation is another reason to buy MU stock ahead of the Q4 report. Despite Micron’s recent share price gains, MU stock still offers a relatively reasonable valuation with respect to its earnings growth. This could boost the stock price even further.
 www.barchart.com
Micron’s Q4 Numbers Are Expected to Remain Solid
Micron’s Q4 financial numbers are expected to remain solid with continued strength across revenue, margins, and earnings. The key driver remains a favorable supply-demand imbalance. Demand for memory products continues to exceed supply, and this dynamic is expected to keep pricing conditions favorable in the near term.
Both growth in bit shipments and ASP increases are likely to drive the top and bottom line. Meanwhile, Micron’s data-center business could continue to show strength and is likely to remain the key growth engine.
Micron’s data-center revenue surpassed $25 billion in fiscal Q3, implying an annualized run rate (ARR) above $100 billion. Momentum in this business is expected to continue into Q4 and beyond as artificial intelligence (AI) drives significant data-center growth.
The company reported Q3 revenue of $41.5 billion, representing a 74% sequential increase and a 346% year-over-year (YOY) jump. Against this elevated base, management is guiding for Q4 revenue of approximately $50 billion, reflecting a sequential increase of more than 20%.
AI remains central to the outlook. The rapid expansion of AI computing is increasing demand for high-performance memory in data centers, while broader industry trends point to significant growth in DRAM and NAND bit shipments. At the same time, supply has not fully kept pace with demand, creating conditions that allow memory manufacturers to raise prices and improve margins.
Profitability is also expected to remain strong. Micron projects a Q4 gross margin of 86%, compared with 84.9% in Q3. Importantly, the anticipated margin expansion is expected even as the pace of memory price increases moderates. This suggests that improvements in product mix, scale, and operating leverage could increasingly contribute to profitability alongside pricing.
Management’s earnings guidance points in the same direction. Micron forecast Q4 EPS of $31, representing further sequential and YOY growth. The current analyst consensus estimate for the quarter is slightly higher at $31.24 per share, implying expectations that Micron could again outperform its own guidance. The company has exceeded Wall Street’s EPS estimates for four consecutive quarters, including a nearly 19% upside surprise in the most recently reported quarter.
Overall, Micron’s Q4 will likely benefit from AI-driven demand, constrained industry supply, stronger data-center revenue, and improving product mix. All of these factors should give the company's bottom line a solid push.
The Valuation Is Attractive
While MU stock has rallied significantly, its valuation still looks compelling. Micron trades at 6.7 times forward earnings, which is low given its expected bottom-line growth. The consensus estimate from analysts for fiscal 2027 earnings indicates that its bottom line could more than double despite tough YOY comparisons.
Overall, Micron's solid EPS growth and low earnings multiple indicate further upside in MU stock.
The Bottom Line for Micron Stock
The Sept. 30 earnings report should reflect strong operating momentum, supported by AI-driven data-center demand, favorable memory pricing, and expanding margins. With revenue and EPS expected to grow further and the valuation remaining relatively modest against projected earnings growth, the Q4 results could strengthen the market’s positive view of Micron's fundamentals.
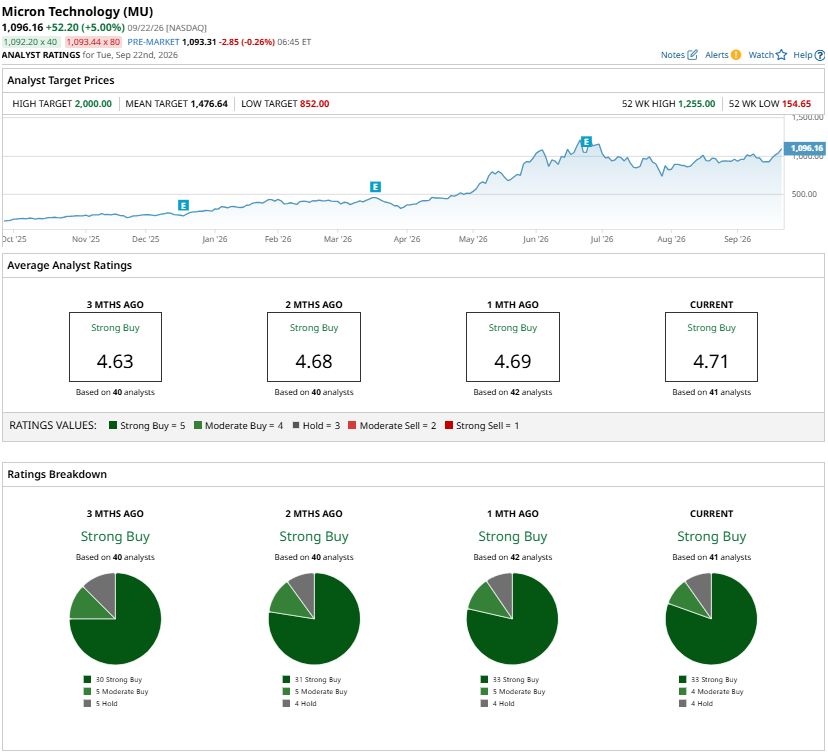
Analysts remain bullish ahead of the release. Currently, the stock carries a consensus “Strong Buy” rating on Wall Street based on 41 analysts with coverage.
 www.barchart.com
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.