

McCormick & Company, Incorporated (MKC), based in Hunt Valley, Maryland, is a global flavor company specializing in herbs, spices, seasonings, sauces and flavor solutions. With a market capitalization of approximately $12.9 billion, the company serves consumers through its branded products while also providing customized flavor solutions to food manufacturers, foodservice operators and restaurants worldwide.
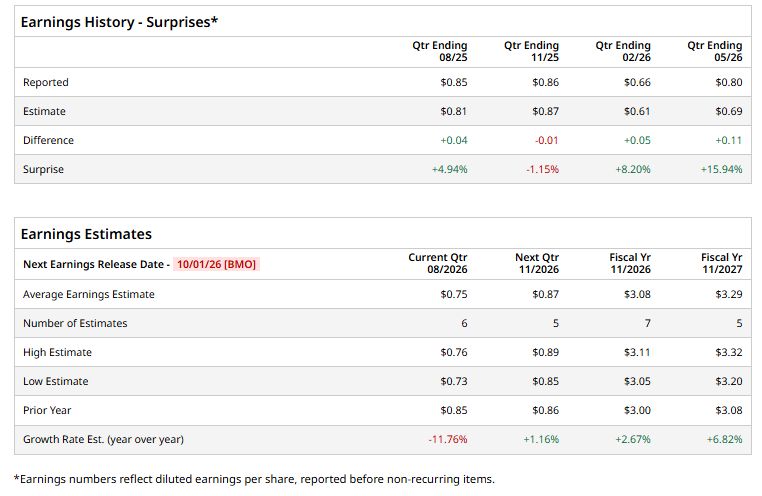
MKC is set to report its Q3 earnings on Thursday, October 1, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of 75 cents, down 11.8% from 85 cents in the year-ago quarter. MKC has exceeded Wall Street’s EPS estimates in three of the past four quarters, while missing expectations in the remaining quarter.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect the company to report EPS of $3.08, up 2.7% from $3 in fiscal 2025. Moreover, EPS is projected to increase 6.8% year over year to $3.29 in fiscal 2027.
 www.barchart.com
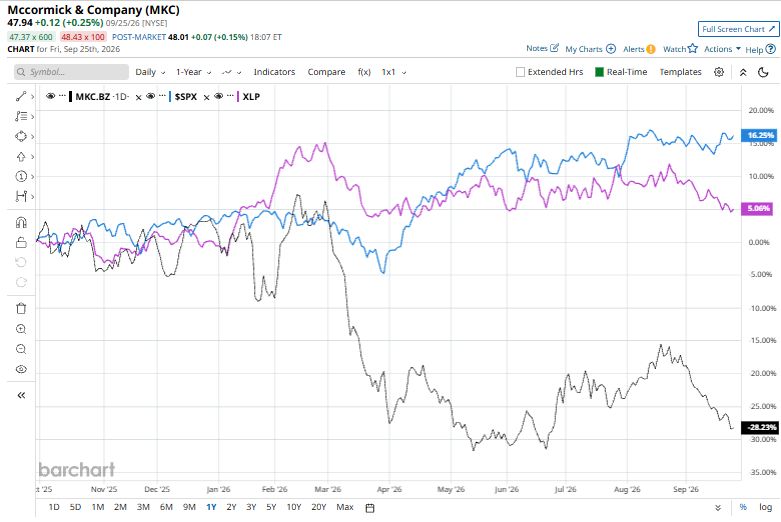
MKC stock has declined 25.8% over the past 52 weeks, substantially underperforming the S&P 500 Index ($SPX), which returned 17.2%, and the State Street Consumer Staples Select Sector SPDR ETF (XLP), which gained 5.5% over the same period.
 www.barchart.com
Slow growth and concerns over capital efficiency have weighed on McCormick’s performance, while its proposed Unilever PLC (UL) deal has added another layer of uncertainty. Sales have grown just 2.5% annually over the past three years, below the typical consumer staples company, while its 8.9% return on invested capital highlights challenges in identifying attractive investment opportunities. These factors have raised questions about the company’s ability to generate stronger growth and returns.
More recently, investor concerns have centered on McCormick’s proposed acquisition of Unilever's food business, particularly the higher leverage needed to fund the $15.7 billion cash payment. The transaction is expected to push leverage to about 4.0x EBITDA, raising concerns about the company’s post-deal balance sheet and execution risks.
Analysts remain somewhat bullish on MKC, with the stock carrying a consensus “Strong Buy” rating. Among the 14 analysts covering the stock, six recommend a “Strong Buy,” one rates it a “Moderate Buy,” and seven suggest a “Hold.” Meanwhile, the average price target of $60.83 implies potential upside of 26.9% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
With AI Putting Cybersecurity in the Spotlight, Fortinet Stock Looks Hot at New All-Time Highs The AI Fear That Crushed Accenture Just Created Its Biggest Opportunity. Here’s What The Anthropic Partnership Means. While Everyone’s Debating Muse, Mark Zuckerberg Is Quietly Building a 4,300-Mile Cable Under the Ocean. Here’s What It’s For. HP Stock Slips as PC Maker Warns of Industry Decline in 2027