

CoreWeave (CRWV) has had a lot going on lately. The company recently became the first AI cloud provider to put multi-rack clusters using Nvidia (NVDA)’s Vera Rubin NVL72 systems into customer production. These setups link hundreds of Rubin GPUs together, and no other neocloud provider has publicly announced a similar deployment. CoreWeave also signed more than $25 billion in net new customer commitments early in the third quarter. That adds to its $104.2 billion revenue backlog as of June 30, up 246% from a year earlier.
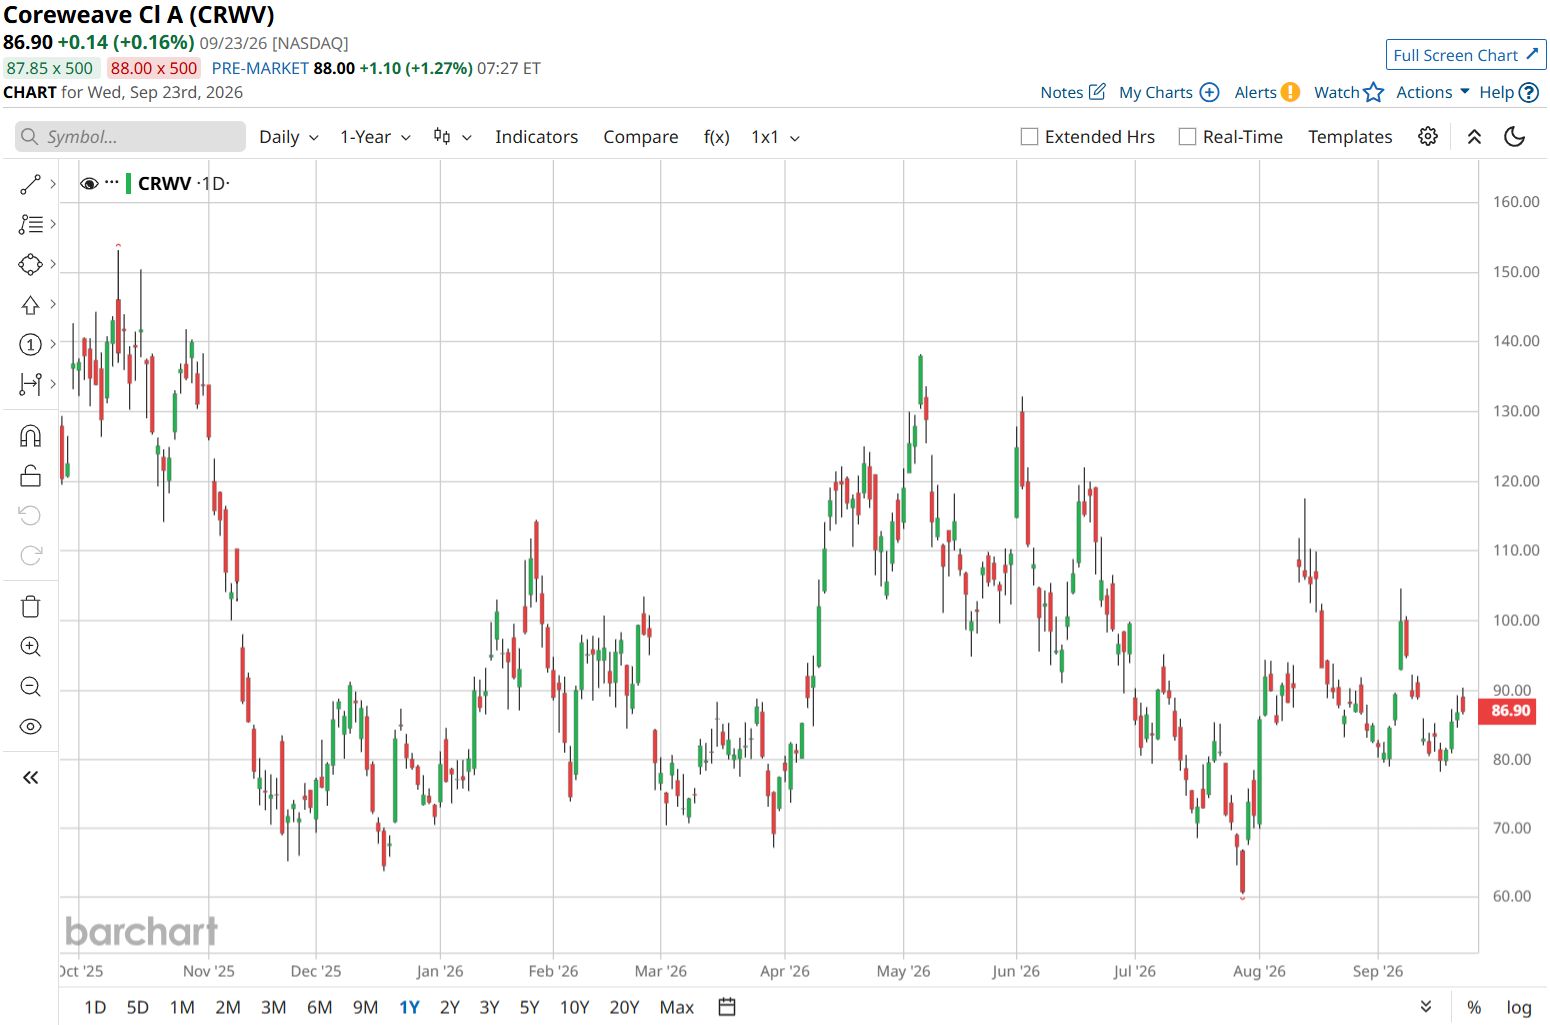
Still, investors have been cautious. CRWV shares are down about 17.80% over the past three months and trade near $87, though they remain up 21.35% so far this year.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
The big concern is how much CoreWeave must spend to keep expanding. Management raised its 2026 capital expenditure outlook to $35 billion to $39 billion, then last week priced a larger-than-planned $3.7 billion convertible-note offering and set up an at-the-market program for up to 35 million Class A shares.
That is the debate UBS stepped into this week. The Swiss bank started coverage of CoreWeave with a Buy rating, backing the upside case even as investors worry about the bill for growth. So, what does UBS see in CRWV that others may be missing? Let’s take a closer look.
Inside UBS's Buy Call on CRWV
On Sept. 23, UBS analyst Karl Keirstead started coverage of CoreWeave with a $120 price target, which was about 40% above where the stock was trading at the time. Shares rose about 0.9% before the market opened and nearly 2% during the session. UBS called the rating a “non-consensus positive call,” meaning the bank sees more upside than much of Wall Street does. Its main point is simple: demand for AI computing power remains strong and is spreading beyond a small group of major AI developers to more businesses.
UBS also thinks the market is not giving CoreWeave enough credit for that demand. The bank expects the company’s revenue per gigawatt of capacity to rise over time, while CRWV trades at roughly 3 times estimated 2027 revenue. In UBS’s view, that is a low valuation for a company with CoreWeave’s growth outlook.
Keirstead expects CoreWeave’s revenue per gigawatt to climb from about $11 billion today to more than $15 billion over time. He points to steady customer demand and better pricing for graphics-processing-unit capacity as the main drivers. UBS based its target on 3.8 times estimated 2028 sales, effectively betting that investors will become more willing to pay up for CoreWeave’s growth.
CoreWeave's Numbers Behind the Rally
CoreWeave’s second quarter showed that customer demand is still strong. Revenue came in at $2.6 billion, up 112% from a year earlier. Its revenue backlog reached $104.2 billion as of June 30, up 246% year over year. That number does not include the more than $25 billion in new customer commitments signed early in the third quarter. Based on that demand, CoreWeave raised its 2026 revenue outlook to $12.4 billion to $13.2 billion and expects adjusted operating income of $960 million to $1.15 billion. For the third quarter, it expects revenue of $3.4 billion to $3.6 billion. Adjusted EBITDA also nearly doubled to $1.5 billion, though the company still posted losses of $1.14 per share as it continues spending heavily on new capacity.
That spending is tied to long-term customer deals and new infrastructure. Meta Platforms (META) expanded its relationship with CoreWeave through a new $21 billion commitment. The agreement is built on an earlier $14.2 billion deal and runs through December 2032, taking Meta Platforms’ total commitments to roughly $35.2 billion. CoreWeave was also the first AI cloud provider to put Nvidia’s Vera Rubin NVL72 system into service. Nvidia's $2 billion investment earlier this year added further support, as CoreWeave raised more than $10 billion through unsecured debt and convertible bonds during the second quarter to fund the expansion.
Wall Street's Verdict on CRWV's Future
CoreWeave is set to report its next earnings on Nov. 9, 2026, and expectations are not pretty. Analysts see a loss of $1.57 per share for the September 2026 quarter, compared with a $0.31 loss a year ago — a drop of about 406.45%. The full-year view is rough too. For 2026, analysts project a loss of $5.19 per share, versus $2.69 last year, a 92.94% decline.
The bearish case got louder just a day before UBS made its call. Rothschild & Redburn started coverage with a Sell rating and a $54 price target, which implies about 34% downside from the prior close. Analyst Alex Haissl said the problem is leasing economics, not demand, warning that "credit markets are beginning to price risks that equities largely ignore." He pointed to falling GPU rental prices, big cloud companies building their own hardware, and rising financing costs eating into returns on CoreWeave's debt-heavy model.
Jefferies Financial Group is sticking with the bulls. The firm kept its Buy rating and $150 price target, arguing that better unit economics and clearer demand visibility matter more than near-term worries. It also noted that newer contracts are coming with stronger economics, thanks to better pricing, a more differentiated platform, and more efficient infrastructure.
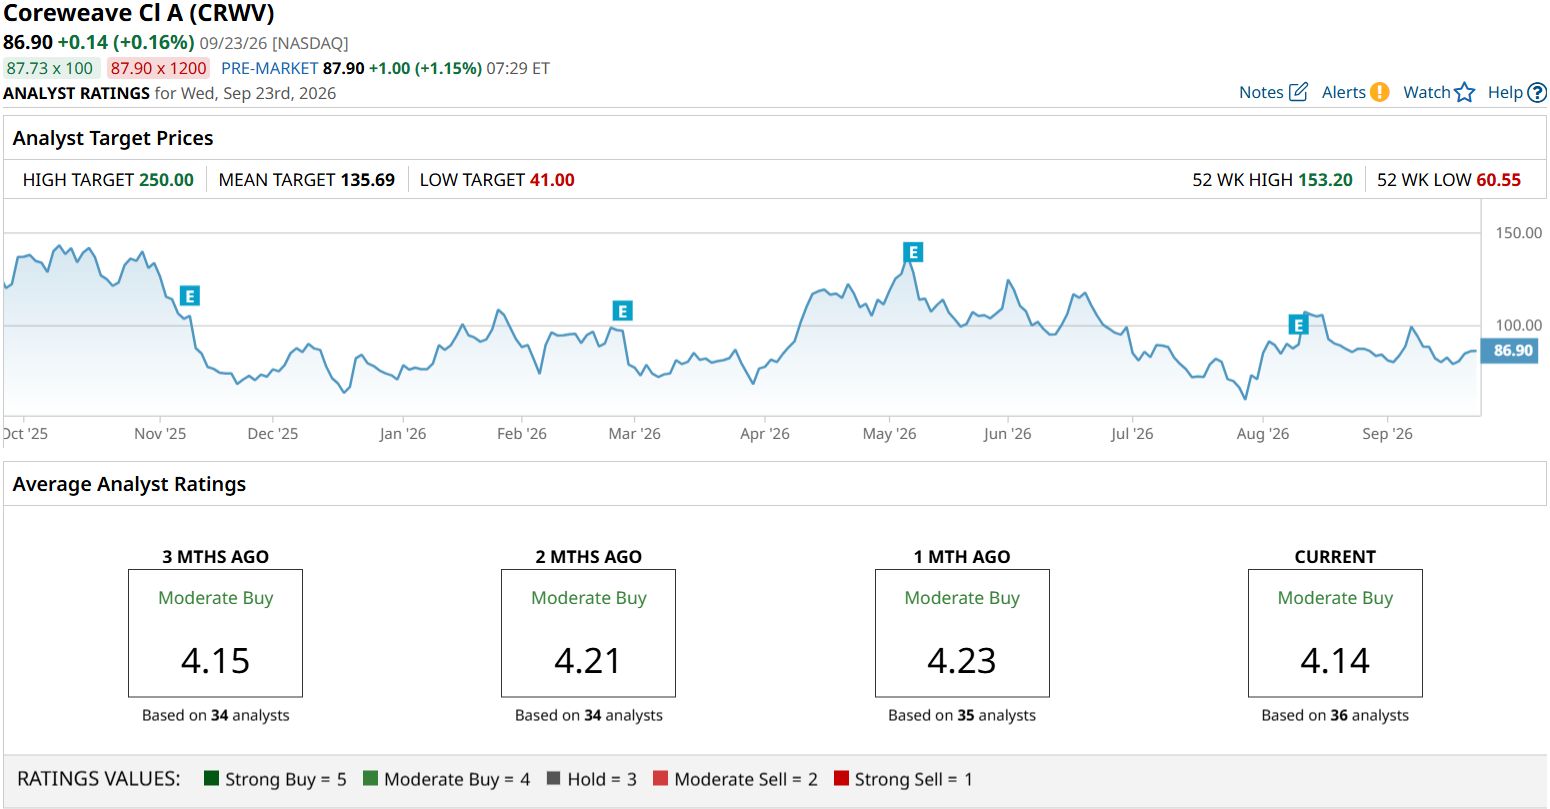
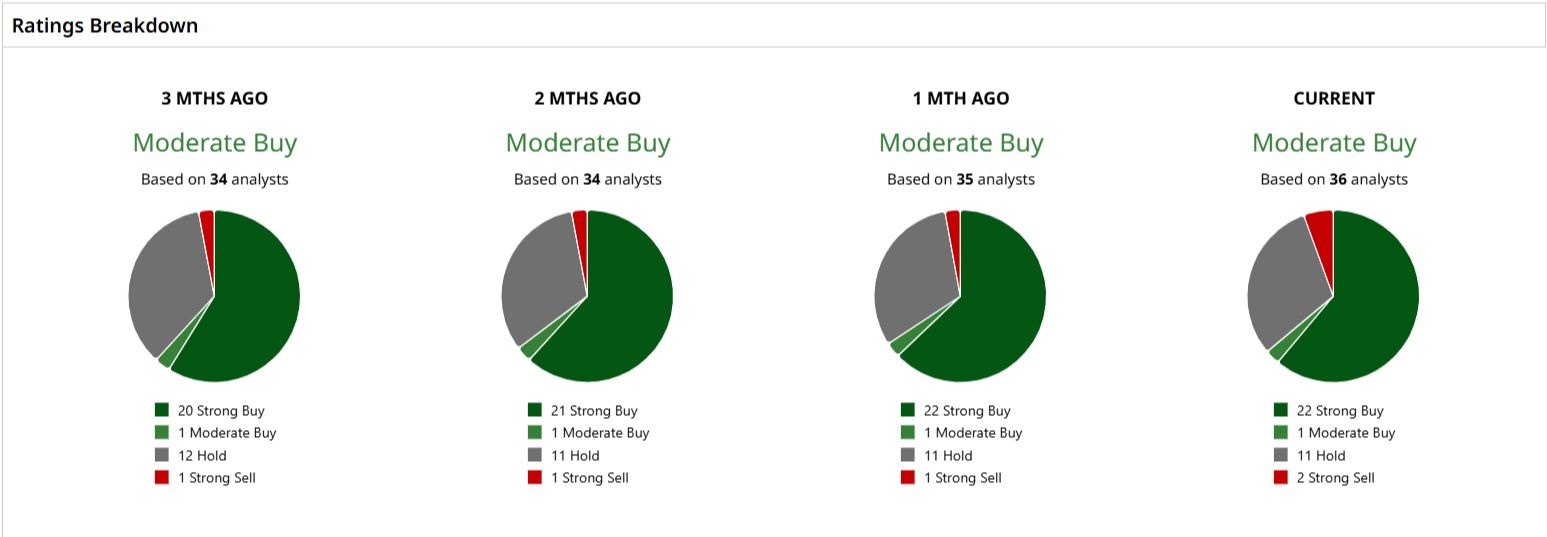
Overall, Wall Street still leans positive. All 36 analysts covering the stock rate CRWV a consensus "Moderate Buy," with an average price target of $135.69. From CoreWeave's current price levels, that implies roughly 56.14% potential upside.
 www.barchart.com
 www.barchart.com
Conclusion
So, is UBS right on CoreWeave? The evidence leans that way. Demand is real, the backlog keeps growing, Meta and Nvidia are doubling down, and a 3x revenue multiple is cheap for a company posting triple-digit growth. The pushback from Rothschild is fair, though. Rising financing costs and GPU pricing pressure are genuine risks, not noise. Still, with Wall Street's average target sitting near $135.69 and catalysts stacking up, CRWV looks more likely to grind higher than lower over the next several months, especially if the November earnings show newer contracts delivering better economics. Don’t expect a smooth ride, but the path of least resistance appears to be up.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Cadence Strengthens Its Partnership With TSMC, Here's What It Could Mean for AI Stocks Citi Raises Estimates for Micron Ahead of Earnings. How to Play MU Stock Now. Options Action: Naked Put Trade Ideas for this Week UBS Started Coverage of CoreWeave With a ‘Buy’ Rating. What This Means for CRWV Stock.