

With a market cap of $25.3 billion, W. R. Berkley Corporation (WRB) is a leading insurance holding company and one of the largest commercial lines insurers in the United States, with operations worldwide. The company operates through two property casualty segments: Insurance and Reinsurance & Monoline Excess.
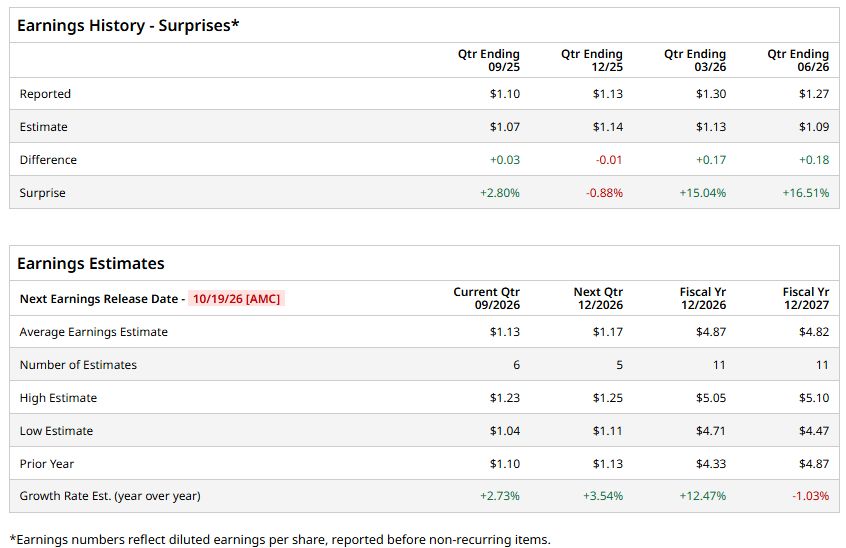
The Greenwich, Connecticut-based company is set to release its fiscal Q3 2026 results after the market closes on Monday, Oct. 19. Ahead of this event, analysts expect the company to report an EPS of $1.13, up 2.7% from $1.10 in the prior year's quarter. It has surpassed Wall Street's bottom-line estimates in three of the past four quarters while missing on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts forecast the property and casualty insurance firm to post EPS of $4.87, reflecting a 12.5% increase from $4.33 in fiscal 2025.
 www.barchart.com
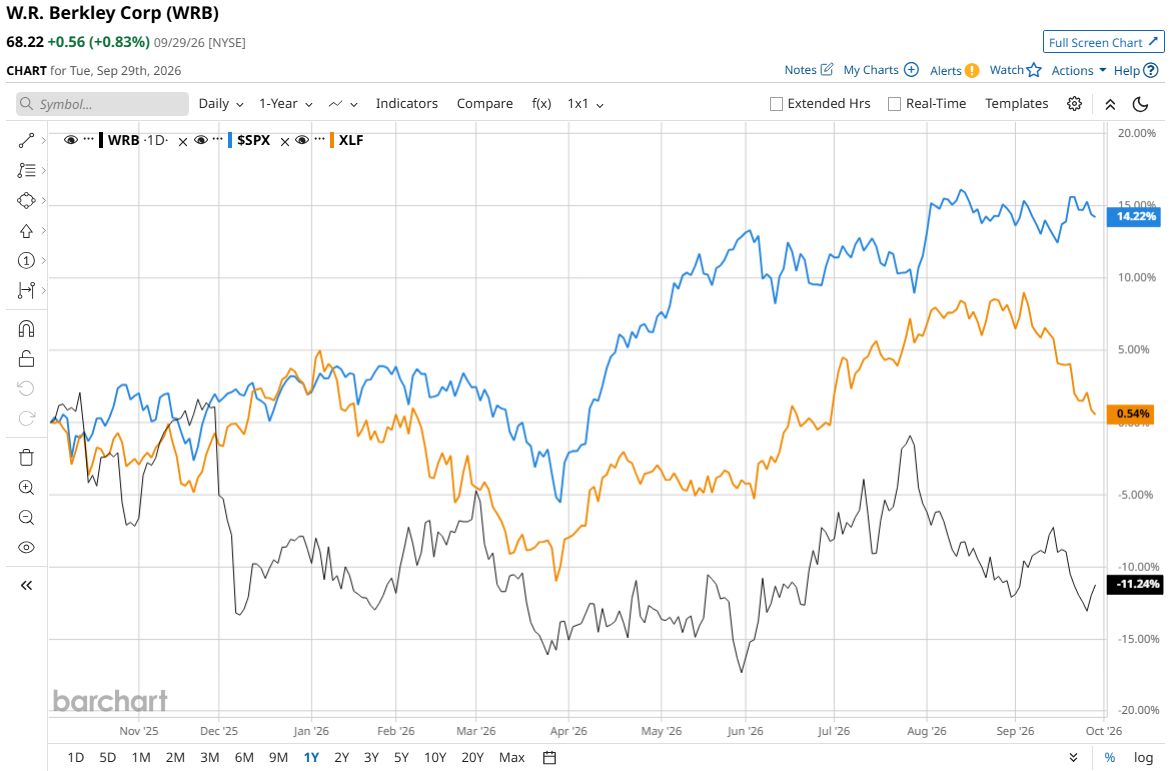
Shares of W. R. Berkley have fallen 10.3% over the past 52 weeks, lagging behind the S&P 500 Index's ($SPX) 15.2% gain and the State Street Financial Select Sector SPDR ETF's (XLF) marginal decline over the period.
 www.barchart.com
Despite Q2 2026 operating income rising to $1.27 per share and beating the consensus on Jul. 20, W. R. Berkley shares fell marginally the next day as revenue of $3.72 billion came in below the estimate. The revenue shortfall was primarily due to a $55.13 million loss on investments and net premiums earned of $3.19 billion also narrowly missed the consensus.
Investor sentiment was further weighed by weaker Reinsurance & Monoline Excess premiums of $361.36 million and a wider Corporate & Eliminations pretax loss of $148.88 million, despite net investment income rising to $418.71 million.
Analysts' consensus view on WRB stock is cautiously optimistic, with an overall “Hold” rating. Among 20 analysts covering the stock, two recommend "Strong Buy," 11 suggest "Hold," one has a "Moderate Sell," and six indicate “Strong Sell.” The average analyst price target of $69.72 is a premium of 2.2% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
SpaceX Could Double the Number of Nvidia Chips It Uses in Colossus 2. What This Would Mean for SPCX Stock. What a Revamped Copilot Means for Microsoft Stock A $60 Billion Amazon Opportunity Is Changing Qualcomm's Chip Story Elon Musk’s Potential Colossus 2 Expansion Sends Strong Signal on Nvidia Demand