

Newmont Corporation (NEM), headquartered in Denver, Colorado, acquires, explores, and develops mineral properties. Valued at $121.5 billion by market cap, the company produces and markets gold, copper, silver, zinc, and lead. The world’s leading gold company is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Thursday, Oct. 22.
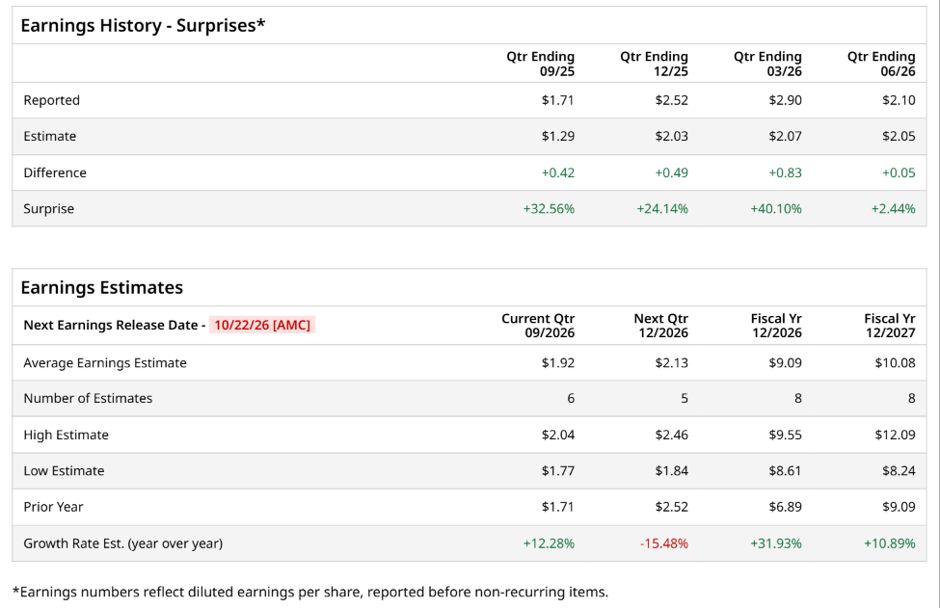
Ahead of the event, analysts expect NEM to report a profit of $1.92 per share on a diluted basis, up 12.3% from $1.71 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
For the full year, analysts expect NEM to report EPS of $9.09, up 31.9% from $6.89 in fiscal 2025. Its EPS is expected to rise 10.9% year over year to $10.08 in fiscal 2027.
 www.barchart.com
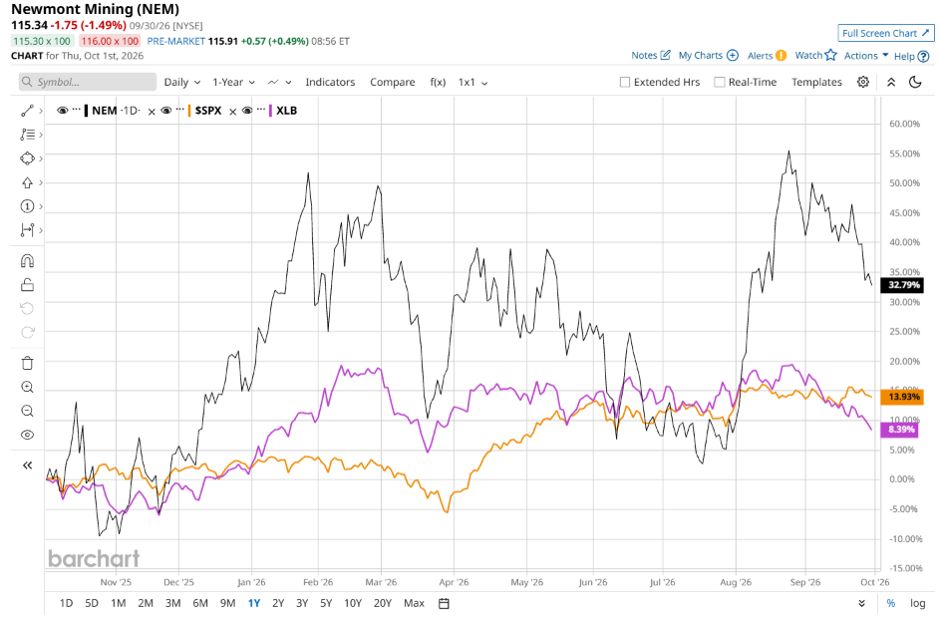
NEM stock has outperformed the S&P 500 Index’s ($SPX) 14% gains over the past 52 weeks, with shares up 35.2% during this period. Similarly, it outperformed the State Street Materials Select Sector SPDR ETF’s (XLB) 8.7% returns over the same time frame.
 www.barchart.com
NEM’s stock outperformance has been driven primarily by record high gold prices, robust operational execution following the integration of its Newcrest acquisition, and significant expansion in free cash flow generation. As the world’s largest gold producer, Newmont benefited immensely from strong macroeconomic tailwinds, including elevated central bank buying and safe-haven demand, which widened its realized metal margins and offset sector-wide labor and energy cost pressures. Furthermore, aggressive portfolio rationalization through non-core asset sales allowed the company to pay down debt, fund expanded share buybacks, and boost capital returns to shareholders. Supported by steady production volumes across its Tier-1 assets, this operational leverage directly converted commodity price strength into robust earnings and multiple expansion.
Analysts’ consensus opinion on NEM stock is bullish, with a “Strong Buy” rating overall. Out of 24 analysts covering the stock, 19 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” and three give a “Hold.” NEM’s average analyst price target is $138.20, indicating a potential upside of 19.8% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Nvidia to Sell Twice as Many Chips as This Next Year’: But Jensen Huang’s Comments Ignore the Market Share Question Why Bank of America Is Betting That Nike Stock Will Fall from Here Netflix’s Problem Isn’t Subscribers, It’s Losing the Attention War This Lesser-Known Stock Eyes a $1.4 Billion Cut in Historic Apple Verdict