

Netflix (NFLX) co-CEO Ted Sarandos, speaking at Bloomberg's Screentime conference in Los Angeles on Wednesday, said the streaming giant is not growing as fast as he wants. He later clarified that the business is healthy and growing fine.
Sarandos noted Netflix spends about 5% of its $20 billion annual content budget on live programming, which drives roughly 1% of viewership but generates plenty of signups and helps reduce churn. He also brushed off regret over Netflix's brief winning bid for Warner Bros. Discovery (WBD) and downplayed its YouTube creator deals as a strategy shift.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
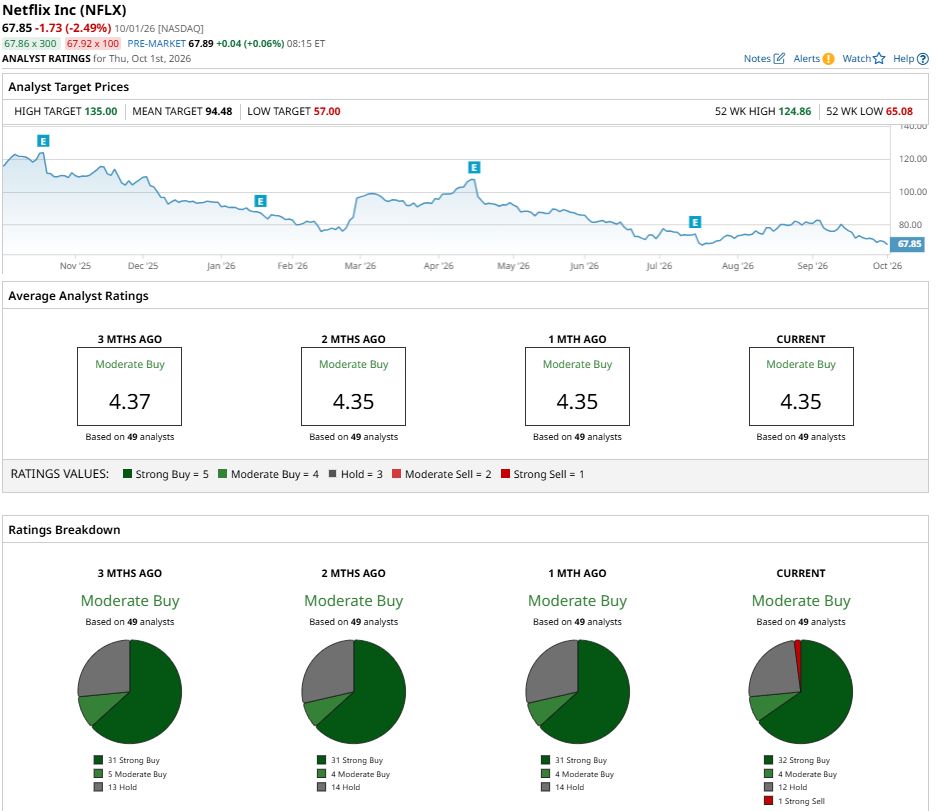
Analysts remain split on NFLX stock: HSBC downgraded it to Hold with a $76 price target, Wells Fargo cut it to Underweight with a $57 target, and Deutsche Bank upgraded it to Buy with a $95 target.
About NFLX Stock
Netflix, based in Los Gatos, California, is the world's leading streaming entertainment company, offering TV series, films, documentaries, games, and live programming. With more than 325 million paid memberships, a fast-growing ad-supported tier, and a market capitalization near $293 billion, Netflix remains a heavyweight in the communication services sector.
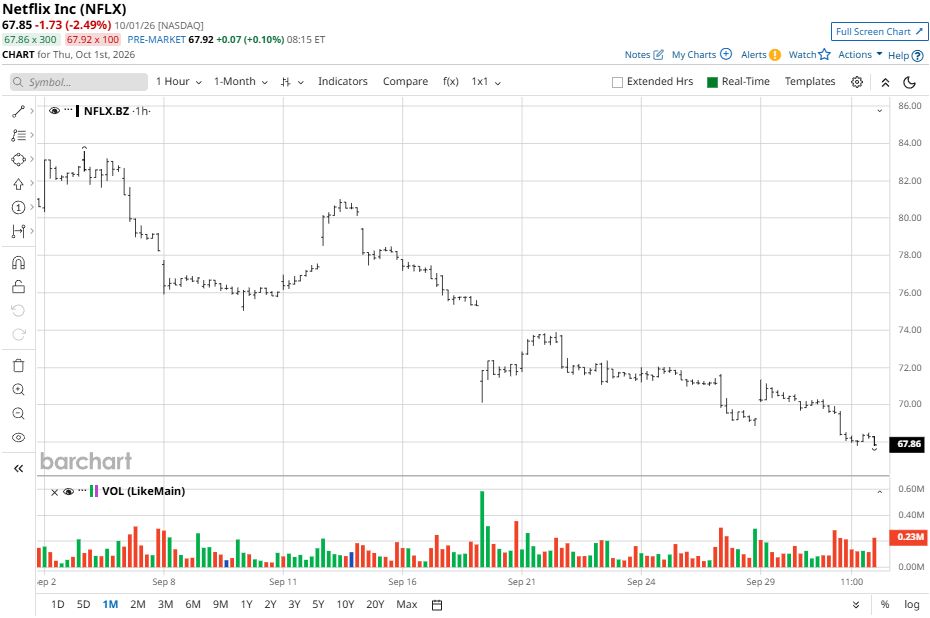
Its stock has had a punishing 2026. Shares closed at $67.85 on October 1, not far above the 52-week low of $65.08 set in July, and have lost roughly a quarter of their value this year. The stock slid more than 7% after its second-quarter report, and analysts have flagged slowing engagement and rising YouTube competition.
Over the past 52 weeks, Netflix has tumbled about 41.6%, sharply trailing the S&P 500's (SPY) 15.2% gain and the 6.1% decline in the Communication Services sector, as tracked by the State Street Communication Services Select Sector SPDR ETF (XLC). That wide gap suggests the weakness is stock-specific rather than sector-wide, leaving NFLX a notable laggard among large-cap communication names.
 www.barchart.com
Netflix Q2 2026 Earnings Results
Netflix reported second-quarter 2026 revenue of $12.56 billion, up 13.4% year over year, landing a hair below the $12.58 billion Wall Street expected. Earnings per share came in at $0.80, edging past the $0.79 analyst estimate, and rising 11% from $0.72 a year earlier, while net income reached $3.4 billion. Overall, the quarter was broadly in line with expectations.
Operating income rose 11% to $4.2 billion, but operating margin slipped to 33.4% from 34.1% as content amortization growth ran higher in the first half. Free cash flow fell to $1.5 billion from $2.3 billion a year ago, with operating cash flow at $1.7 billion versus $2.4 billion. Management expects content amortization growth to slow in the second half, rising about 10% for 2026.
For the third quarter, Netflix guided to revenue growth of 12%, or about $12.86 billion, below analyst estimates, with an operating margin of 33.2% versus 28.2% a year ago. The company narrowed its 2026 revenue forecast to $51.0 billion to $51.4 billion, held its 31.5% operating margin target, and expects advertising revenue to roughly double to about $3 billion. Free cash flow is still projected near $12.5 billion. Investors will get a fresh read when Netflix reports third-quarter results on Oct. 20.
Should You Buy NFLX?
Netflix's own leadership has admitted growth is not moving as fast as desired, and the stock's slide shows investors have noticed. Still, Wall Street remains largely optimistic. Among 49 analysts covering NFLX, 32 rate it a “Strong Buy,” four a “Moderate Buy,” 12 a “Hold,” and just one a “Strong Sell,” producing a consensus “Moderate Buy” rating. The mean price target of $94.48 implies roughly 40% upside from current levels. For long-term investors, live programming and advertising could speed growth, but the Oct. 20 earnings report may decide whether NFLX deserves a spot in your portfolio.
 www.barchart.com
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Carnival Corp Generates Strong Free Cash Flow - What's the Best CCL Play Analyst Sees 6 Million iPhone Duo Sales This Year. Why That’s Not Enough to Move AAPL Stock. Netflix’s Own Co-CEO Just Warned of Slowing Growth Meta vs. Microsoft: One AI Agent Has a Problem the Other Doesn’t.