

Santa Clara, California-based Intel Corporation (INTC) designs, develops, manufactures, markets, sells, and services computing and related end products and services in the United States and internationally. The company has a market cap of $601.9 billion and operates through three segments: CCG, DCAI, and Intel Foundry, and offers client computing group products, including client and commercial CPUs, discrete client GPUs, edge computing, and connectivity products.
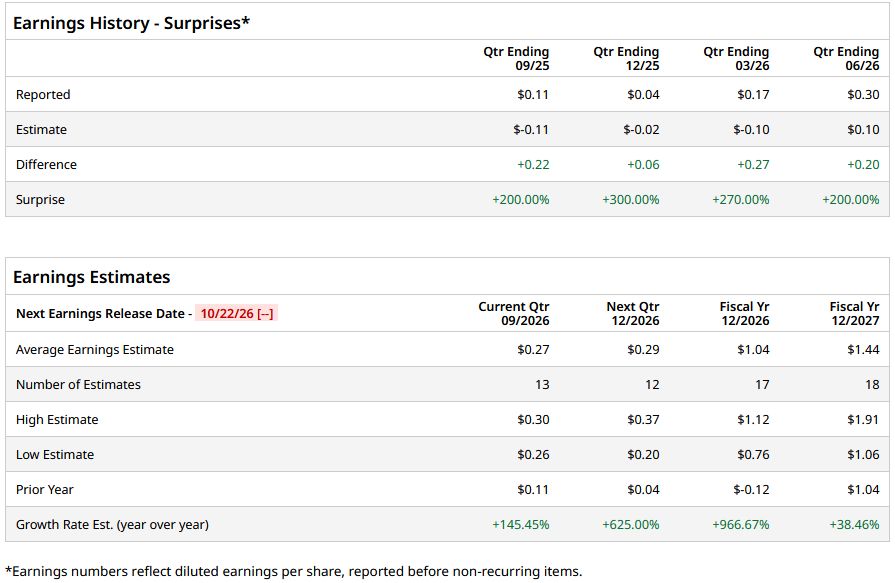
INTC is expected to release its Q3 2026 earnings soon. Ahead of this event, analysts anticipate the company will generate earnings of $0.27 per share, representing an increase of 145.5% from $0.11 per share reported in the same quarter last year. The company has surpassed the Street’s bottom-line estimates in each of the past four quarters, which is impressive.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect the company to report an EPS of $1.04, indicating a 966.7% rise from a loss per share of $0.12 reported in fiscal 2025. Moreover, its EPS is expected to rise nearly 38.5% year over year (YoY) to $1.44 in fiscal 2027.
 www.barchart.com
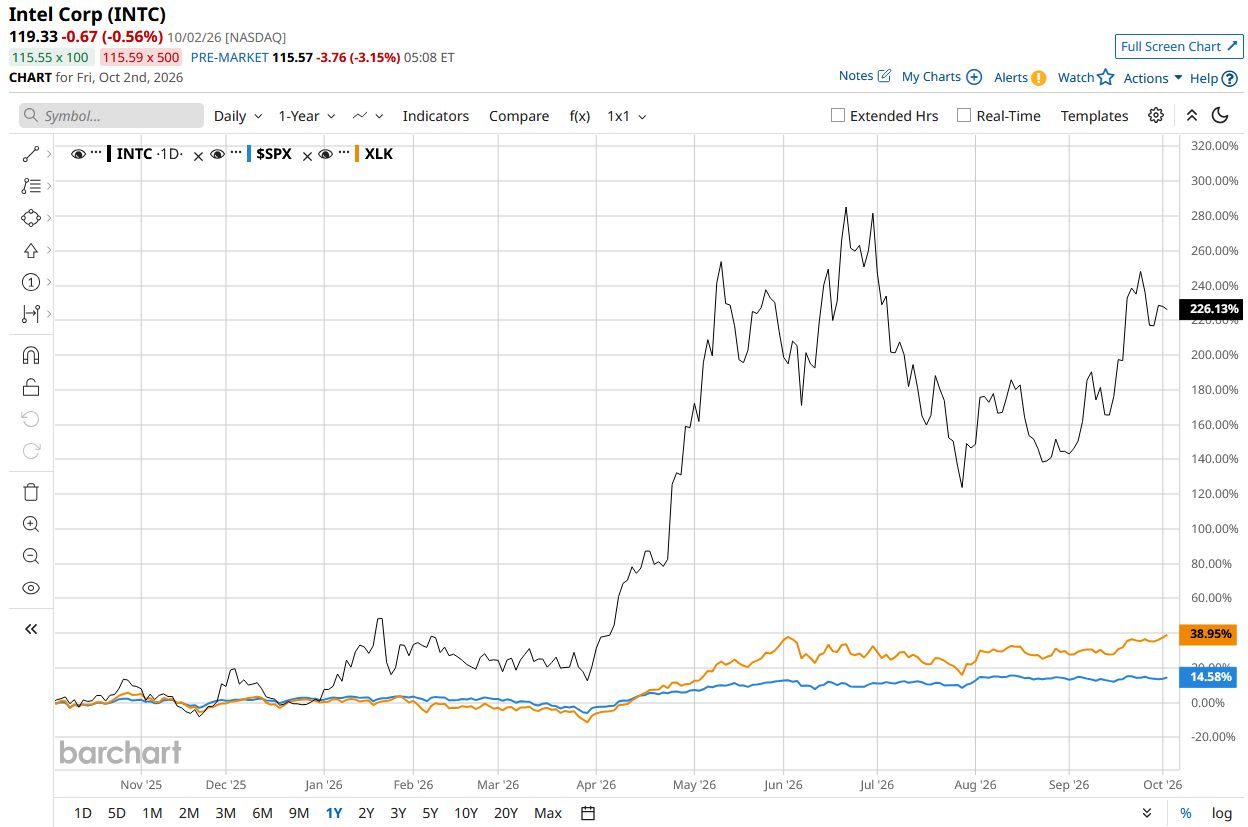
INTC stock has surged 219.2% over the past 52 weeks, outperforming the S&P 500 Index’s ($SPX) 15% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 39.7% rise during the same time frame.
 www.barchart.com
On July 23, INTC delivered better-than-expected Q2 2026 earnings. The company’s revenue for the quarter rose 25.4% from the prior year’s quarter to $16.1 billion and surpassed the Street’s forecasts. Additionally, its adjusted EPS came in at $0.42, beating Wall Street’s estimates by a wide margin. The company raised its 2026 capital expenditure forecast to $20 billion from $18 billion, driven by booming AI-related CPU demand, as well. INTC expects revenue in the range of $15.8 billion to $16.8 billion for the fiscal third quarter and its EPS to be $0.38.
Analysts’ consensus opinion on the stock is moderately bullish, with a “Moderate Buy” rating overall. Of the 46 analysts covering the stock, 12 recommend a “Strong Buy,” one recommends a “Moderate Buy,” 31 suggest a “Hold,” and the remaining two rate it a “Strong Sell.” INTC’s average analyst price target is $115.03, which is below the current price level. However, its Street-high price target of $200 offers a 67.6% upside potential.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.