

PG&E Corporation (PCG), based in Oakland, California, with a market capitalization of approximately $33 billion, operates through Pacific Gas and Electric Company, generating, transmitting, distributing and selling electricity and natural gas across Northern and Central California. The company serves residential, commercial, industrial, agricultural and power generation customers through its extensive energy infrastructure.
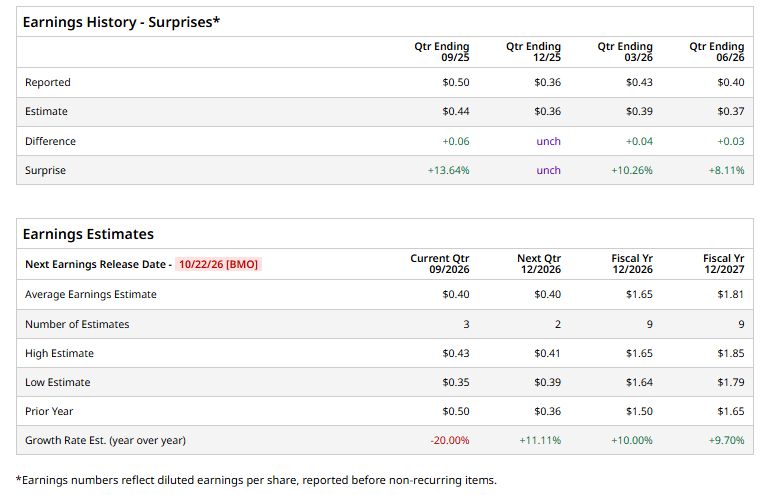
PCG is set to report its Q3 earnings on Thursday, October 22, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of 40 cents, down 20% from 50 cents in the year-ago quarter. That said, PCG has met or exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts expect PCG to report EPS of $1.65, up 10% from $1.50 in fiscal 2025. Moreover, PCG’s EPS is projected to grow another 9.7% year over year to $1.81 in fiscal 2027.
 www.barchart.com
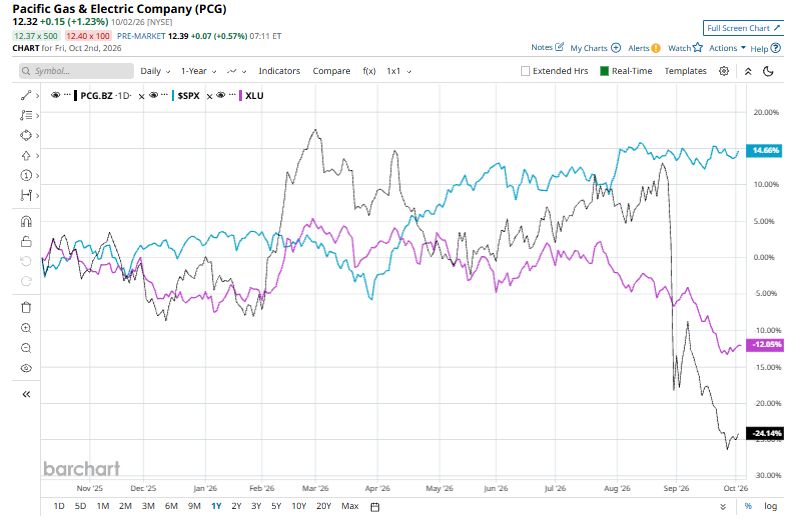
PCG stock has declined 21.2% over the past 52 weeks, substantially underperforming the S&P 500 Index ($SPX), which gained 15%, and the State Street Utilities Select Sector SPDR ETF (XLU), which fell 9.4% over the same period.
 www.barchart.com
PCG’s underperformance relative to the broader market may reflect ongoing regulatory, wildfire and financing pressures despite improving financial results. On July 23, 2026, PG&E reported second-quarter non-GAAP core EPS of 40 cents, up from 31 cents in the year-ago quarter. However, following the results, PCG shares plunged 3.2% as investors digested the earnings.
While higher rate base and net operating and maintenance savings supported earnings, a lower California Public Utilities Commission return on equity and higher Wildfire Fund expenses weighed on results. PG&E also reported $796 million in second-quarter interest expense, highlighting the financing burden associated with its capital-intensive business. Meanwhile, ongoing wildfire-related and regulatory costs remain key considerations for investors.
Analysts remain cautiously bullish on PCG, with the stock carrying a consensus "Moderate Buy" rating. Of the 18 analysts covering the stock, seven recommend a "Strong Buy," while 11 rate it a "Hold." Meanwhile, the average analyst price target of $18.44 implies potential upside of 49.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
NVO vs. LLY: Novo’s CEO Says Confidence Is Gone. Lilly Is Winning 7 in 10 New Seniors. Nvidia Bull Put Spread Could Return 16% U.S. Stock Futures Muted as Europe’s Turmoil Curbs Risk Appetite; Fed Minutes Awaited As Starship Finally Reaches Orbit, Here’s How You Should Place SpaceX Stock