

Healthcare and care services company UnitedHealth Group (UNH) will report its third-quarter results on Oct. 13, before the market opens. Ahead of the results, investors are looking to see whether the company can build on the robust results it reported in Q2, especially improvements in the medical cost ratio. Before announcing Q3 results, UnitedHealth is scaling back its Medicare Advantage business for next year, discontinuing plans covering about 390,000 members. The move, amid high medical costs, aims to further boost profitability.
Let's look into UNH a bit more deeply.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About UnitedHealth Stock
UnitedHealth Group is a diversified U.S. health care company headquartered in Eden Prairie, Minnesota. It operates through two main platforms: UnitedHealthcare, which provides health insurance and benefits to employers, individuals, and government programs such as Medicare and Medicaid; and Optum, which delivers health services including pharmacy care, data analytics, and physician practice management. The company has a market capitalization of $337.78 billion.
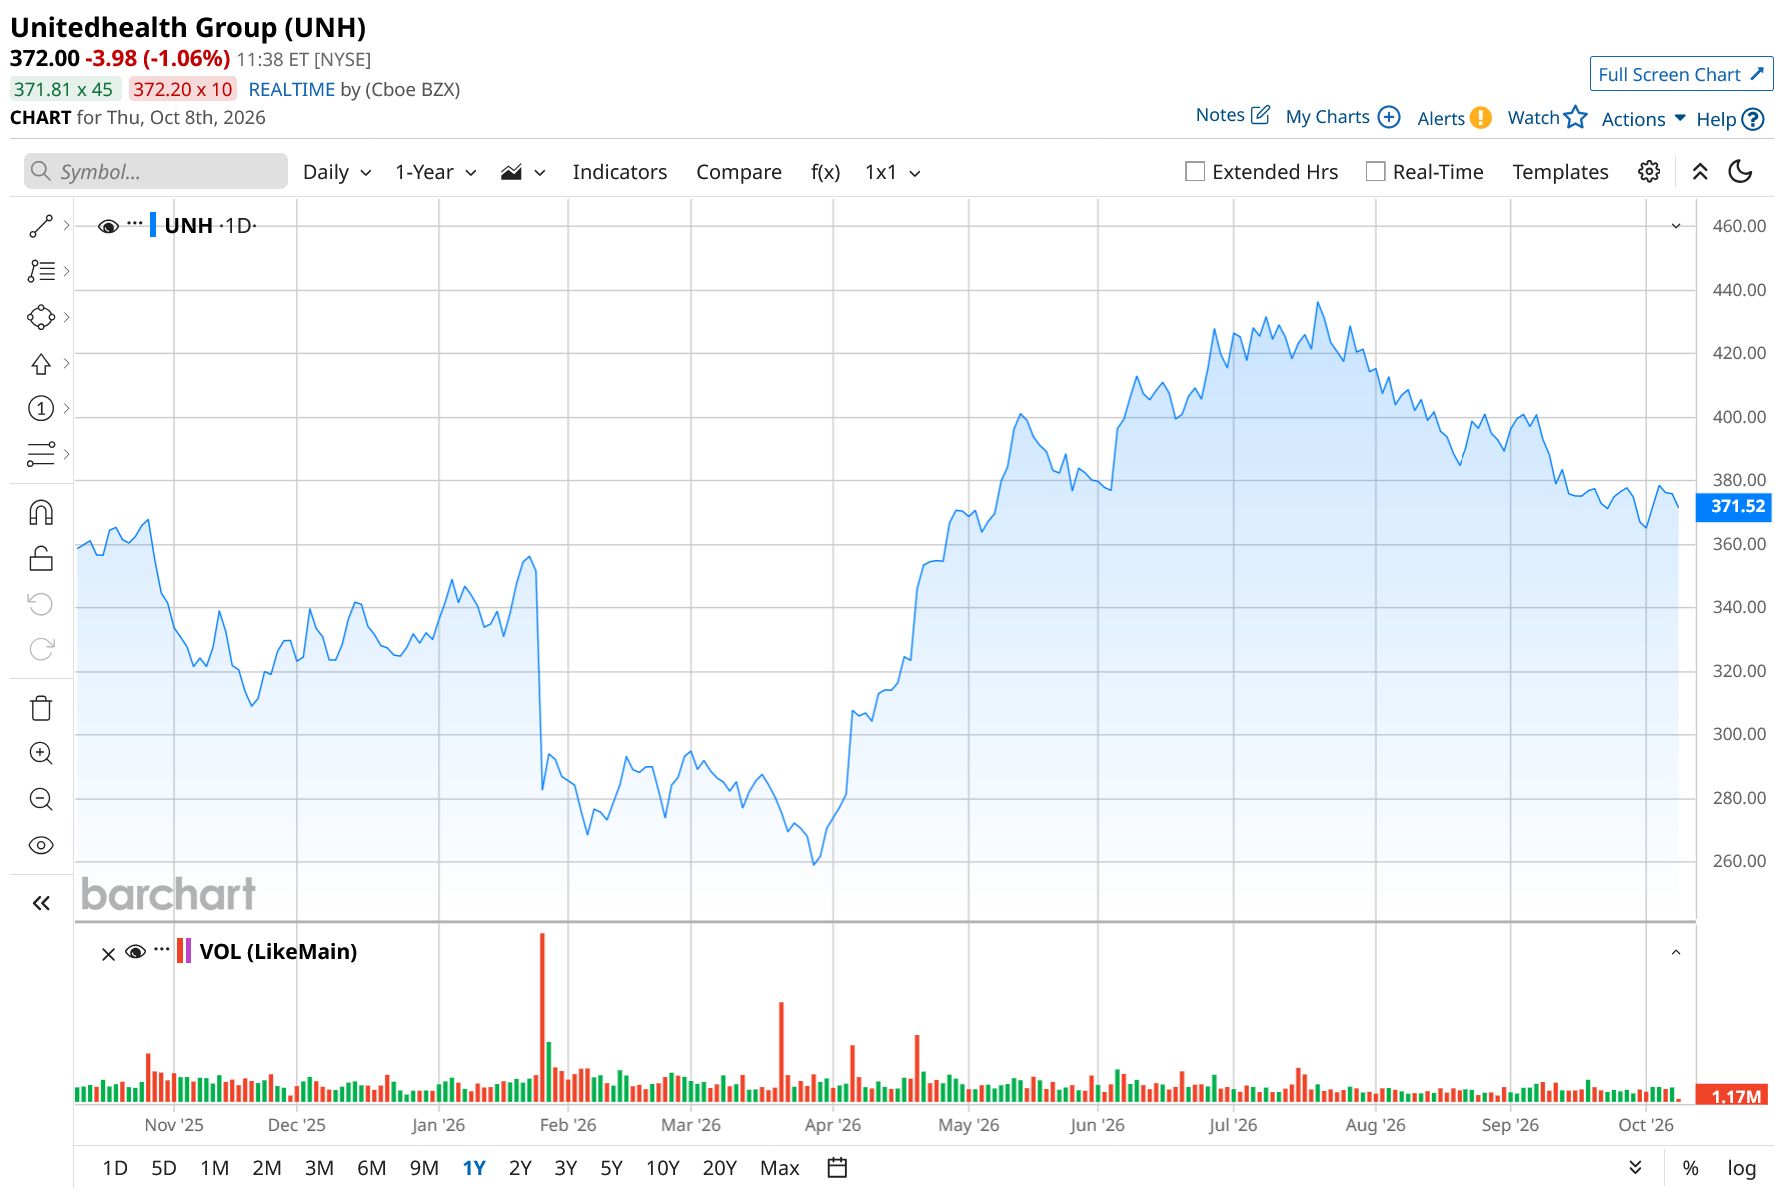
UnitedHealth’s stock is only up 0.18% over the past 52 weeks because a severe 2025 drawdown from elevated medical costs and Medicare Advantage pressure erased much of the prior gains. The 21% gain over the past six months reflects a sharp recovery from those 2025 lows as the company improved its medical loss ratio and raised 2026 earnings guidance, boosting investor confidence. It reached a 52-week high of $461.62 on July 16, but is down 20% from that level.
On a forward-adjusted basis, UnitedHealth’s price-to-earnings (non-GAAP) ratio of 18.94x is marginally higher than the industry average of 18.77x.
 www.barchart.com
UnitedHealth Q2 Earnings Beat Estimates as Medical Cost Ratio Improved
UnitedHealth has employed a broad set of reforms to improve transparency, affordability, and simplicity for the care providers it serves. So far, the reforms seem to be working based on the growth in results.
The company improved its medical cost ratio to 86.7% in the second quarter, reflecting its cost and pricing discipline and shifts in the mix across the company’s benefit offerings. Basically, the company recognized product design changes, improved medical management, and better-aligned pricing. Its operating cost ratio was 12.7% in the quarter, slightly higher than 12.3% a year earlier. This was because UnitedHealth made targeted investments in infrastructure, artificial intelligence (AI), and the consumer experience.
UnitedHealth’s total revenues increased marginally year-over-year (YoY) to $112.03 billion, higher than the $110.12 billion Wall Street analysts expected. The topline growth was partially offset by premium revenue dropping 1.1% YoY to $86.96 billion.
Driven by strong performance across both UnitedHealthcare and Optum, UnitedHealth’s adjusted EPS rose 56.4% from the prior-year period to $6.38, surpassing the $4.94 analysts expected. The company reduced its debt-to-capital ratio from 42.9% at the end of Q1 to 41.2% at the end of Q2. The company continues to target a long-term debt-to-capital ratio of approximately 40.0% by year-end.
For full-year 2026, UnitedHealth expects a medical care ratio of 88.1%, plus or minus 25 basis points. Its adjusted operating earnings are projected to exceed $25.22 billion, while adjusted EPS is expected to be in the $19.50-$20 range. Wall Street analysts are also optimistic about the company’s bottom-line trajectory. For fiscal 2026, UnitedHealth’s EPS is expected to climb 21.4% YoY to $19.85, followed by a 13.6% improvement to $22.54 in fiscal 2027. For the about-to-be-reported quarter, EPS is projected to rise 41.1% YoY to $4.12.
Here’s What Analysts Think About UNH Stock
In July, analysts at JPMorgan maintained UNH stock with an “Overweight” rating and raised the price target from $466 to $516. Mizuho analysts raised the price target from $470 to $493, while keeping an “Outperform” rating. In September, Barclays analyst Andrew Mok, CFA, maintained a “Buy” rating and a $441 price target.
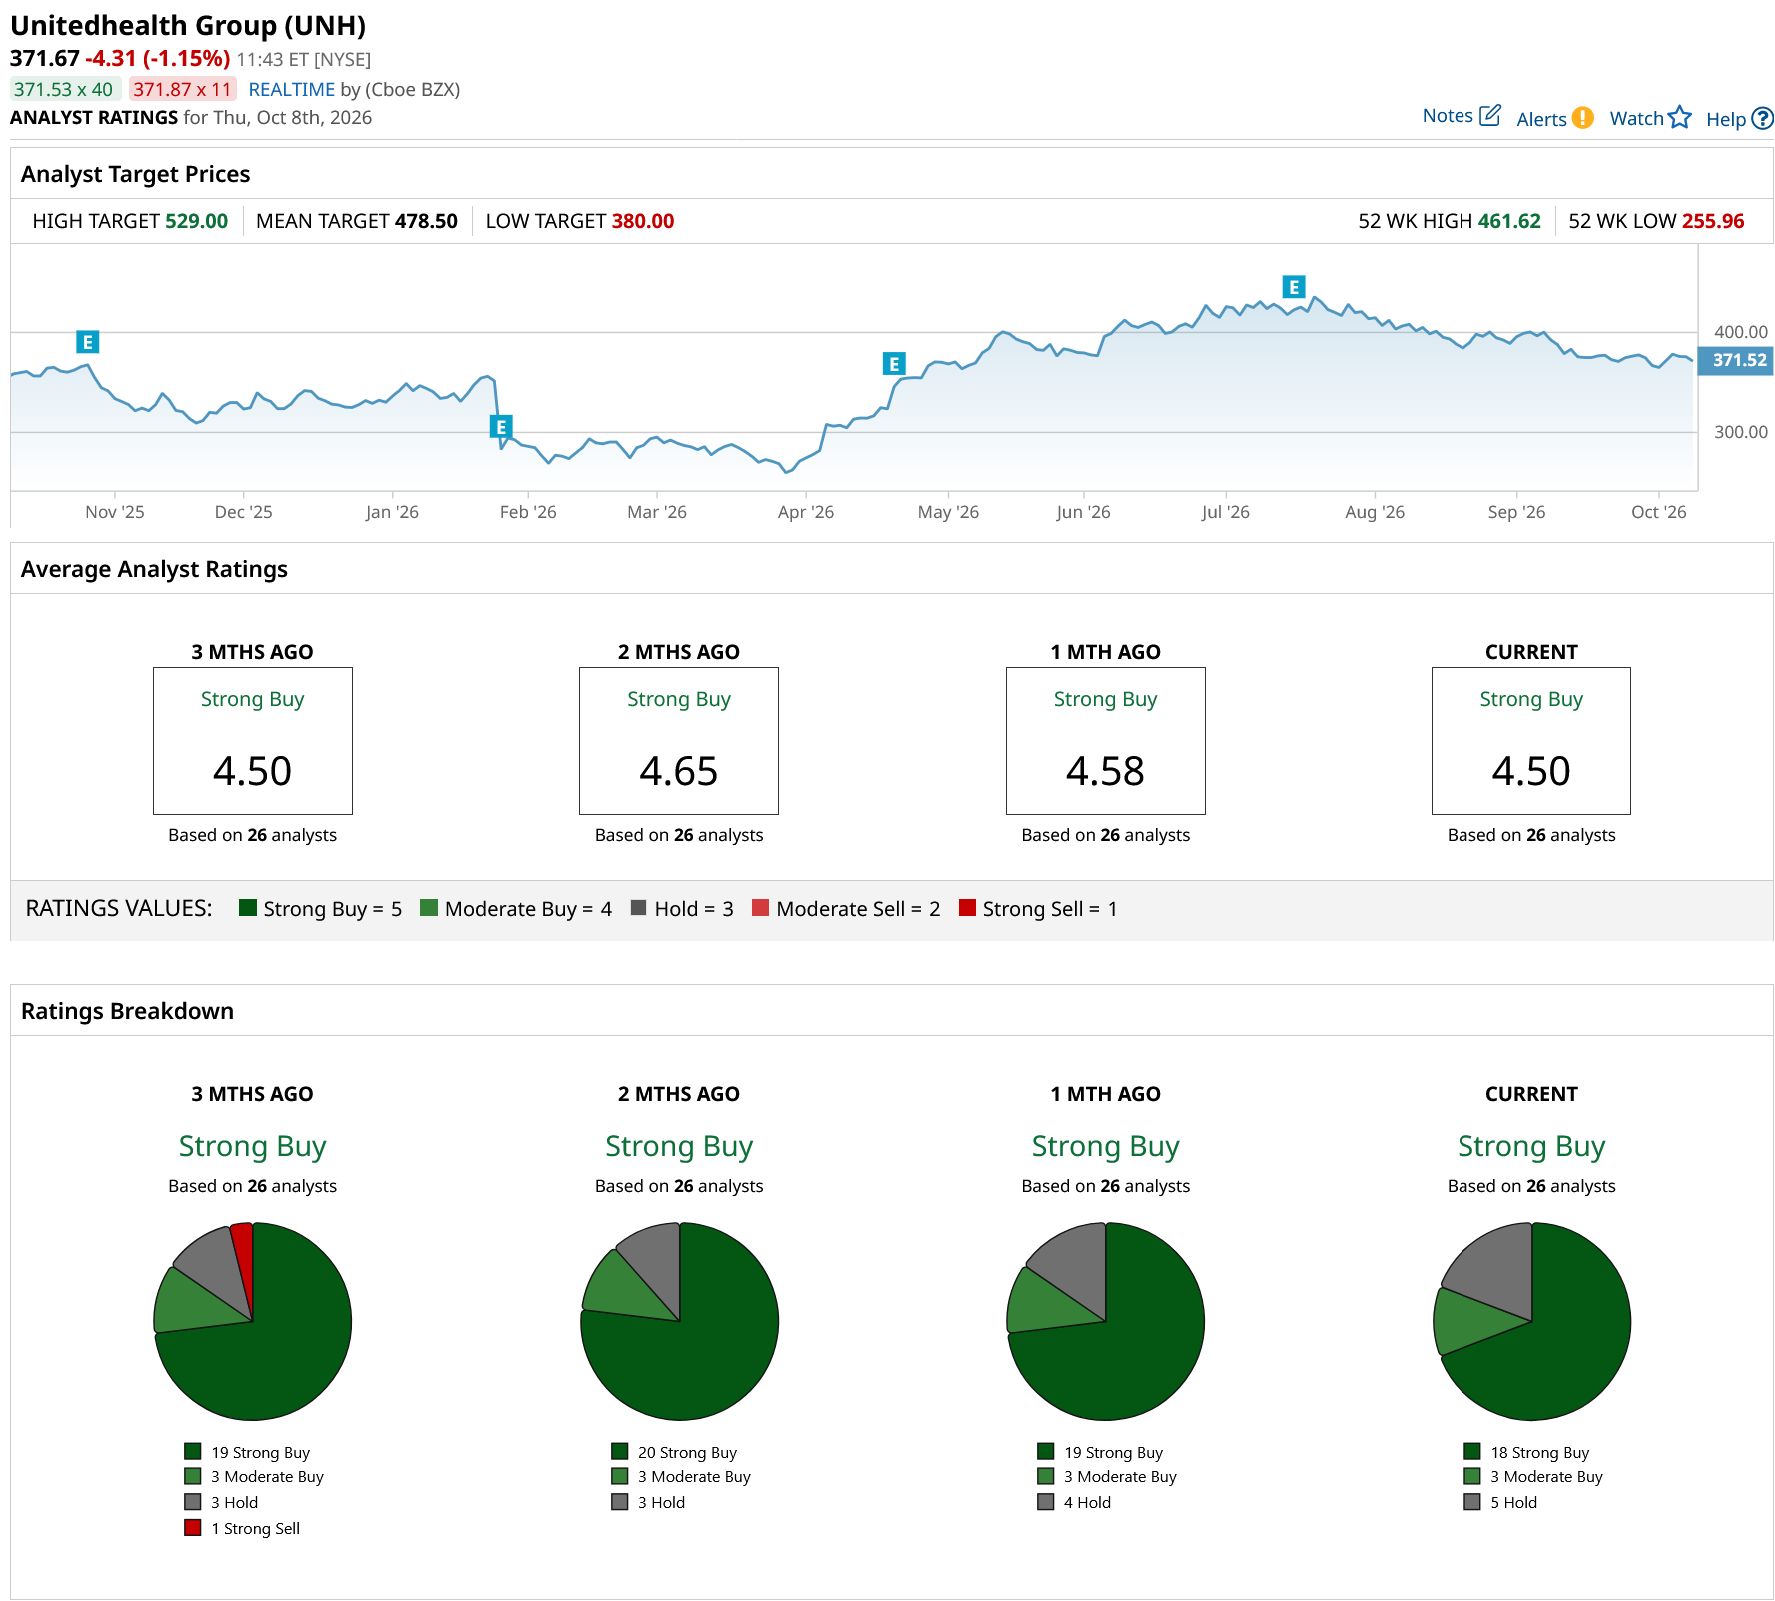
UnitedHealth remains a popular name on Wall Street, with analysts awarding it a consensus “Strong Buy” rating overall. Of the 26 analysts rating UNH stock, a majority of 18 analysts have given it a “Strong Buy” rating, three analysts rated it “Moderate Buy,” while five analysts are taking the middle-of-the-road approach with a “Hold” rating. The consensus price target of $478.50 represents a 29% upside from current levels. The Street-high price target of $529 reflects a 43% upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Following Tilray Earnings, Here's What Comes Next for TLRY Stock Dear UnitedHealth Stock Fans, Mark Your Calendars for October 13 ‘I Got Slaughtered’: Kevin O’Leary Says Shorting Yahoo Cut His Net Worth ‘40, 50%’ After ‘Losing 3, 4 Million An Hour’ So He ‘Never Ever Ever Shorted A Stock Again’ Novo Nordisk’s CEO Was Asked Why His Stock Keeps Falling on Good News: ‘The Stock Market Is Always Right, but With a Bit of a Time Difference’