

New York-based Coinbase Global, Inc. (COIN) operates a platform for crypto assets in the United States and internationally. The company has a market capitalization of $47.3 billion and provides the primary financial account in the crypto economy for consumers, a brokerage platform, and a suite of products that grant developers access to build on-chain. COIN is expected to release its Q3 2026 earnings soon.
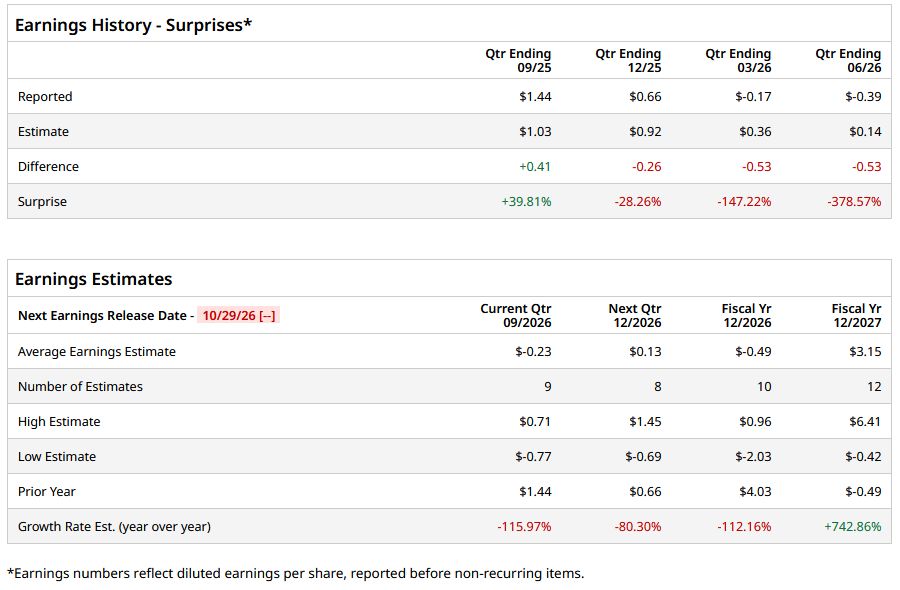
Ahead of the event, analysts expect the company’s loss per share to be $0.23 on a diluted basis, down 116% from $1.44 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in only one of its last four quarters, while missing on three occasions.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts project the company’s loss per share to be $0.49, down 112.2% from $4.03 in fiscal 2025. However, its EPS is expected to rise by roughly 742.9% year over year (YoY) to $3.15 in fiscal 2027.
 www.barchart.com
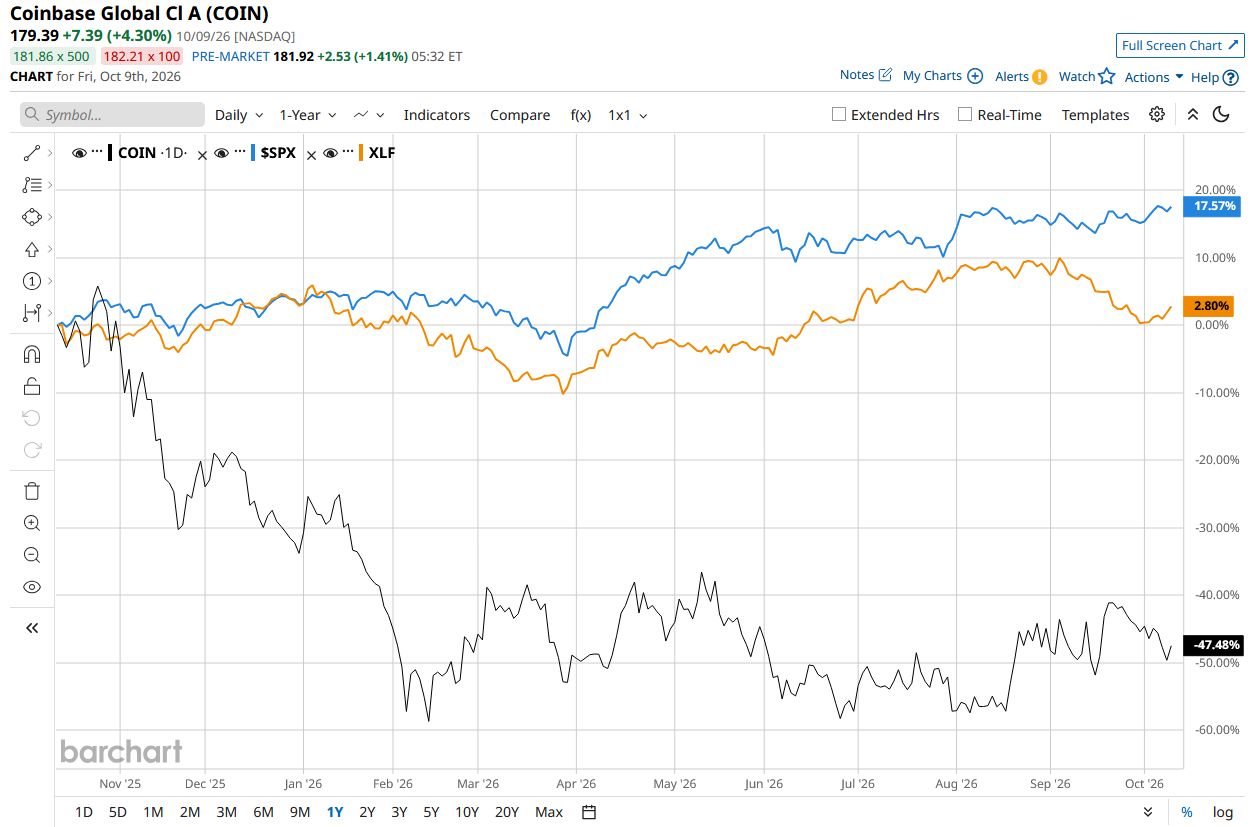
Shares of Coinbase have tanked 53.7% over the past 52 weeks, lagging behind the S&P 500 Index’s ($SPX) 16% rise and the State Street Financial Select Sector SPDR ETF’s (XLF) 2.6% rise during the same time frame.
 www.barchart.com
COIN’s underperformance over the past year can be linked to the underlying problems with the crypto market. With the broader crypto market being a key headwind, stocks related to crypto have been trading down, with major losses over the next year, as showcased by a 28% fall in Bitcoin USD Price (BTC-USD), the primary benchmark of the crypto market, over the past 52 weeks.
More recently, COIN stock has also declined nearly 10% after the Clarity Act failed to clear a critical Senate procedural vote, leaving the industry without clearer U.S. market-structure rules. The bill is expected to establish a crypto market-structure framework, divide oversight between the Securities and Exchange Commission and the Commodity Futures Trading Commission, set registration requirements, and strengthen anti-money-laundering protections. Without the passing of the bill, stocks like COIN continue to face legal and compliance uncertainty, weighing on their share prices.
Analysts are somewhat bullish on COIN, with the stock having a “Moderate Buy” rating overall. Among the 38 analysts covering the stock, 20 are recommending a “Strong Buy,” two recommend a “Moderate Buy,” 13 recommend a ‘Hold,” and three suggest a “Strong Sell” for the stock. COIN’s average analyst price target is $208, indicating an upside of 15.9% from the current levels.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.