

Taiwan Semiconductor’s (TSM) third quarter results showed just how big the AI boom is getting. The company continues to invest billions to maintain its lead, and these investments are now bringing in steady profits.
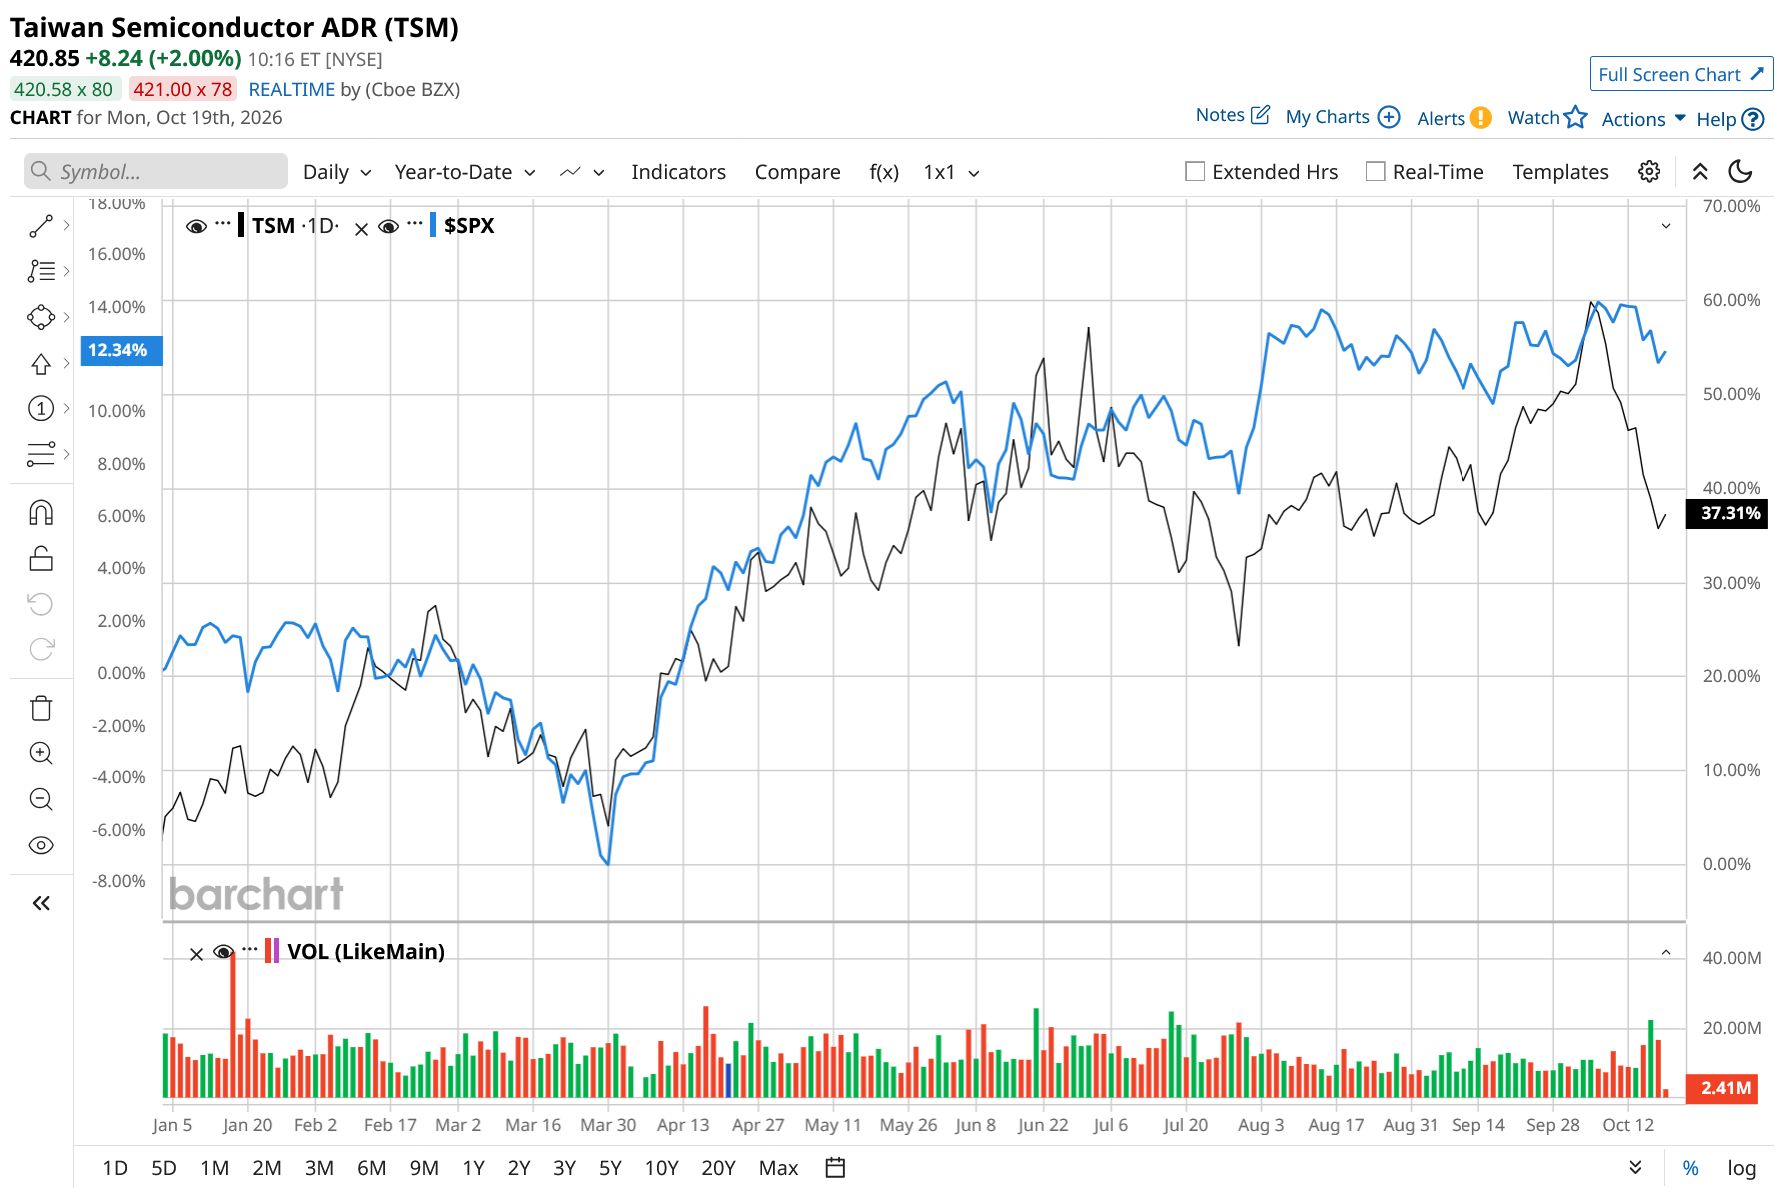
Yet, it wasn’t enough to lift the stock. Although TSM shares are up 38% year-to-date (YTD), the broader AI selloff has dragged down the stock the last few days despite a blowout quarter. As TSMC ramps up its costly 2nm technology, expands overseas manufacturing, and prepares for the next wave of AI demand, protecting profit margins could become its next big challenge.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Q3 Earnings: Another Statement of Strength
Revenue soared 41.2% year-over-year (YoY) to $46.7 billion in the third quarter, rising 16.2% sequentially. Taiwan Semi’s earnings also increased 68.7%. High-performance computing, which includes much of the infrastructure needed for AI, was the key driver. This business grew 22% sequentially and represented 68% of third-quarter revenue. Smartphone-related revenue also rose 10% from the previous quarter and accounted for 21% of the total. TSMC is benefiting from AI investment without relying exclusively on one end market, although high-performance computing is clearly doing most of the heavy lifting.
The company has shown strong momentum this year, with revenue up 40.6% and 33.7% in the first two quarters. Management expects about 58% YoY growth in the fourth quarter, bringing full-year revenue growth to 44%. This shows how strong demand for advanced semiconductor manufacturing is driving earnings growth.
Yet the market seems overly focused on higher capital spending and the AI debt burden. However, not all AI-connected companies are heavily burdened with debt like Coreweave (CRWV). TSMC is the world's leading contract chipmaker, manufacturing advanced semiconductors for some of the biggest names in technology, including Nvidia (NVDA), AMD (AMD), Broadcom (AVGO), and Apple (AAPL). Its reach across AI accelerators, smartphones, and other high-performance computing applications gives it exposure to multiple sources of chip demand. As long as its customers continue to grow their businesses and invest in new products, TSMC's capacity investments have a stronger opportunity to generate returns.
For now, Taiwan Semi’s balance sheet remains strong to fund its expansion. In the third quarter, it held about $126 billion in cash and marketable securities. While risks like overbuilding capacity or margin pressure remain, TSMC stands apart from highly leveraged AI infrastructure providers.
TSMC's $64 Billion AI Bet Faces a Margin Test
The company's gross margin fell 66.4% in the third quarter, from 67.7% in the second quarter. Management attributed this decline to the initial ramp-up of its 2-nanometer process technology. Operating margin was 58.7%, while net profit margin stood at 51.1%. The company spent $13.8 billion on capital expenditures in Q3.
In the third quarter, 2nm technology made up 8% of wafer revenue. The 3 nm process contributed 33%, 5nm brought in 28%, and 7 nm accounted for 10%. Altogether, technologies at 7nm and below generated 79% of wafer revenue. This shows that most of TSMC's revenue comes from making advanced chips.
As TSMC moves to newer technologies like 2nm, making chips overseas is becoming more costly. If these new chips generate enough revenue to cover the higher costs, TSMC’s profits should stay strong. But if costs rise faster than revenue, profit margins could shrink. Management expects a fourth-quarter gross margin between 65% and 67%, with 66% as the midpoint. TSMC confirmed its 2026 capital spending budget of $60 billion to $64 billion. The company expects its spending from 2026 to 2028 to be much higher than in the past three years. This investment is meant to keep up with rising demand for advanced chips, especially those used in agentic AI.
TSMC’s main challenge now is that, even though sales are growing faster, the company still faces short-term margin pressure as it launches new technology. This does not mean TSMC’s strategy is going off track. Instead, it strongly suggests that the costs of preparing for future growth come before the profits from that growth appear. CEO C.C. Wei is still optimistic about demand for AI accelerators, CPUs, and networking chips and expects the company’s annual 2nm capacity to more than double by 2027.
Analysts covering TSMC expect its earnings to increase by 64% in 2027, followed by another 33.6% in 2028.
What Does Wall Street Say About TSM Stock?
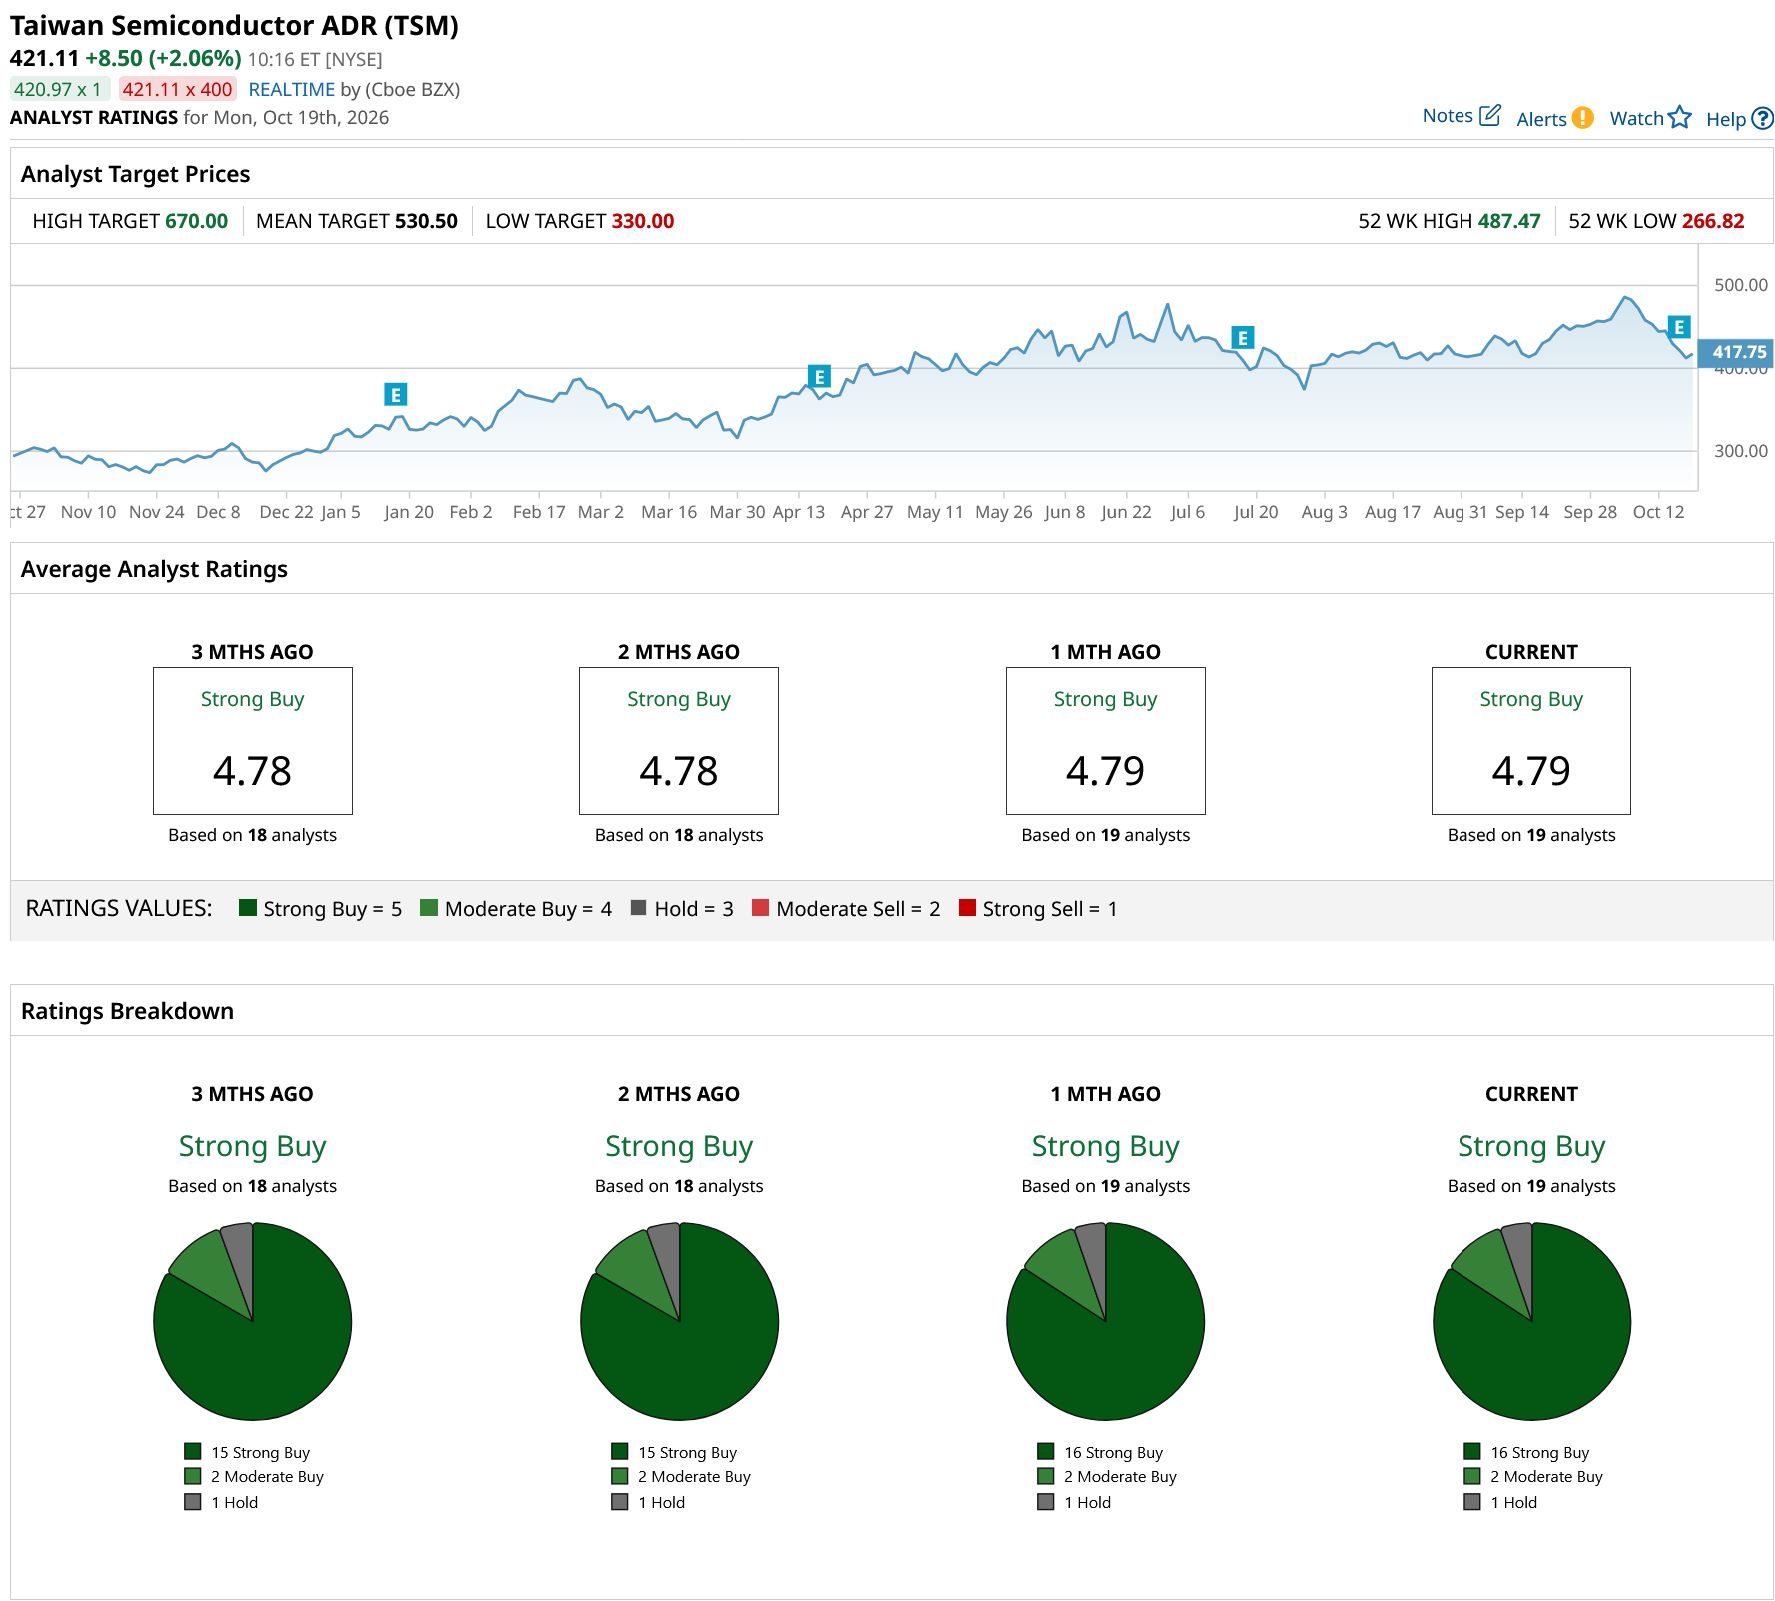
On Wall Street, TSM stock holds a consensus “Strong Buy” rating. Out of 19 analysts with coverage, 16 rate TSM as a “Strong Buy,” two have a “Moderate Buy” rating, and one analyst offers a “Hold” rating. The average price target of $530.50 suggests the stock can gain 26% from current levels. The high target price of $670 implies a potential upside of 59% over the next 12 months.
 www.barchart.com
The Bottom Line
The next few quarters will show if Taiwan Semi can keep growing as it manages the costs of expansion. Investors should look for any ongoing pressure on gross margins and pay attention to the 2nm ramp-up. It is also smart to track capital spending and cash generation. The returns will depend on overseas fab costs, production efficiency, and customer demand. By 2027, revenue growth and margins should give a better sense of how the company is doing.
Overall, TSMC is in a strong position for long-term growth thanks to its lead in advanced chip manufacturing. The company now controls about 73% of the global pure-play foundry market. As chips get more complex, TSMC’s experience and size may give it an even bigger edge over competitors.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Caterpillar vs. Deere: The Better Heavy Equipment Stock for the Data Center Boom TSMC Stock Just Delivered Another Blowout Quarter. Why It's a Buy for the Next 10 Years. Dear Meta Stock Fans, Mark Your Calendar for October 21 Nasdaq Futures Slip as AI Stocks Resume Slide, Oil Jumps; SpaceX Earnings on Tap