

Companies rarely cut jobs just for the sake of it. Sometimes, they are trying to protect margins as growth slows; other times, they are clearing out organizational clutter to make room for a new strategy. For Lightspeed Commerce (LSPD), the latest round of workforce reductions appears to be a mix of both, though the real picture should become clearer soon.
The Montreal-based company, which provides point-of-sale and commerce software to retailers and restaurants, says 250 roles will be affected through employee layoffs and unfilled vacancies. Management says the move is intended to simplify operations and free up resources for customer growth and product innovation. However, Lightspeed has made several staffing cuts over the past few years, particularly since founder Dax Dasilva returned as CEO. The company also completed a strategic review last year without pursuing a go-private deal, choosing instead to focus on North American retail and European hospitality while selling its Upserve restaurant-management business.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
So, is this another step toward a leaner, more focused business, or a sign that Lightspeed is still working to get its cost structure in line with growth? Investors may get more answers when the company reports its quarterly results next month.
LSPD stock closed slightly lower following the announcement, even as the stock has gained momentum recently. Still, shares remain about 19% below their year-ago highs. With the latest cuts adding another layer to the company’s restructuring story, should investors bet on a leaner business or wait for clearer evidence that the strategy is paying off?
About Lightspeed Commerce Stock
Lightspeed Commerce is a cloud-based commerce software company founded in 2005. It provides an integrated platform for retailers, restaurants, golf course operators, and other businesses operating online and through physical locations. Its offerings include point-of-sale (POS) systems, payment processing, inventory and employee management, analytics, eCommerce, customer loyalty tools, and multi-location operations.
Lightspeed also provides wholesale ordering solutions through NuORDER, merchant financing through Lightspeed Capital, and hardware such as payment terminals, scanners, and receipt printers. The company generates revenue primarily through software subscriptions and transaction-based payments, helping merchants manage operations, engage customers, and grow their businesses. Its market capitalization currently stands at $1.5 billion.
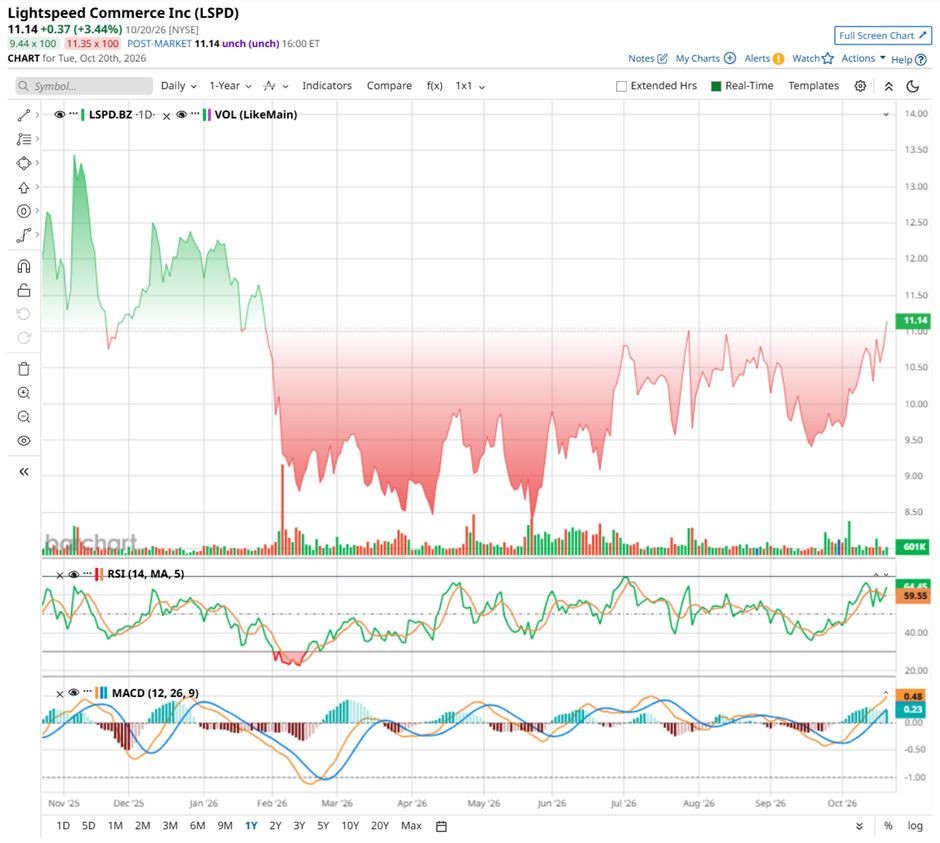
Shares of Lightspeed have had a bumpy ride over the past year, but lately, it seems to be finding its footing again. Shares hit a 52-week high of $13.72 last November before sliding to a low of $7.83 on May 21. Since then, the stock has bounced back sharply, climbing 42.3% from those lows. Still, the recovery has some catching up to do, with shares down 6% over the past 52 weeks and 8% in 2026.
Zoom in, however, and the picture looks more encouraging. LSPD stock has gained 12.8% over the past six months and surged 16% in the past month alone. One recent catalyst has been Lightspeed’s push into AI. The company expanded its Lightspeed AI platform with agentic capabilities designed to go beyond offering insights, helping retailers automate routine tasks, manage inventory, and make decisions more efficiently. The system can recommend actions and prepare tasks for merchants to review and approve, giving investors another potential growth driver to watch.
The technical picture is also leaning bullish. The 14-day RSI sits around 64.5, suggesting positive momentum without yet entering the traditionally overbought zone above 70. Meanwhile, the MACD line has crossed above its signal line, and the positive histogram bars point to strengthening upward momentum. Together, these signals indicate buyers are gaining control, although they don't guarantee that the rally will continue. After such a sharp rebound, investors will want to see whether LSPD can sustain its momentum and turn the recent optimism into lasting gains.
Valuation-wise, LSPD looks relatively inexpensive, trading at 17.87 times forward adjusted earnings and 1.14 times forward sales, both below sector averages.
 www.barchart.com
A Snapshot of Lightspeed Commerce’s Q1 Results
In July, Lightspeed Commerce started fiscal 2027 with a solid quarter. For the first quarter of fiscal 2027, revenue climbed 5.8% year-over-year (YoY) to $322.7 million, while organic revenue growth came in at a much stronger 17%. Both revenue and earnings beat Wall Street’s expectations, giving investors a reason to pay attention.
Transaction-based revenue rose 5%, as reported, to $214.5 million, representing organic growth of 20%. Subscription revenue, meanwhile, increased 5% to $95.4 million, with organic growth of 8%. In other words, Lightspeed is making progress on both its payments and software businesses, rather than relying on just one revenue stream.
The bottom line also moved in the right direction. Adjusted EPS came in at $0.13, up from $0.06 a year earlier, while adjusted EBITDA increased to $17.5 million from $15.9 million. However, cash generation was less impressive. Cash flow from operating activities fell sharply to $0.1 million from $12.4 million, and adjusted free cash flow used widened to $4.4 million from $1.7 million. Still, Lightspeed ended June with $372.1 million in cash and cash equivalents.
Its North American retail and European hospitality businesses remained the standout performers. Together, these growth engines delivered 20% revenue growth, 12% subscription revenue growth, and a 14% increase in gross transaction volume (GTV). Customer locations in these segments rose 10% YoY to approximately 99,000, while total customer locations stood at around 146,000 after the Upserve divestiture. Average revenue per user (ARPU) also increased to approximately $676 from $655, reflecting greater adoption of payments and software modules.
Looking ahead, management maintained its fiscal 2027 outlook, projecting revenue of $1.225 billion to $1.265 billion, organic revenue growth of 12% to 15%, gross profit of $565 million to $585 million, and adjusted EBITDA of $75 million to $95 million. The company expects adjusted free cash flow to grow significantly from fiscal 2026 and remains confident in reaching its $95 million target for fiscal 2028.
Lightspeed is scheduled to report fiscal Q2 2027 results before the market opens on Nov. 5, 2026. Management expects revenue of $316 million to $326 million, gross profit of $141 million to $146 million, and adjusted EBITDA of $20 million to $25 million. After a promising start to the year, the next report will show whether Lightspeed can keep growing while turning that momentum into stronger cash generation.
Analysts monitoring the company remain optimistic, predicting Q2 revenue around $321.03 billion, while EPS is anticipated to rise by 100% YoY to $0.06. Looking further ahead to fiscal 2027, profit is expected to be around $0.23 per share, up 666.7% YoY, before surging another 104.4% annually to $0.47 per share in fiscal 2028.
What Do Analysts Expect for LSPD Stock?
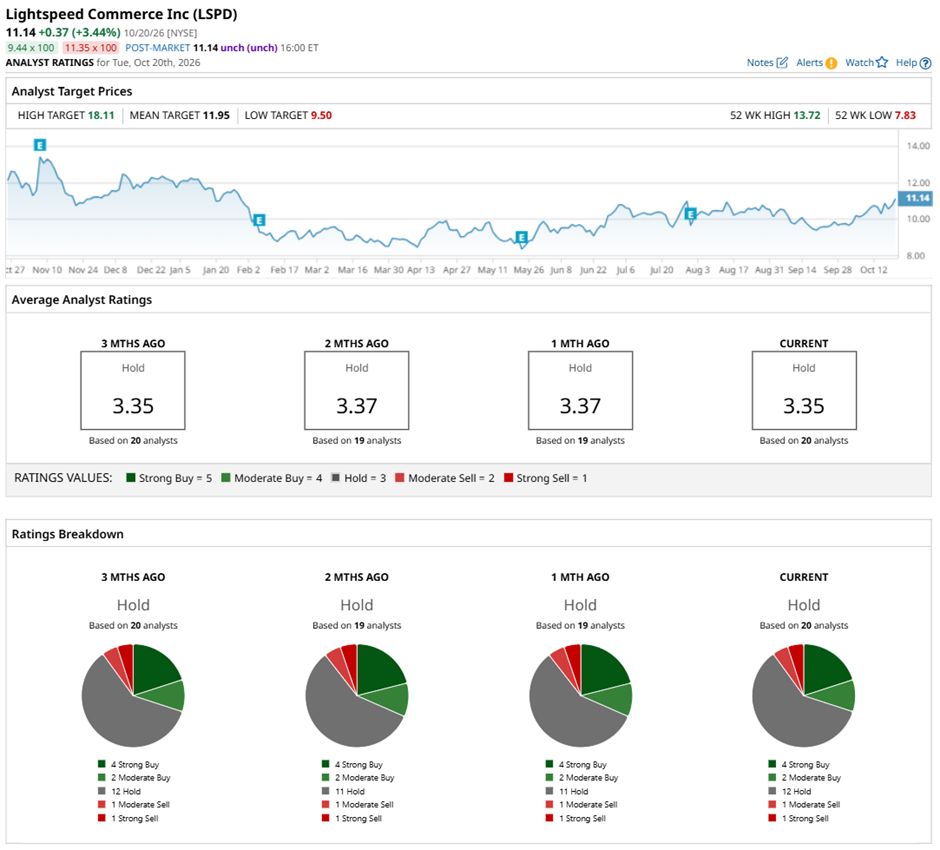
Analysts remain sharply divided on Lightspeed Commerce. LSPD stock has a “Hold” rating overall. Of the 20 analysts covering the stock, four recommend a “Strong Buy,” two have a “Moderate Buy,” 12 suggest a “Hold,” one has a “Moderate Sell,” and the remaining one has a “Strong Sell” rating.
The mean price target of $11.95 suggests LSPD stock has a potential upside of 7.3% from the current levels. The Street-high of $18.11 implies the stock could rise as much as 62.6% from here.
 www.barchart.com
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play LSPD Stock as Lightspeed Slashes 250 Roles Marvell Stock Is Bouncing Back. 3 Reasons the Bulls Aren’t Backing Down. This Blue-Chip Stock Is a ‘Hold’ for the Long Term Thanks to Robust Momentum and Fundamentals Dear Tesla Stock Fans, Mark Your Calendars for December 3