

American Water Works Company, Inc. (AWK) is the largest regulated water and wastewater utility in the United States, serving approximately 3.6 million customers across 14 U.S. states. With a market cap of around $27 billion, the Camden, New Jersey-based company operates treatment plants, pipelines, pumping stations, wells, and storage facilities while also managing municipal water systems.
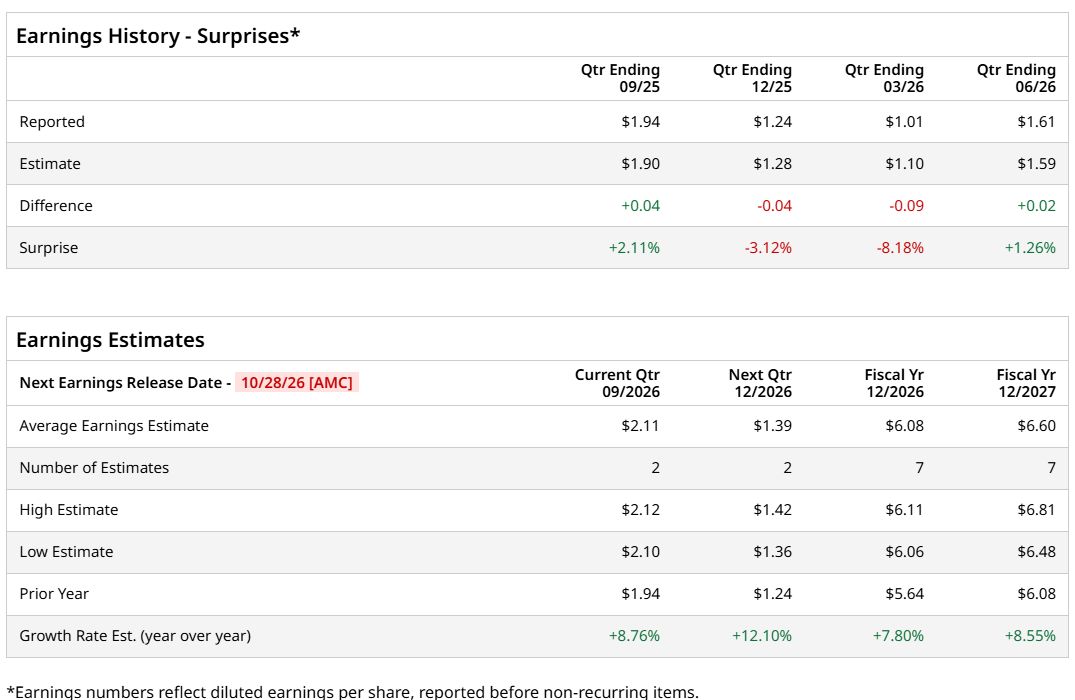
With its extensive infrastructure supporting essential services, American Water Works is set to report Q3 FY2026 results after the market closes on Wednesday, Oct. 28. Analysts expect diluted EPS of $2.11, compared with $1.94 in the year-ago quarter. The company has also beaten earnings estimates in two of the past four quarters.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The outlook extends beyond the upcoming report, with Wall Street forecasting diluted EPS of $6.08 for full-year FY2026, marking year-over-year (YOY) growth of 7.8%. Meanwhile, for FY2027, earnings are projected to reach $6.60, up 8.6% from the preceding year.
 www.barchart.com
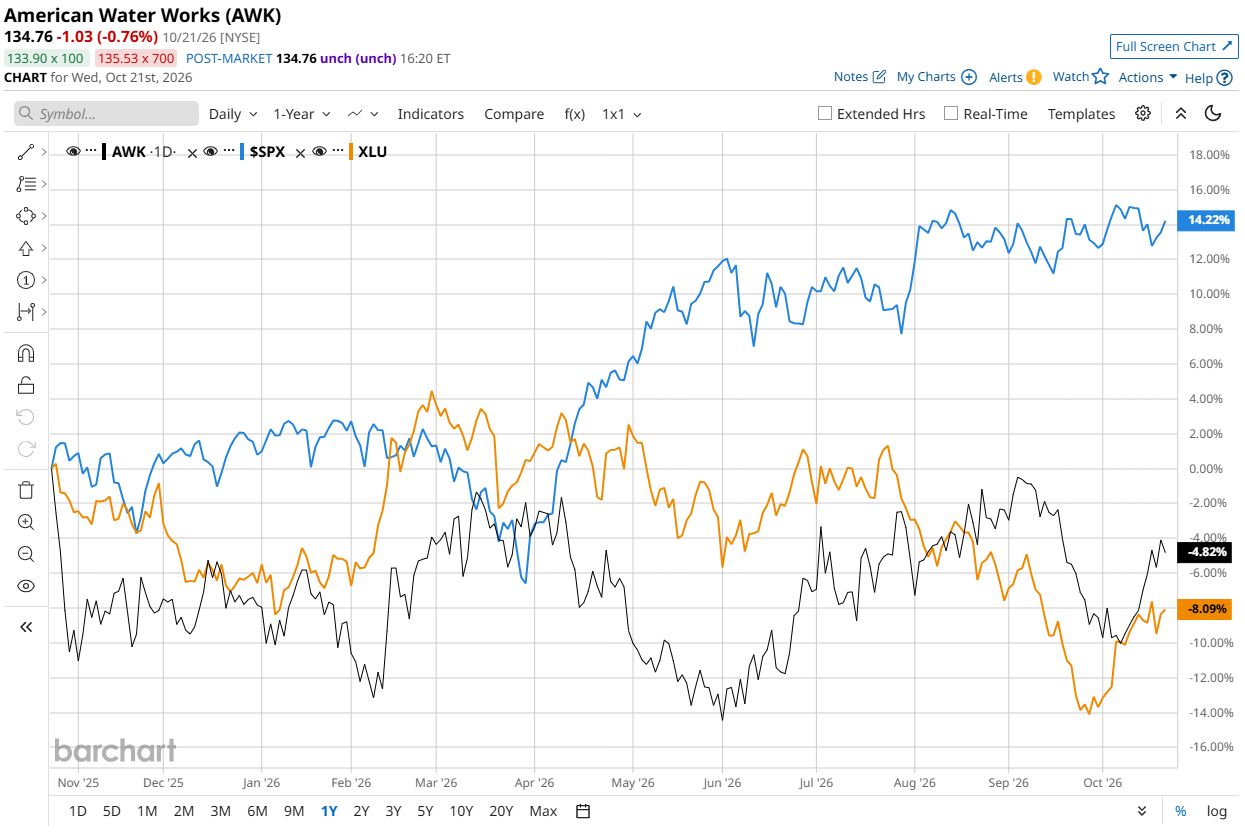
The earnings outlook has yet to translate into stronger stock performance. American Water Works’ shares have fallen 6.5% over the past 52 weeks, while the S&P 500 Index ($SPX) gained 15.2%. The gap narrowed somewhat in 2026, with AWK stock up 3.3%, although the benchmark has gained 13.3% over the same period.
Its performance looks more resilient against the utilities sector, where the State Street Utilities Select Sector SPDR ETF (XLU) has declined 7.3% over the past 52 weeks and slipped 1.6% year-to-date (YTD). While American Water Works struggled to keep pace with the broader market, it has fared better than the sector benchmark.
 www.barchart.com
Part of the pressure stems from the pending all-stock merger with Essential Utilities, Inc. (WTRG), which raises concerns about potential dilution for existing shareholders and remains subject to outstanding regulatory approvals. Even solid Q2 results, including 6.2% YOY revenue growth to $1.36 billion and an 8.1% increase in adjusted EPS to $1.61, have not fully eased valuation concerns.
The anticipated benefits of greater scale remain a future prospect, but recent developments have offered investors some encouragement. Management reaffirmed its 2026 adjusted EPS guidance of $6.02–$6.12 and raised the dividend by 8.2%. Meanwhile, the merger has secured early state-level approvals, providing progress on a transaction that continues to shape the stock’s outlook.
Despite these developments, Wall Street remains measured in its assessment of AWK stock, assigning it an overall rating of “Hold.” Of the 13 analysts covering the name, three recommend “Strong Buy,” nine maintain a “Hold” rating, and one assigns a “Strong Sell” rating.
The average price target stands at $141.92, suggesting potential upside of 5.3%, while the Street-High target of $155 suggests a gain of 15% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Interactive Brokers Increased Its Dividend by More Than 70%. What This Means for IBKR Stock. Jensen Huang Says the Next Wave of AI Is Physical. Forget Nvidia and Tesla, I’d Bet on These 2 Mid-Cap Stocks Instead. Dear Spotify Stock Fans, Mark Your Calendars for October 22 Billionaire Bill Ackman Says Netflix Told Him 'We're Never Going to Do It' on Ads, Then Announced an Ad Model 'Literally 3 Weeks' Later Costing Him $400 Million