

Irving, Texas-based McKesson Corporation (MCK) distributes pharmaceuticals, medical-surgical supplies, and health and beauty care products. With a market cap of $118.4 billion, the company also develops, implements, and supports software that facilitates the integration of data throughout the health enterprise. In addition, McKesson offers analytic, care management, and patient solutions for payers. The healthcare giant is expected to announce its fiscal second-quarter earnings for 2027 after the market closes on Wednesday, Nov. 4.
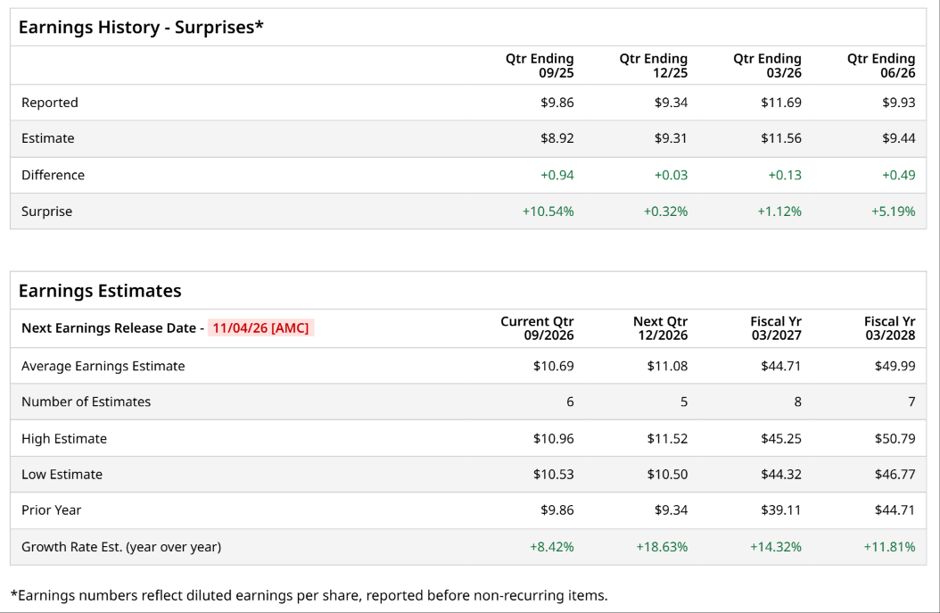
Ahead of the event, analysts expect McKesson to report a profit of $10.69 per share on a diluted basis, up 8.4% from $9.86 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect McKesson to report EPS of $44.71, up 14.3% from $39.11 in fiscal 2026. Its EPS is expected to rise 11.8% year over year to $49.99 in fiscal 2028.
 www.barchart.com
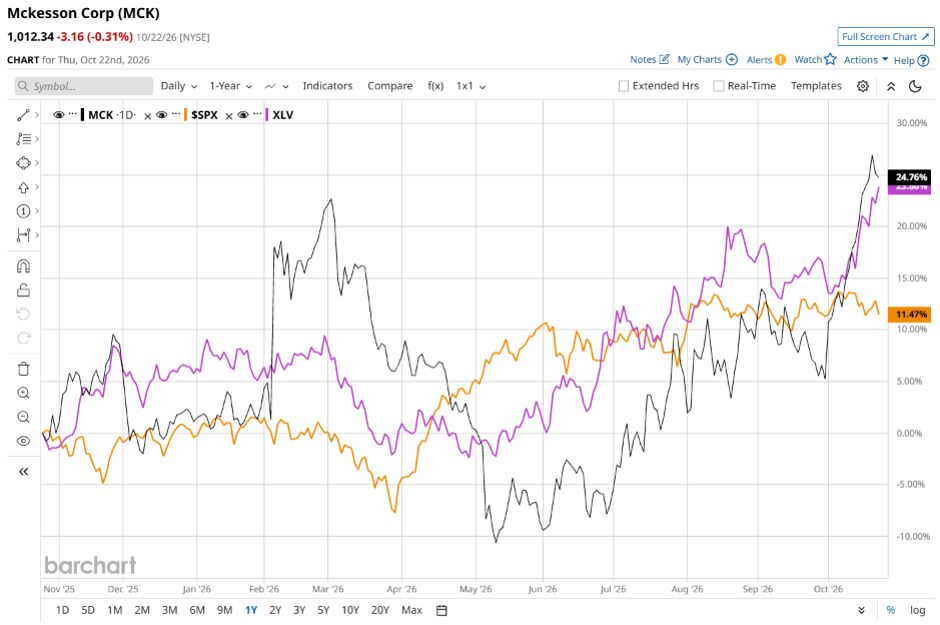
MCK stock has outperformed the S&P 500 Index’s ($SPX) 14.4% gains over the past 52 weeks, with shares up 27.2% during this period. Similarly, it outperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 24.2% returns over the same time frame.
 www.barchart.com
McKesson’s outperformance is a testament to its exceptional operational momentum and dominant positioning in high-growth healthcare sectors. Driven by robust, double-digit volume growth across its core U.S. pharmaceutical distribution network and specialty oncology solutions, the company has consistently delivered strong top-line expansion and rising adjusted earnings. This upward trajectory has been further amplified by surging market demand for GLP-1 weight-loss medications. By capitalizing on these high-demand categories and making strategic investments in technology and infrastructure, McKesson continues to cement its market leadership, turning solid revenue beats into clear indicators of enduring business strength.
On Aug. 5, MCK shares rose 5.6% after reporting its Q1 results. Its adjusted EPS of $9.93 surpassed Wall Street expectations of $9.44. The company’s revenue was $105.4 billion, topping Wall Street forecasts of $104.4 billion. MCK expects full-year adjusted EPS in the range of $44.20 to $45.
Analysts’ consensus opinion on MCK stock is bullish, with a “Strong Buy” rating overall. Out of 17 analysts covering the stock, 13 advise a “Strong Buy” rating, and four give a “Hold.” MCK’s average analyst price target is $1013.33, indicating a marginal potential upside from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.