

Based in Dublin, Ireland, Smurfit Westrock Plc (SW) manufactures and sells paper-based packaging products across global markets. Valued at nearly $22 billion, the company offers a broad portfolio that includes containerboard, corrugated containers, consumer packaging, kraft paper, paper sacks, folding cartons, labels, and displays.
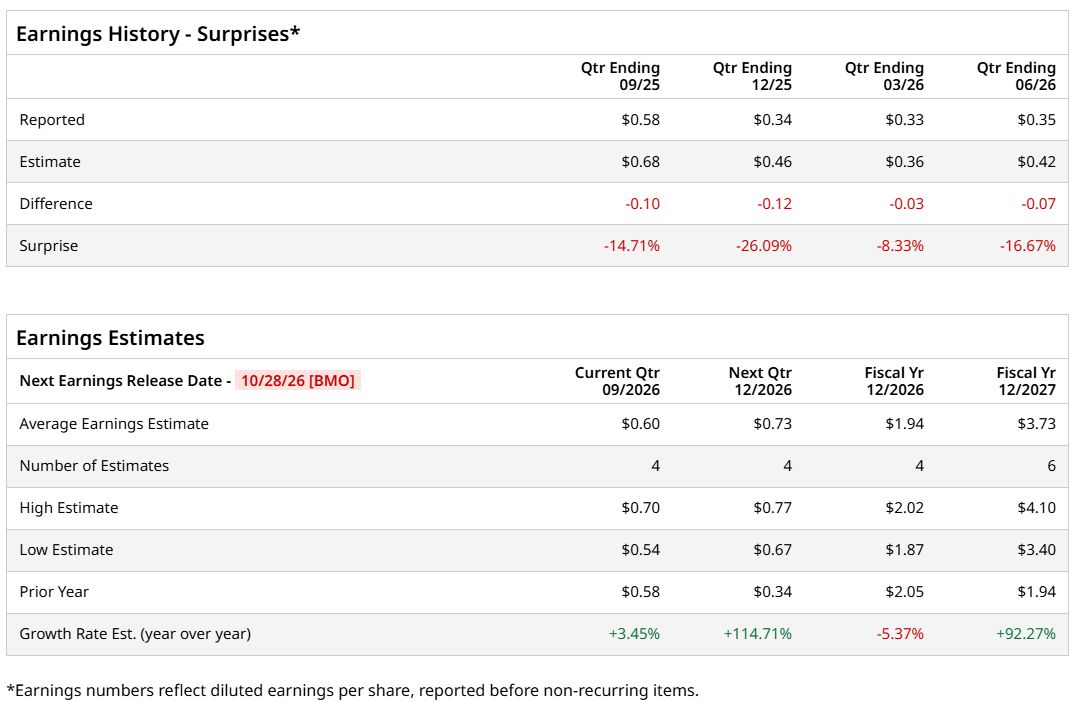
The company is now scheduled to release its Q3 FY2026 results on Wednesday, Oct. 28, before the market opens. Analysts project diluted EPS of $0.60, edging up from $0.58 in the year-ago quarter. The modest improvement, however, comes after four consecutive quarters in which Smurfit missed earnings estimates.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The outlook becomes more challenging when viewed across the full fiscal year. Wall Street expects diluted EPS of $1.94 for FY2026, representing a 5.4% year-over-year (YOY) decline. Forecasts for FY2027, however, paint a much brighter picture, with earnings projected to reach $3.73, a substantial 92.3% increase from the preceding year.
 www.barchart.com
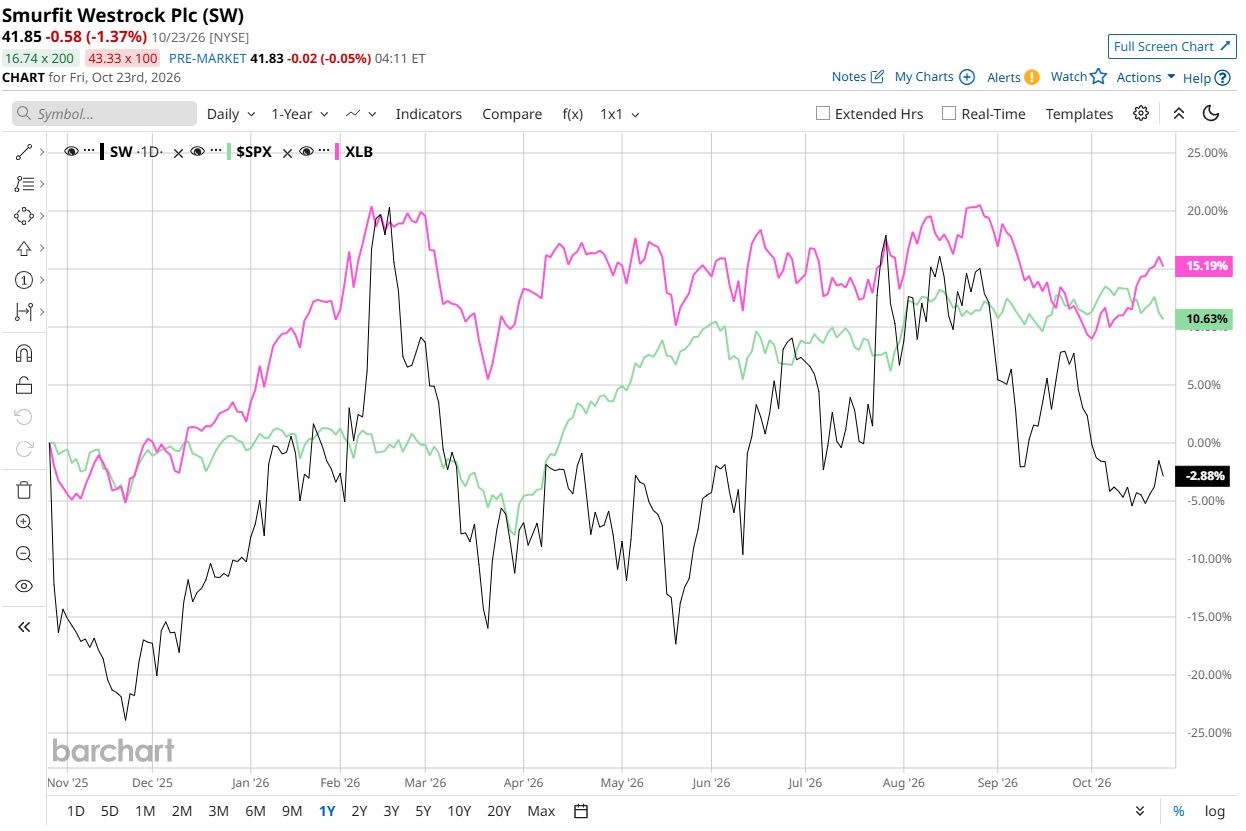
The anticipated earnings recovery has yet to translate into market-leading returns. Over the past 52 weeks, SW stock has fallen 2.7%, while the S&P 500 Index ($SPX) climbed 13.1%. Shares have regained some ground in 2026, rising 8.2% year-to-date (YTD), but still trail the benchmark’s 11.4% gain.
The broader materials sector has fared better, adding another point of comparison for investors assessing Smurfit's performance. The State Street Materials Select Sector SPDR ETF (XLB) has climbed 14.8% over the last 52 weeks and gained 13.1% YTD, outpacing Smurfit on both measures.
 www.barchart.com
Much of that underperformance stems from a difficult late-2025 stretch, when earnings misses, margin compression, and sharply rising freight and energy costs weighed on results and guidance. More recently, the company’s Q2 FY2026 report offered a mixed picture, with revenue beating estimates but adjusted EPS falling short of consensus, adding further pressure to the stock.
Still, the recovery in 2026 suggests that conditions may be turning more favorable. Stronger containerboard pricing momentum, tighter global supply, and the $420 million agreement to acquire CMPC’s Chilean containerboard and corrugated business have bolstered the outlook. Management expects pricing actions and cost recovery to support earnings from late 2026 onward, while a roughly 4.4% dividend yield provides an additional income source.
Against this backdrop, Wall Street remains optimistic about the stock’s prospects. Smurfit carries an overall “Strong Buy” rating, with 15 of the 18 analysts covering the stock recommending a “Strong Buy.” Two analysts assign a “Moderate Buy” rating, while one recommends a “Hold.”
To that end, the average price target stands at $56.22, representing potential upside of 34.3%, while the Street-High target of $69 suggests a gain of 64.9% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
CRWV Stock Warning: Why Bernstein Says CoreWeave Shares Haven’t Bottomed Out Yet How to Play the Brutal Selloff in CoreWeave Stock Tesla Is Betting on a Flying Car to Combat Its Stock Slump Wedbush Gives a Thumbs Up to Super Micro’s Preliminary Q1 Results. Troubles for SMCI Stock Could Finally Be in the Rear-View.