

On Oct. 16, Nvidia (NVDA) and Mercedes-Benz (MBGYY) agreed to extend their partnership. The two companies will focus on developing next-generation automated driving systems. Nvidia provides Hyperion, the car’s computing and sensor platform, along with Alpamayo, AI reasoning software designed for city driving. The partnership has already produced a system: Mercedes’ first urban point-to-point assistance system for Western markets. Their longer-term goal is to support Level-4 applications, which allow cars to drive themselves under specific conditions.
The main risk is how long that transition takes, particularly because Level 4 is still in the future and automotive contributes little compared with Nvidia’s data center business. Still, I think NVDA’s combination of chips, software, and safety capabilities puts it in a strong position as vehicle automation expands.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Nvidia Stock
Nvidia is a premier technology firm known for its expertise in graphics processing units and artificial intelligence solutions. The company is renowned for its pioneering contributions to gaming, data centers, and AI-driven applications. NVDA’s technological solutions are developed around a platform strategy that combines hardware, systems, software, algorithms, and services to provide distinctive value. The chipmaker has a market cap of $5.49 trillion, making it the world’s most valuable company. Founded in 1993, the company is headquartered in Santa Clara, California.
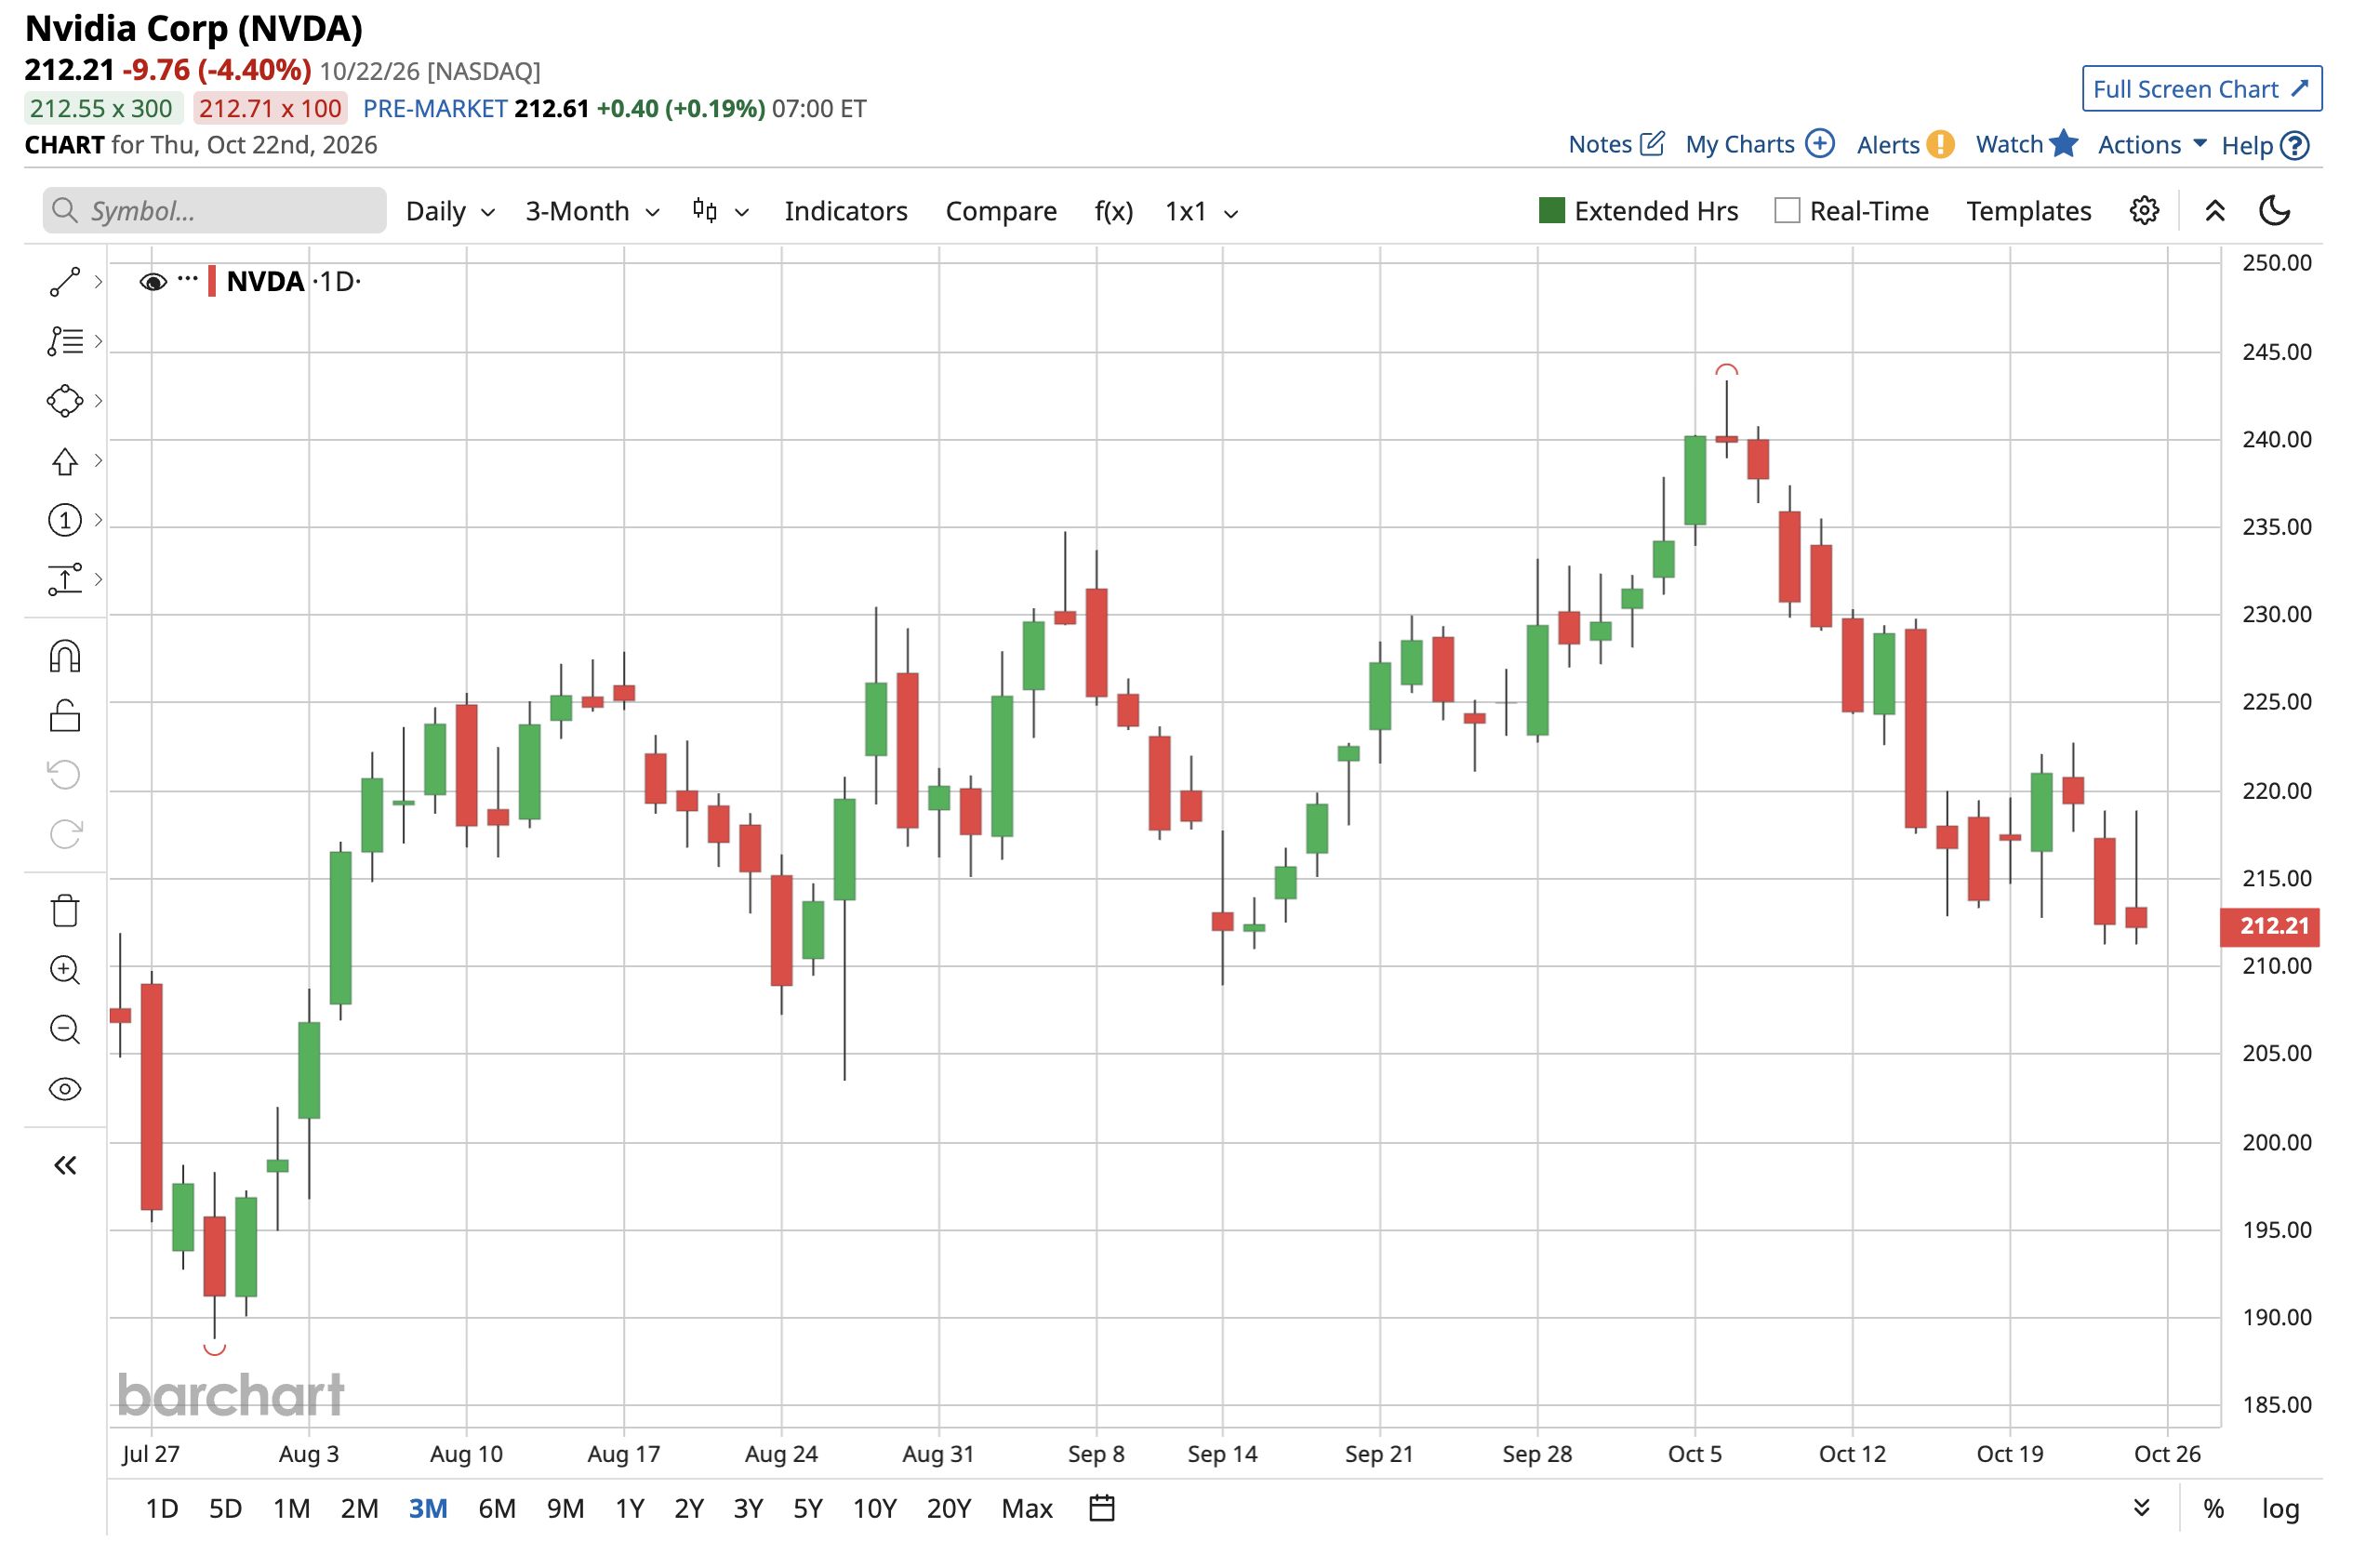
Nvidia’s 2026 has been a story of volatility inside an uptrend. Shares of the AI company have climbed 17% on a year-to-date (YTD) basis as relentless spending on AI infrastructure continues to drive demand for the company’s GPUs, networking equipment, and increasingly its CPUs. The bull case rests on hyperscaler spending that shows no sign of slowing, an inference boom that extends the product cycle, and an aggressive buyback.
 www.barchart.com
Nvidia’s Multiples Sit Well Below Its History
At 23.33x forward earnings, Nvidia trades at a 44% discount to its five-year average. Its forward price-to-sales ratio of 12.74x is also 35% below its five-year norm of 19.64x. The discount may reflect investor concerns that growth will moderate, as analysts project EPS growth to slow to about 34.11% in fiscal 2029. However, they still expect earnings to increase approximately 95% this fiscal year and 71% next year. This could bring the P/E down to approximately 14x based on fiscal 2028 earnings. The company also holds around $62.47 billion in cash against $38.86 billion in debt, modest amounts for a company valued at $5.25 trillion.
I believe its current valuation could offer long-term investors room for gains if automated driving expands and earnings meet expectations.
Nvidia Forecasts $108 Billion in Q3 Revenue as AI Spending Accelerates
On August 26, the company reported its Q2 FY2027 earnings, prompting an 8.7% jump in the stock during the following trading session. Revenue soared 105.9% year over year (YoY) to $96.2 billion, ahead of analysts’ expectations of $92.17 billion. The Data Center business remained the undisputed growth engine, growing 117% YOY to $89 billion. Hyperscale revenue reached $49 billion as Blackwell adoption continued and cloud infrastructure investment expanded. Even so, the additional spending has not prevented Nvidia from delivering stronger profitability. Non-GAAP operating income climbed 124.1% to $64 billion. Non-GAAP net income rose 117.9% from the prior year’s quarter to $54 billion, while adjusted EPS rose 119.8% YOY to $2.22, beating the Street’s forecast of $2.10.
Looking forward to the third quarter, the company expects revenue to be $108 billion. Q3 FY2027 EPS is forecast to increase 99.2% YoY to $2.47. For the full FY2027, estimates stand at $9.25, implying annual growth of 102.4%. The following year is expected to bring further gains, with FY2028 EPS projected at $15.53, up another 67.9% YOY.
What Do Analysts Expect for NVDA Stock?
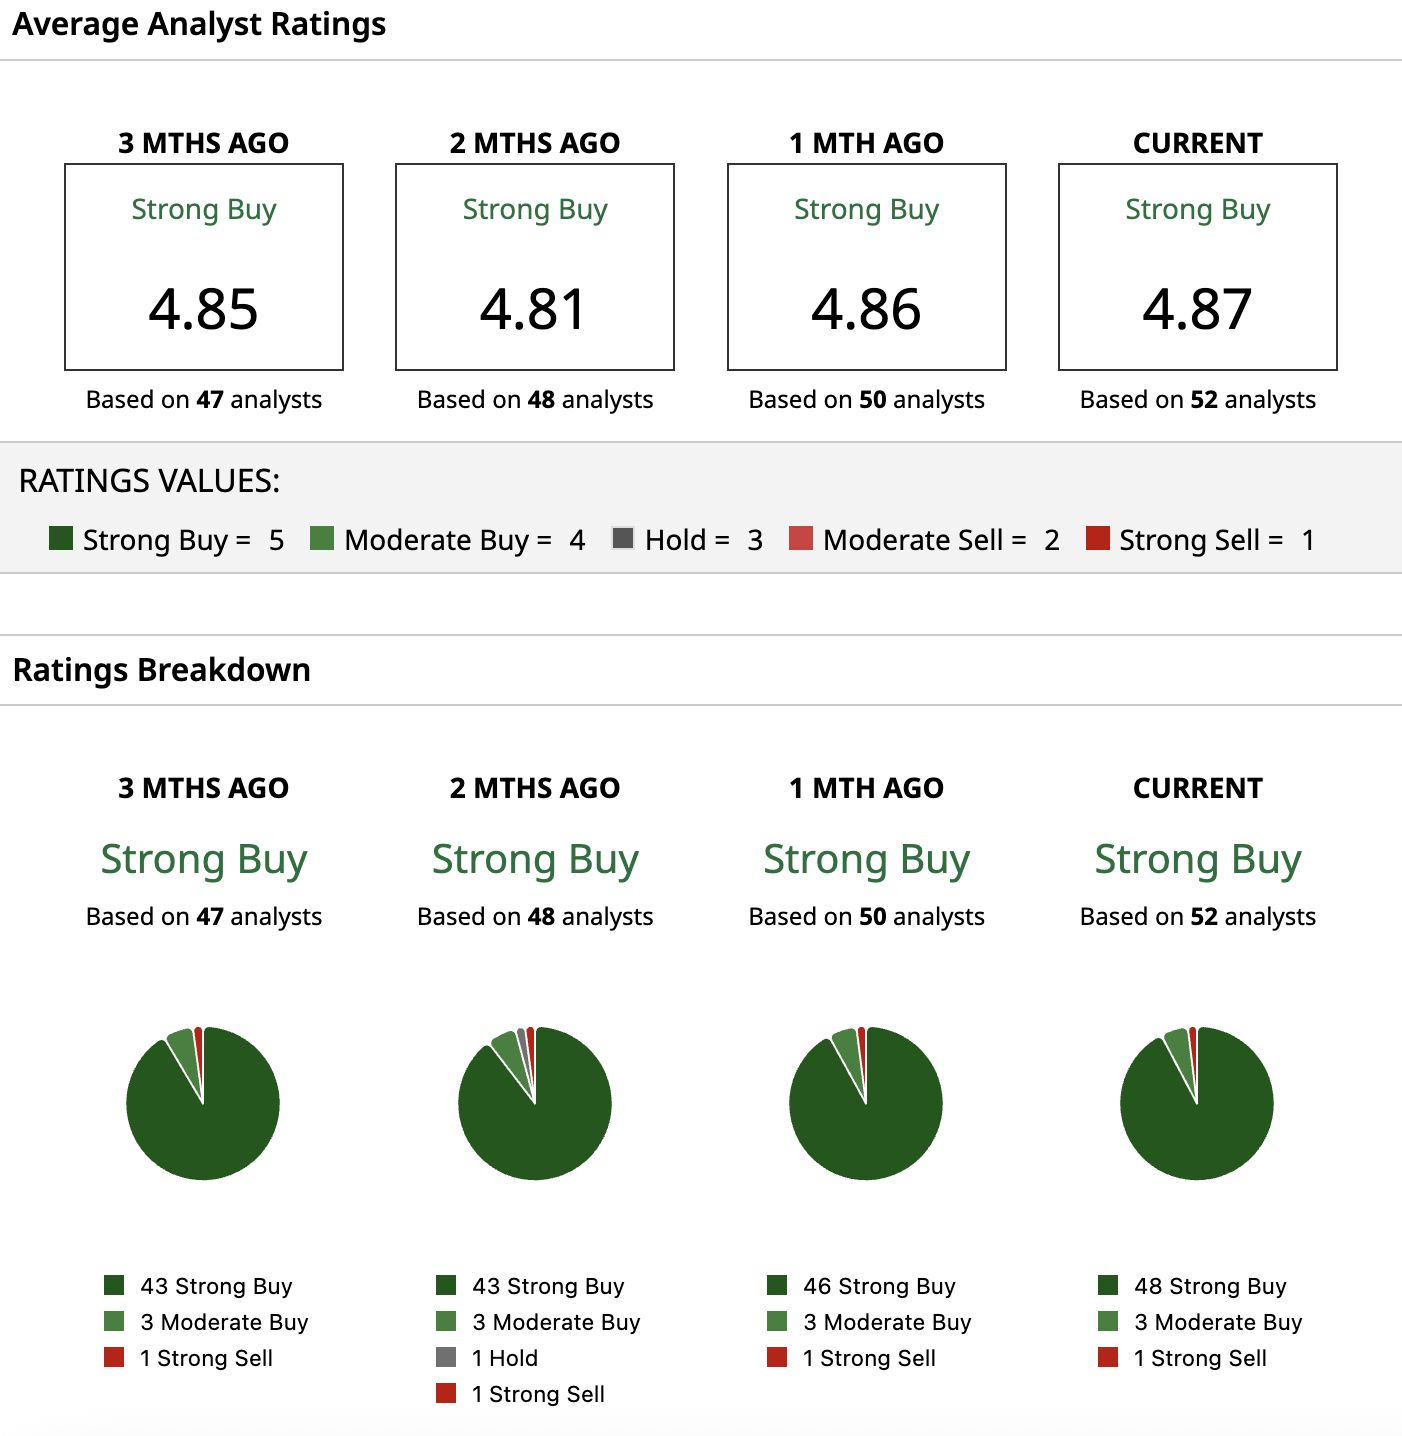
Wall Street remains optimistic about Nvidia, with the stock carrying an overall Strong Buy rating. Of the 52 analysts covering the name, 48 assign a “Strong Buy,” three recommend a “Moderate Buy,” and just one gives the shares a “Strong Sell” rating. Against that backdrop, the average price target of $328.75 represents potential upside of 55%. Meanwhile, the Street-High target of $515 points to an impressive gain of 143% from current levels.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.