

Apple (AAPL) will release its fiscal fourth-quarter earnings on Monday, Nov. 2. Sustained product demand and higher pricing will likely support Apple’s Q4 performance. However, its high valuation and supply constraints could limit upside.
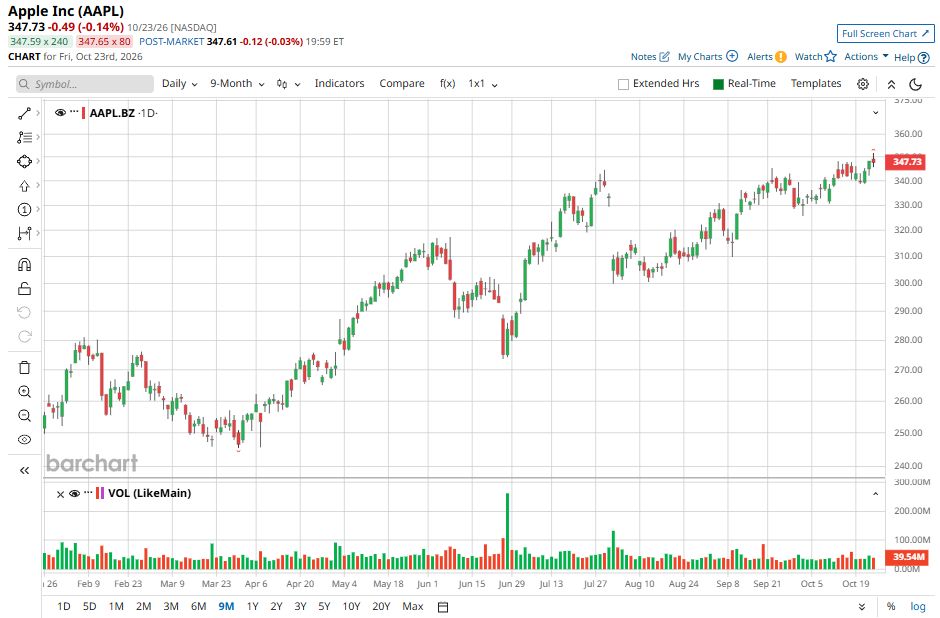
Apple stock is up 27.9% year to date, outperforming its large tech peers. Moreover, the stock is trading close to its all-time high, suggesting it has priced in positives ahead of the Q4 earnings release.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Apple Q4 Outlook
Apple is expected to sustain revenue growth in the fourth quarter, supported by continued demand for the iPhone and Mac, and the resilience of its Services segment. However, the company’s growth rate is likely to moderate from the previous quarter as supply constraints limit hardware sales. Meanwhile, rising memory costs could weigh on profitability, although favorable cost trends in certain non-memory components and higher pricing provide relief.
 www.barchart.com
Apple’s Products segment generated $78.7 billion in revenue in the third quarter, up 18% year over year. Strong demand for the iPhone and Mac drove growth, with both recording double-digit revenue gains. iPhone revenue rose 22% year over year to $54.3 billion, supported by the iPhone 17 lineup. The company also reported growth across most major markets, while its active iPhone installed base hit a record high, led by a record June quarter for customers upgrading their devices.
Mac revenue increased 29% year over year to $10.4 billion, driven by solid demand for the MacBook Neo and MacBook Pro.
Despite this positive momentum, product-related growth is expected to decelerate in the fourth quarter. Management said during the Q3 earnings call that supply constraints would intensify significantly sequentially, affecting product availability. Consequently, Apple guided total company revenue growth of 9%-11% year over year in the September quarter, down from 16% in Q3.
The iPhone segment is expected to remain a primary revenue contributor, supported by sustained consumer demand. Nevertheless, supply limitations are likely to restrict the conversion of demand into reported sales. Management anticipated mid-teens year-over-year iPhone revenue growth for the September quarter, below the 22% increase recorded in the preceding quarter.
Apple’s Services business generated $30.7 billion in Q3 revenue, an increase of 12% year over year. The segment is expected to maintain its growth momentum, supported by broad-based contributions from advertising, the App Store, AppleCare, Apple Music, and Apple TV+. Cloud-related offerings and payment services are also expected to drive revenue growth.
Apple’s expanding installed base is a significant competitive advantage. The company reported about 2.5 billion active devices at the end of Q3, creating a substantial customer ecosystem it can monetize through subscriptions, digital content, advertising, payment solutions, and cloud storage. Further expansion of this installed base in Q4 could increase the number of potential service customers and deepen engagement with existing users.
Apple’s fourth-quarter earnings will benefit from higher revenue and favorable pricing. However, elevated memory costs may constrain margin expansion. Conversely, lower costs for certain non-memory components could partially offset these pressures.
Analysts expect Apple to report Q4 earnings per share of $2, an 8.1% year-over-year increase. The iPhone maker has exceeded analysts’ EPS expectations for four consecutive quarters, reflecting consistent earnings outperformance.
Valuation and Supply Risks Could Limit AAPL Stock’s Upside
While Apple’s strong iPhone demand, resilient Services business, and favorable pricing are expected to support Q4 earnings growth, intensifying supply constraints and rising memory costs could temper revenue momentum and profitability.
With the stock already up 27.9% year to date and trading near its all-time high, expectations appear elevated, leaving limited room for disappointment. Although Apple’s track record of earnings beats is encouraging, investors should exercise caution ahead of the earnings release, as solid results may not drive further gains.
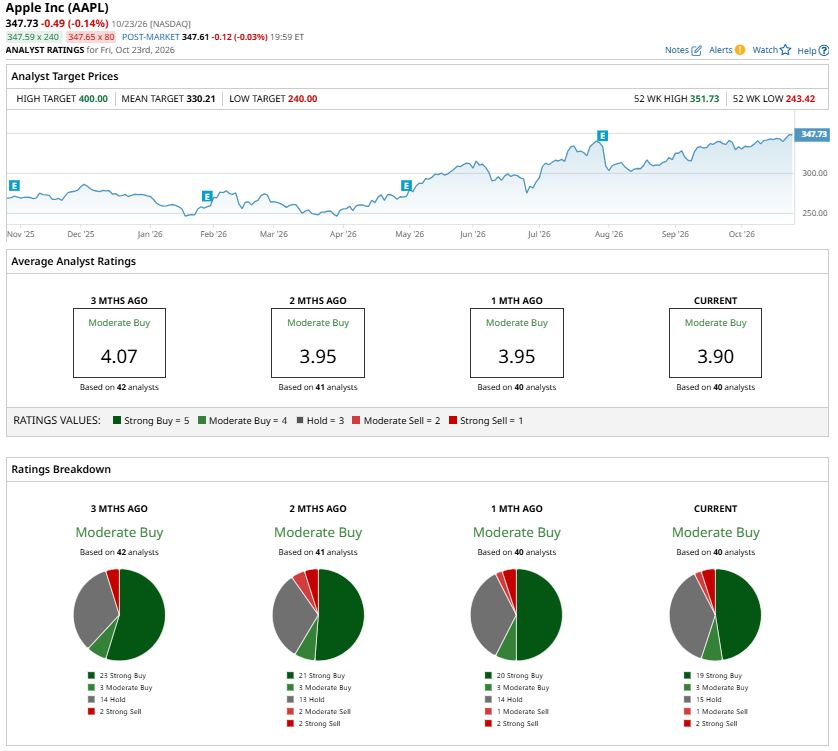
With AAPL stock trading at a forward earnings multiple of 36.3, which is high relative to its earnings growth potential, analysts have a “Moderate Buy” consensus rating.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Coca-Cola Earnings, Here's What Barchart Data Says Comes Next for KO Stock A $1 Billion Reason to Buy Skydance Stock Tesla, SpaceX, and a $100 Billion Chip Bet: Elon Musk Is Playing a Different Game Ahead of Visa Earnings, Here's What Barchart Data Says Comes Next for V Stock