

Intel (INTC) will report its Q3 earnings on Oct. 29. Despite ongoing supply constraints, the company is expected to maintain solid growth, supported by the rapid expansion of AI infrastructure. These structural tailwinds are creating significant growth opportunities across Intel’s core product segments and foundry business.
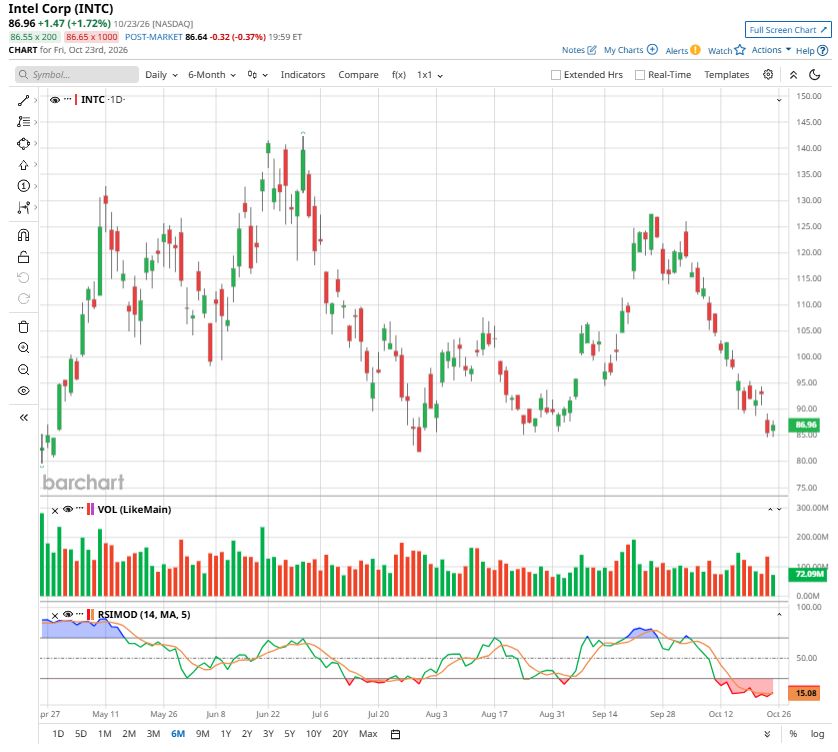
Intel’s stock has surged 135.7% so far in 2026, reflecting strong AI-driven demand for its products. However, shares have retreated about 39% from their 52-week high, reflecting profit booking after the sharp rally. Against this backdrop, the upcoming earnings report could serve as a key catalyst for the stock. Strong quarterly results and an upbeat outlook could help rebuild investor confidence and drive a recovery in INTC.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Intel to Deliver Solid Q3 Growth
Intel appears well-positioned to deliver solid Q3 growth, supported by sustained demand across its AI-related businesses, which make up a significant portion of its revenue. Continued investment in AI infrastructure, rising demand for server CPUs, and growth in specialized silicon products will support its growth.
Intel reported Q2 revenue of $16.1 billion, up 25% year over year. Revenue from its AI-driven businesses increased 70%, accounting for approximately 70% of total revenue. The AI businesses will likely sustain solid momentum in Q3, supporting overall revenue.
The Data Center and AI (DCAI) segment is expected to remain a key growth driver. The business generated $6.3 billion in Q2 revenue, up 24% sequentially and 59% year over year. Continued spending by hyperscale cloud providers and enterprise customers could sustain this momentum in Q3. As AI workloads expand beyond model training into inference, agentic AI, and multi-agent systems, demand for server CPUs is also increasing. This trend creates a solid growth opportunity for Intel, as customers need more computing capacity to support increasingly complex AI applications.
Intel’s purpose-built silicon portfolio could provide another source of incremental growth. Management expects revenue from these products to increase significantly sequentially and year over year, reflecting growing demand for specialized computing solutions. In addition, strategic customer wins and long-term agreements improve revenue visibility and support business expansion over the coming quarters.
Intel expects Q3 revenue of $15.8 billion to $16.8 billion. At the midpoint of $16.3 billion, the guidance implies approximately 19% year-over-year growth. With demand across its data center, AI, and specialized silicon businesses remaining strong, Intel could surpass its internal guidance range.
Higher sales volumes and a favorable average selling price mix will support profitability. Management forecasts an adjusted gross margin of 42% for Q3, up 200 basis points from the year-ago quarter.
Higher revenue and margins could drive stronger earnings. Intel expects adjusted earnings of $0.38 per share in Q3, up approximately 65% from $0.23 in the prior-year period.
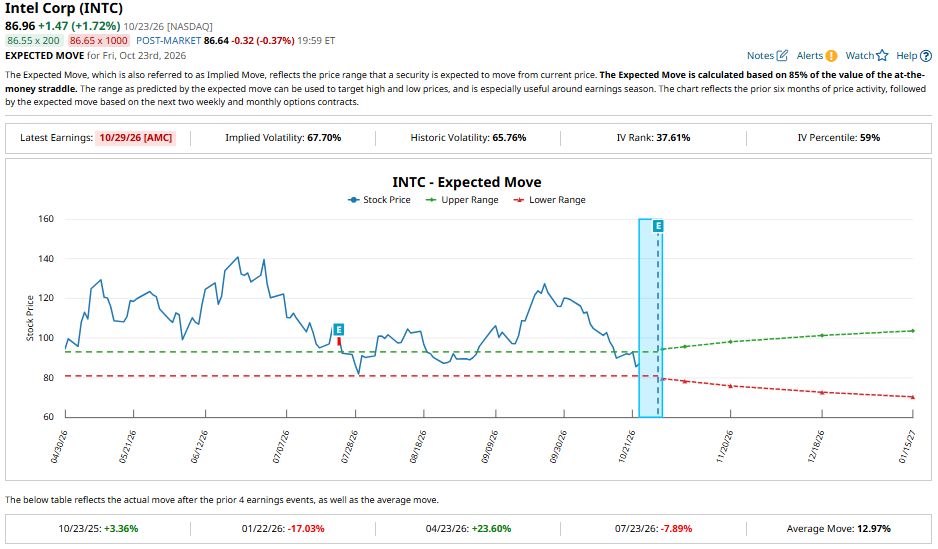
Overall, sustained AI-related demand, strong DCAI performance, and improving margin expectations provide a constructive near-term outlook for Intel and could act as a catalyst for its stock. However, Intel’s post-earnings performance has been mixed over the past four quarters, with the stock rising twice and falling twice. The average post-earnings move has been approximately 13%, suggesting the potential for substantial volatility after the announcement.
 www.barchart.com
Conclusion: Intel’s Q3 Earnings Could Set the Stock’s Direction
Intel’s Q3 earnings could be a key catalyst for the stock’s next move, with sustained AI-driven demand, data center growth, and improving margins shaping its outlook. Continued investment in AI infrastructure, rising demand for server CPUs, a favorable product mix, and growth in specialized silicon could support revenue expansion and strengthen profitability.
However, analysts remain cautiously optimistic, maintaining a “Moderate Buy” consensus rating after Intel’s sharp 2026 rally. Stronger-than-expected results and upbeat forward guidance, however, could provide further upside momentum for Intel stock.
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Coca-Cola Earnings, Here's What Barchart Data Says Comes Next for KO Stock A $1 Billion Reason to Buy Skydance Stock Tesla, SpaceX, and a $100 Billion Chip Bet: Elon Musk Is Playing a Different Game Ahead of Visa Earnings, Here's What Barchart Data Says Comes Next for V Stock