

Alphabet (GOOG) (GOOGL) will announce its third-quarter financial results on Wednesday, October 28. The technology giant is expected to deliver solid growth, driven by a resilient core advertising business, continued growth in Google Cloud, and an expanding contribution from artificial intelligence (AI) across its ecosystem.
Against this backdrop, here are three key factors in Alphabet’s Q3 earnings report to watch for that will justify its substantial AI infrastructure investments and support GOOGL stock.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
1. AI Integration to Keep Powering Google Search Growth
Alphabet’s integration of AI into Google Search is emerging as a key driver of user engagement and advertising monetization. Innovations such as AI Overviews and AI Mode are enhancing the search experience by delivering more contextual and relevant information. These capabilities create incremental monetization opportunities by enabling advertisers to connect with users through more targeted, intent-driven advertising placements.
 www.barchart.com
Alphabet’s second-quarter financial results showed the benefits of AI integration in the Search business. Google Search and other advertising revenue increased 17% year over year (YoY) to $63.3 billion in Q2. Meanwhile, total Google advertising revenue grew 14% to $81.6 billion, supported in part by a solid 13% increase in YouTube advertising revenue. These results suggest that Alphabet’s AI-led enhancements are supporting growth across its core advertising ecosystem.
Looking ahead, Search faces a tougher year-over-year comparison in the third quarter as it begins to lap the acceleration it posted in the same period last year. This could moderate reported growth rates.
However, Alphabet’s substantial AI investments could deliver durable commercial returns and strengthen Google Search’s competitive position.
2. Google Cloud Revenue to Accelerate
Google Cloud remains one of Alphabet’s key growth drivers, driven largely by rising demand for cloud services and AI solutions. In Q2, the segment’s revenue increased by 82% year over year to $24.8 billion, driven by strong performance across Google Cloud Platform (GCP), AI solutions, and AI infrastructure. Growth remained strong even after excluding revenue from TPU system sales.
This momentum in the Cloud segment will likely continue, with sales growth accelerating further in Q3. Google Cloud offers an integrated range of services, including AI chips, models, data analytics, cybersecurity, and AI agent platforms. By bringing these capabilities together, Google provides businesses with a more complete set of solutions while encouraging greater use of its cloud services. Gemini also plays an important role in this strategy, as it is being integrated across products.
Google Cloud is also seeing strong demand across different industries, customer groups, and geographical markets. Its growth is being supported by the acquisition of new customers at a faster pace, existing customers expanding their use of Google Cloud services, and the company benefiting from its partner ecosystem,
Overall, Google Cloud’s performance is expected to remain solid. Its integrated technology offerings, growing customer base, stronger partner network, and TPU system sales provide a solid foundation for further acceleration.
3. Alphabet Stock Trades at a Discount to Its Peers
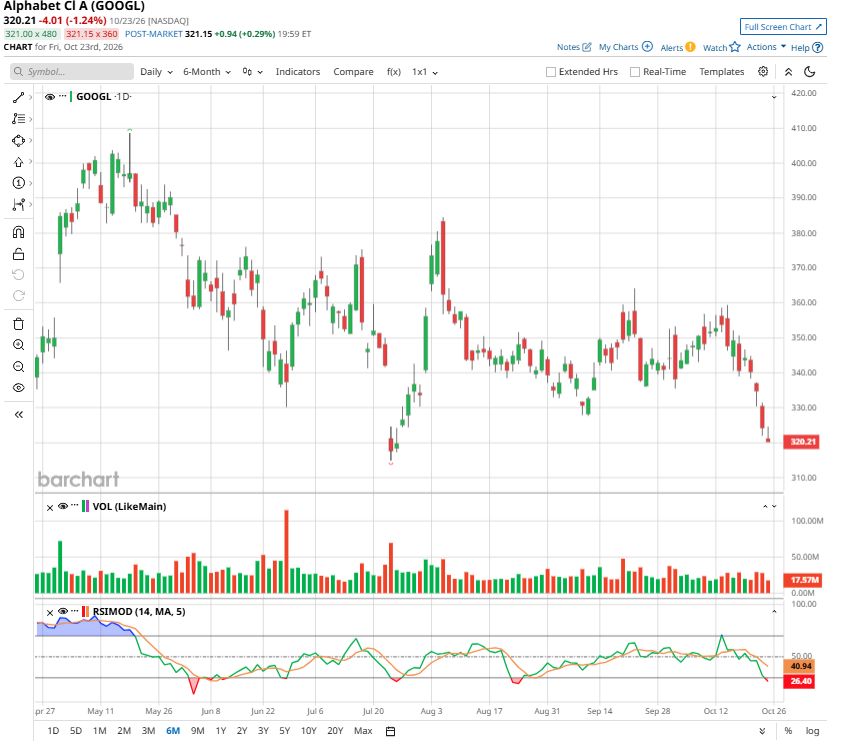
Alphabet is positioned to deliver healthy third-quarter revenue growth, while analysts expect year-over-year earnings growth despite substantial AI investments. Moreover, GOOGL stock appears relatively inexpensive compared with major technology peers.
Its forward price-to-earnings (P/E) ratio stands at 15.7, significantly below Microsoft’s (MSFT) 26.5 and Amazon’s (AMZN) 33.2. Its lower valuation offers an attractive entry point.
Alphabet Stock Appears Attractive Ahead of Q3
Alphabet’s robust advertising business, accelerating Google Cloud growth, and expanding AI capabilities position the company for sustained growth in Q3 and beyond. Its relatively attractive valuation compared with major technology peers also strengthens its investment appeal.
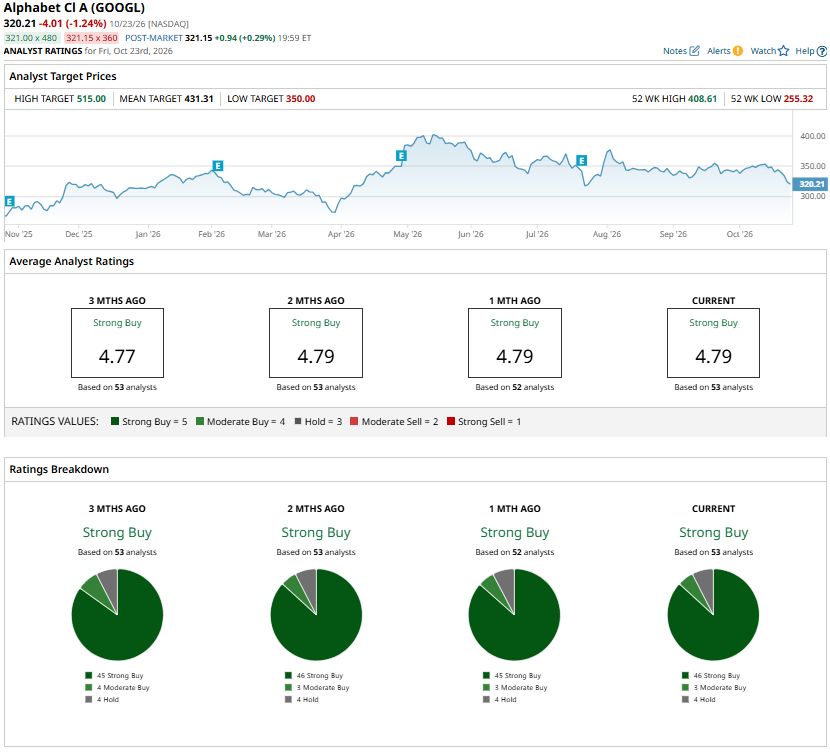
Analysts’ sentiment remains positive, with GOOGL stock maintaining a “Strong Buy” consensus rating.
 www.barchart.com
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Coca-Cola Earnings, Here's What Barchart Data Says Comes Next for KO Stock A $1 Billion Reason to Buy Skydance Stock Tesla, SpaceX, and a $100 Billion Chip Bet: Elon Musk Is Playing a Different Game Ahead of Visa Earnings, Here's What Barchart Data Says Comes Next for V Stock