

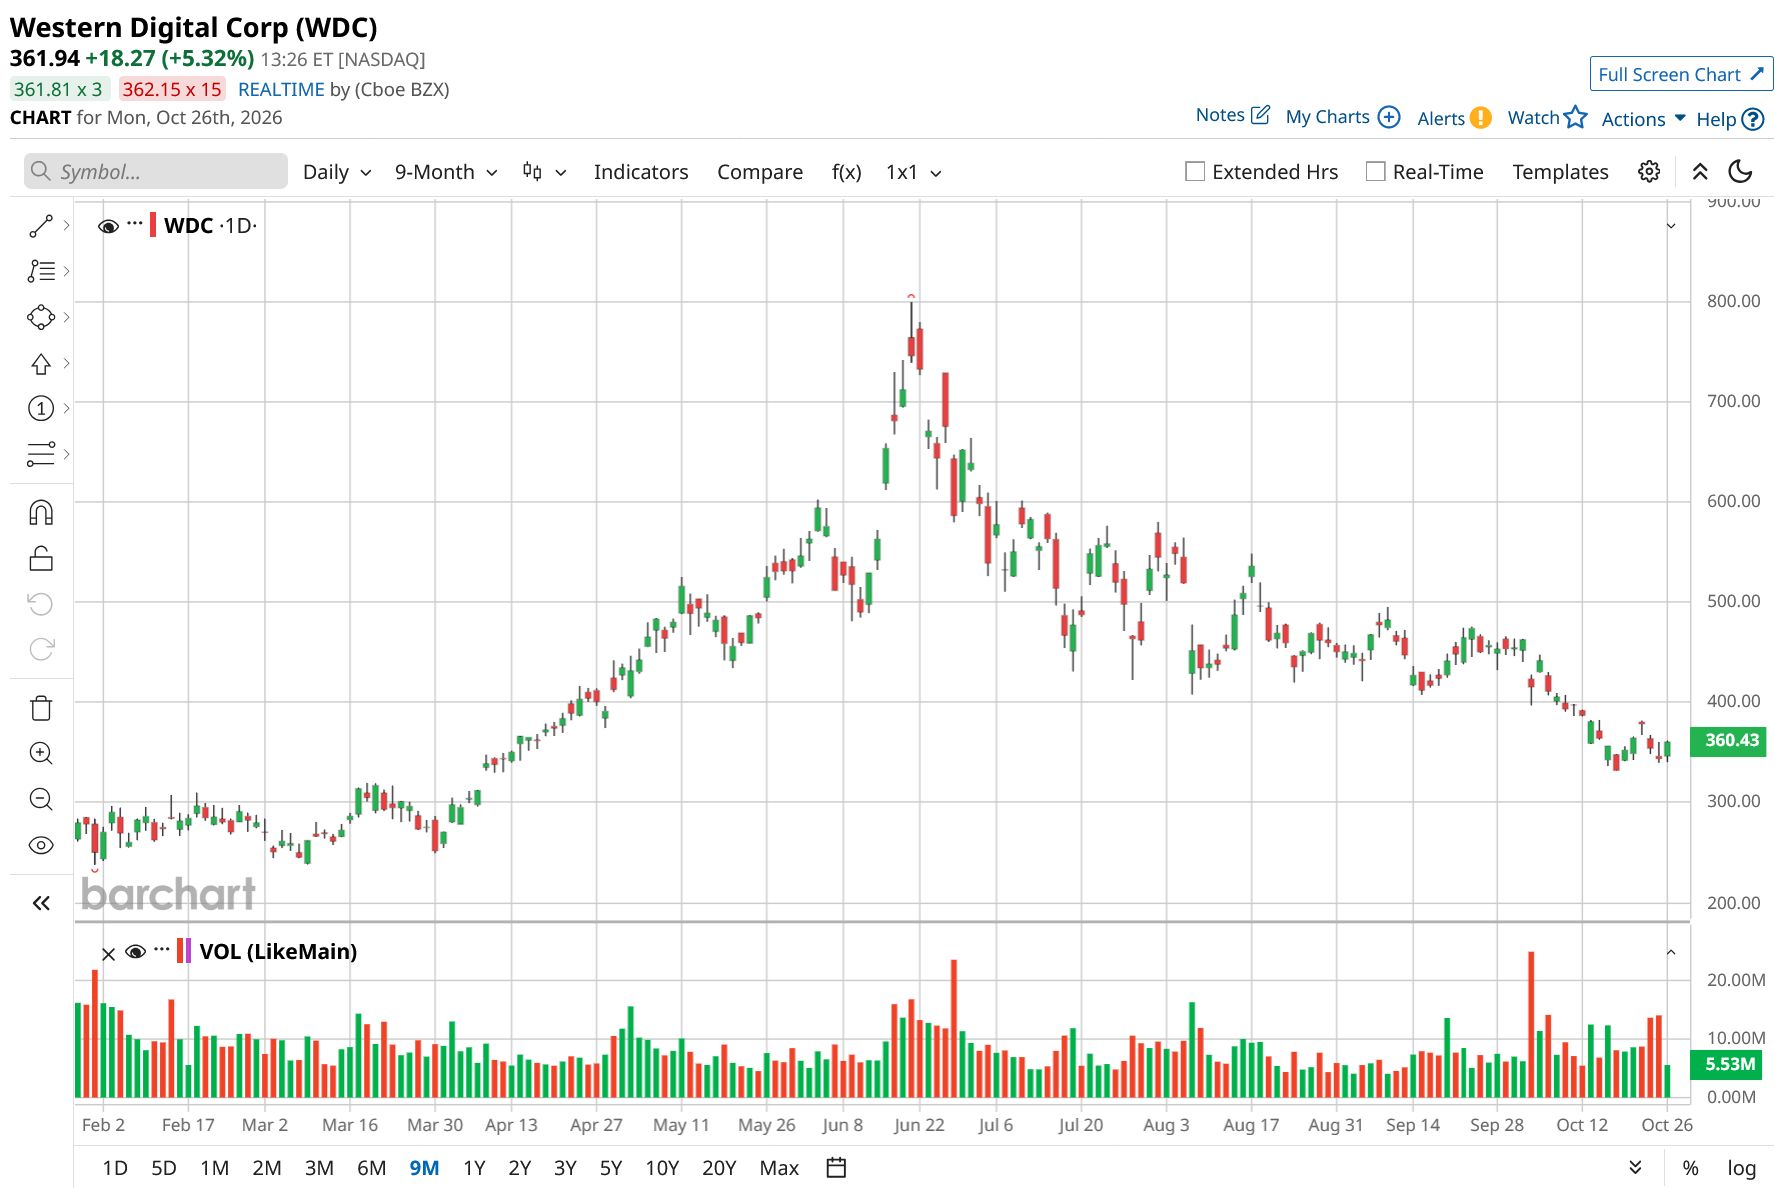
Western Digital (WDC) stock has retreated following a significant rally and is trading about 56% below its 52-week high. The decline reflects profit-taking, concerns about elevated capital expenditure (capex) requirements over the coming years, higher input costs, and the risk that increased competition could expand industry supply and put downward pressure on pricing.
Despite these near-term challenges, WDC’s growth prospects remain solid. Western Digital is likely to deliver strong revenue growth and sustain solid margins, supported by strong demand and pricing power. Furthermore, WDC’s current valuation appears attractive relative to its expected earnings growth.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Taken together, these factors suggest WDC stock is an attractive investment opportunity at its current market price.
 www.barchart.com
Capex and Cost Concerns Are Overblown
Western Digital delivered solid Q1 earnings last week. However, capex and cost concerns weighed on its stock price. These concerns appear overblown, as WDC is likely to benefit from favorable pricing dynamics and an improving product mix.
During its Q1 FY2027 earnings call, management indicated that capex could average 4%–6% of revenue over five years. However, capital spending is expected to exceed this range modestly over the next two years.
Further, WDC is also experiencing higher input costs, particularly for DRAM and NAND components used in its HDDs, amid tight supply-chain conditions. While these pressures could affect near-term margins, the company has several mechanisms to offset their impact.
First, favorable pricing trends are strengthening revenue realization. Long-term agreements (LTAs) include contractual price adjustments, allowing WDC to capture higher pricing as contracts reach scheduled revision periods and customers transition to higher-capacity drives. Additionally, tight supply conditions have supported improved spot pricing among nearline customers without LTAs, alongside better pricing trends in the client and consumer segments.
Second, the ongoing shift toward higher-capacity drives is expected to improve average selling prices (ASPs) and profitability. These products command higher per-unit prices, supporting gross margin expansion.
Third, higher areal density lets Western Digital deliver more exabytes of storage without proportionately increasing the number of drives it manufactures. This improves production efficiency by spreading fixed costs across greater storage capacity.
Overall, higher pricing, a favorable product mix, and higher storage density provide a solid base for sustained gross margin expansion.
Western Digital to Deliver Solid Growth Ahead
Western Digital is well-positioned for continued growth, supported by strong demand for data storage, improving profitability, and favorable pricing dynamics. In Q1, revenue rose 55% year-over-year (YoY), while gross and operating margins expanded to 58% and 49%, respectively. Earnings per share (EPS) surged 161%, and free cash flow reached $1.4 billion.
This momentum is expected to continue as demand for hard disk drives (HDDs) expands beyond traditional cloud and hyperscale customers. Growing adoption across enterprise markets, neocloud providers, and AI-focused research organizations is diversifying WDC’s customer base and improving visibility into long-term demand.
The rapid development of generative AI, inference, and agentic systems is creating substantial volumes of operational logs, model outputs, and performance data that require long-term storage. Meanwhile, physical AI applications, including robotics, industrial automation, and autonomous vehicles, are generating additional data through video and machine-driven processes. These developments will likely support WDC’s growth.
In the near term, Western Digital’s growth is likely to accelerate. Management projects revenue of $5.1 billion in Q2 2027, up 69% YoY, indicating acceleration from Q1. Gross margins will continue to benefit from a favorable pricing environment and increasing sales of higher-capacity drives. EPS is expected to reach $5.80, compared with $2.13 in the prior-year quarter.
Looking ahead, deeper customer relationships, improved demand visibility, and ongoing product innovation should support exabyte supply growth through fiscal 2027 and 2028. Combined with strong cash generation and a solid balance sheet, these factors position WDC to invest in technological advancement while capitalizing on the expanding demand for data storage.
WDC Stock’s Valuation Appears Compelling
WDC stock currently trades at about 18 times forward earnings, suggesting it is undervalued relative to its earnings-growth potential.
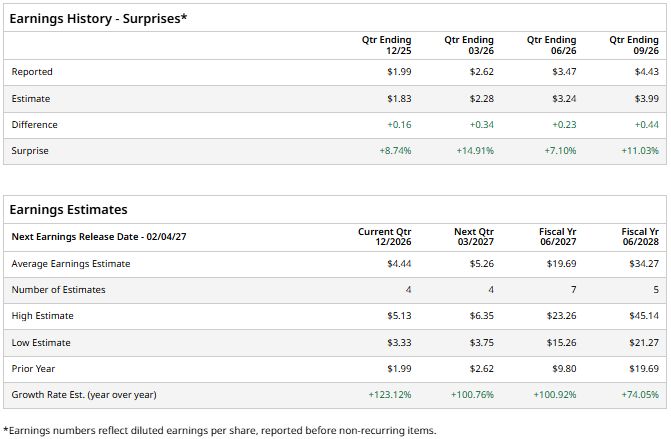
Analysts currently project its fiscal 2027 EPS to double. Moreover, growth is also expected to remain strong in fiscal 2028, with consensus estimates projecting an approximately 74% increase in EPS.
With robust earnings growth anticipated and shares trading at a relatively low valuation, WDC could have further upside.
 www.barchart.com
WDC Stock Is a “Strong Buy”
Western Digital’s strong earnings momentum, supported by favorable pricing dynamics and growing AI-driven storage demand, supports its long-term growth outlook. While elevated capex and input costs pose near-term risks, higher-capacity drives, improving product mix, and increasing storage density should help sustain margin expansion.
Trading at approximately 18 times forward earnings, WDC appears attractively valued relative to its projected earnings growth. Overall, the stock offers compelling upside potential.
And most analysts agree. Of the 25 covering WDC stock, 18 rate it a “Strong Buy.”
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Lumentum Just Scored a New 'Buy' Rating. Here's Why. Meta Stock Alert: Meta: The $25 Billion Legal Blow Investors Cannot Ignore A $95 Billion Reason Why META Stock Is in Focus Today How to Play Amazon Stock Before Q3 Earnings as the AI Trade Flounders