

An American fabless semiconductor company, Ambarella (AMBA), suddenly becomes the most interesting stock in edge AI. On Oct. 21, a post from Betaville suggested Nvidia (NVDA) could be the third party to buy the edge-AI chipmaker, after NXP Semiconductors (NXPI) and Qualcomm (QCOM).
The company was said to be getting the same advice from Goldman Sachs, which was also reportedly looking at a potential sale, but there has been no official bid, price, or deal announced.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The impression of strategic logic appears to be correct: Ambarella offers low-power processors that, for example, analyze video and operate AI in cars, cameras, or robotics applications, while Nvidia would appear to be the leader in AI computing in data centers.
The acquisition of Ambarella could expand Nvidia's reach in physical AI and edge computing. Now unless a serious offer materializes, or if the talks go stale, those rumored gains could disappear just as fast as they came.
While investors might be tempted to be drawn into a possible bid, a more important question is whether Ambarella can generate yet more revenue and cash flow to support this valuation without being simply taken over.
A Rough Year for AMBA Stock
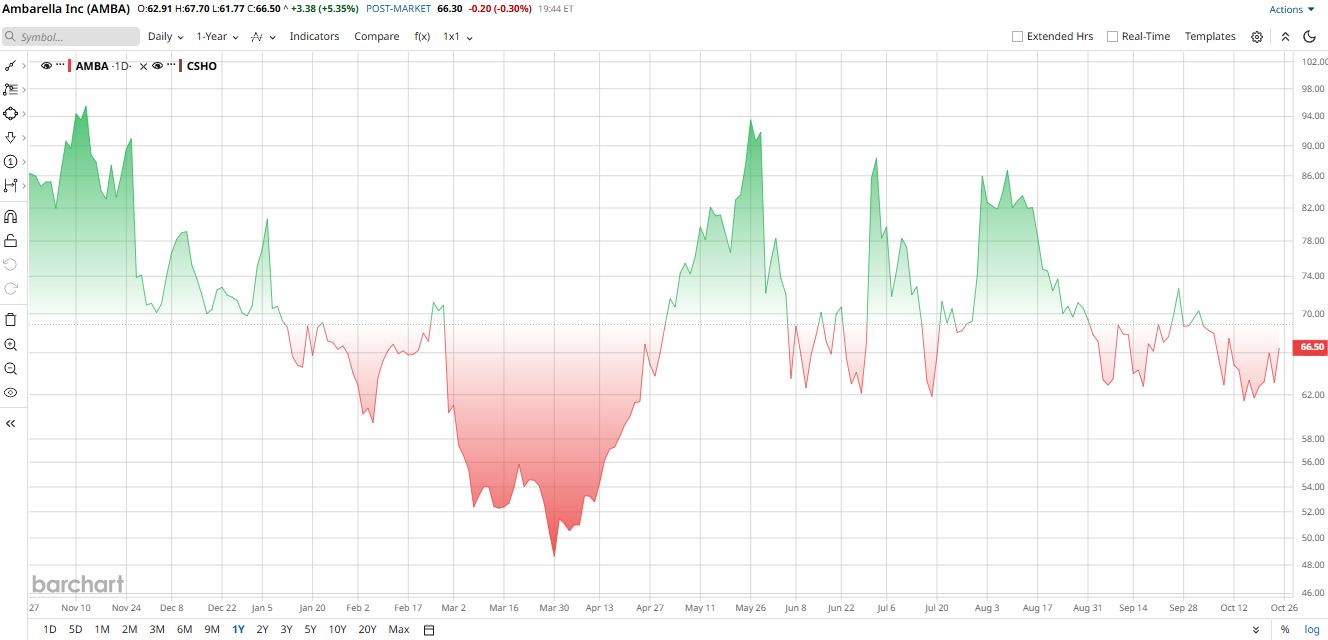
AMBA stock is down 6% year-to-date (YTD) in 2026, and it is down roughly 31% from its 2026 high. The stock rallied about 8% in late October on the Nvidia rumor, but that pop did not erase the earlier losses.
The negative catalysts were slow X7 adoption and margin pressure from rising memory costs. The positive catalyst is the buyout interest from three credible suitors. Without the M&A bid, the stock would likely be much lower.
Turning to valuation, Ambarella trades at a price-to-sales (P/S) ratio of 6x. That is below its own historical median of 8x and below the semiconductor industry median. The forward price-to-earnings (P/E) ratio is 81.97. That looks expensive. But it reflects a depressed earnings base. On sales, the stock looks fairly valued on the slightly cheap side. On earnings, it is expensive. The market is pricing in a lot of future growth.
 www.barchart.com
Why Nvidia Makes Sense as a Suitor
So the chip giant Nvidia is reportedly interested in the acquisition of Ambarella, with Goldman Sachs on board for the deal. Ambarella is the tech company that specializes in low-power AI chips for cameras, cars, and robots. That's the tangible aspect of AI. Currently, AI training in the data center is dominated by Nvidia. By acquiring Ambarella, Nvidia will gain a better position in the field of AI inference in actual devices.
Being the third bidder in the process, and the one with the largest purse, also increases the chances of getting a better deal. Theoretically, it is a good strategy. However, it is all still just a rumor. Traders are betting on a maybe and not something even remotely set in stone. This is why AMBA stock is still trading well below its YTD level despite the rally.
After that is the newest big move: the launch of the X7 AI accelerator. Ambarella announced the X7 on Sept. 15, 2026. It is designed for edge infrastructure and is extremely power-efficient and memory-consuming. It's also entered into seven-year distribution deals with Macnica and Capgemini (CGEMY). The opportunity from those deals would drive up to $500 million in incremental revenue over seven years. The moves illustrate that Ambarella has a larger enterprise going on the buyout side. The distribution deals expand the moat.
Q2 Was a Record Quarter
Ambarella's fiscal second quarter of 2027 reported solid growth due to higher demand for its edge AI chips in the automotive and Internet of Things (IoT) segment.
Revenue increased by 13% over the prior-year figure to $108.1 million and above management's guidance as well. Solid sales of commercial vehicles and edge artificial intelligence revenue helped handily. The enterprise IoT segment also performed better than the consumer-focused segments.
Profitability went up as well. Ambarella registered a net loss of $6.7 million, compared to a $20 million loss a year ago. Adjusted net income was $8.2 million, or $0.18 per share, in the current quarter compared to $8,200,000, or $0.15 per share, for the same quarter last year.
But the free cash flow was negative at $7.1 million. At the end of the quarter, the company had $272.3 million in cash and marketable securities for financial flexibility as the company started to invest in new products.
CEO Fermi Wang was upbeat. “Our edge AI revenue reached record levels in Q2, with balanced sequential growth in Auto and IoT markets,” he said. He also highlighted the X7 launch and the new distribution deals.
For the coming fiscal 3Q results, Ambarella is forecasting $115 million to $124 million in revenue and gross margins from 59% to 60%. Analysts are estimating fiscal 2027 revenue at about $440.6 million and adjusted earnings per share at a loss of $1.12, so higher revenue can be expected if sales demand continues.
Wall Street Is Split on AMBA Stock
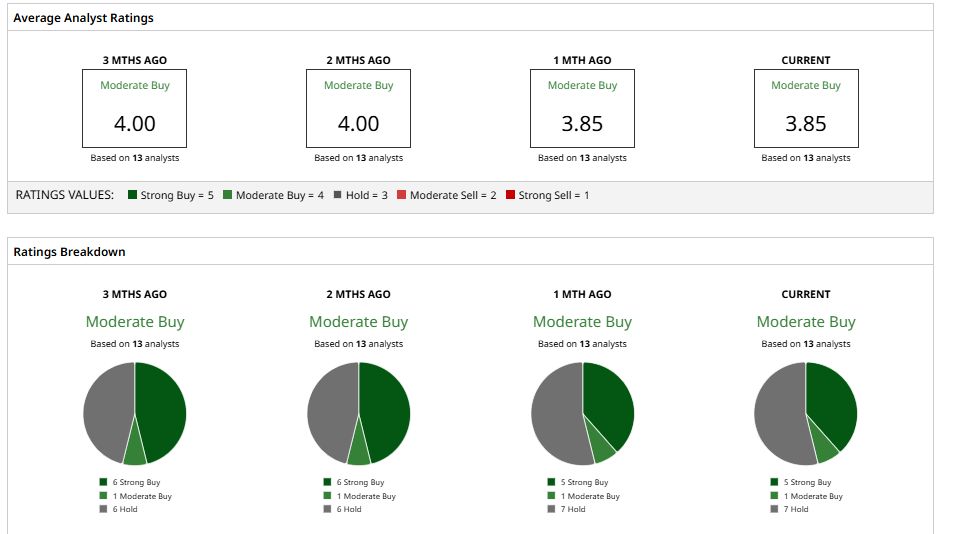
Wall Street opinion towards AMBA stock is generally mixed but leaning positive. Morgan Stanley analyst Joseph Moore has a “Buy” rating and a $96 price target. Roth Capital cut its target to $65 with a “Neutral” rating. Bank of America lowered its target to $70 with a “Neutral” rating.
The consensus rating among 13 analysts is “Moderate Buy.” The mean price target is nearly $90, implying about 35% upside from the current price.
Summing it all up. I think the stock is considered binary risk. A buyout may result in a premium. In the absence of an agreement, the stock may revert to a loss-making estimate. As one analyst said, “…there is a two-way risk for investors here, either a premium on the deal, or the valuation hitting loss warrant levels.” This is the debate in a nutshell.
Currently, the only thing that's seriously driving AMBA stock is the buyout chatter. However, the core business is improving. The investors who purchase AMBA are now hoping there will be a deal. They are also taking a keen bet on the edge AI story continuing to go up. Either wager is a winner. Neither is guaranteed.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.