

Lumentum (LITE) is sold out of optical components through early 2029, according to CEO Michael Hurlston. Hurlston said the company could not meet about 70% of demand for certain products through 2027. In my view, Lumentum does not need to prove that artificial intelligence (AI) networking demand exists. It needs to produce enough components to serve that demand.
Lumentum's main advantage is that it sits on a scarce input: The lasers that power AI data-center optics. Its electro-absorption modulated lasers (EMLs) are in a supply crunch, helping the company with pricing power and margin expansion. This supply shortage also spreads across the company’s continuous wave and ultra-high-power lasers. The best part about Lumentum is that demand for its lasers will seemingly always be there, whether the industry moves toward pluggable modules, near-packaged optics, or co-packaged optics.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Released on Aug. 11, Lumentum’s fiscal fourth-quarter results show how the company is already benefiting. Revenue surged 109% year-over-year (YOY) to $1.01 billion in Q4, while non-GAAP operating margin rose to 36.6% from 15% a year earlier. Management also guided Q1 fiscal 2027 revenue to $1.225 billion to $1.275 billion. This shows that the company is benefiting from both higher sales and improved efficiency. If Lumentum expands production without a similar increase in operating costs, the company could boost profits. Moreover, its 1.6T transceivers and optical circuit switching products offer additional growth opportunities.
About Lumentum Stock
Lumentum provides optical and photonic products, from components like lasers to systems spanning cloud transceivers and optical circuit switches. In recent years, the firm has become a crucial backbone of the global AI boom. Founded in 2015, the company is headquartered in San Jose, California.
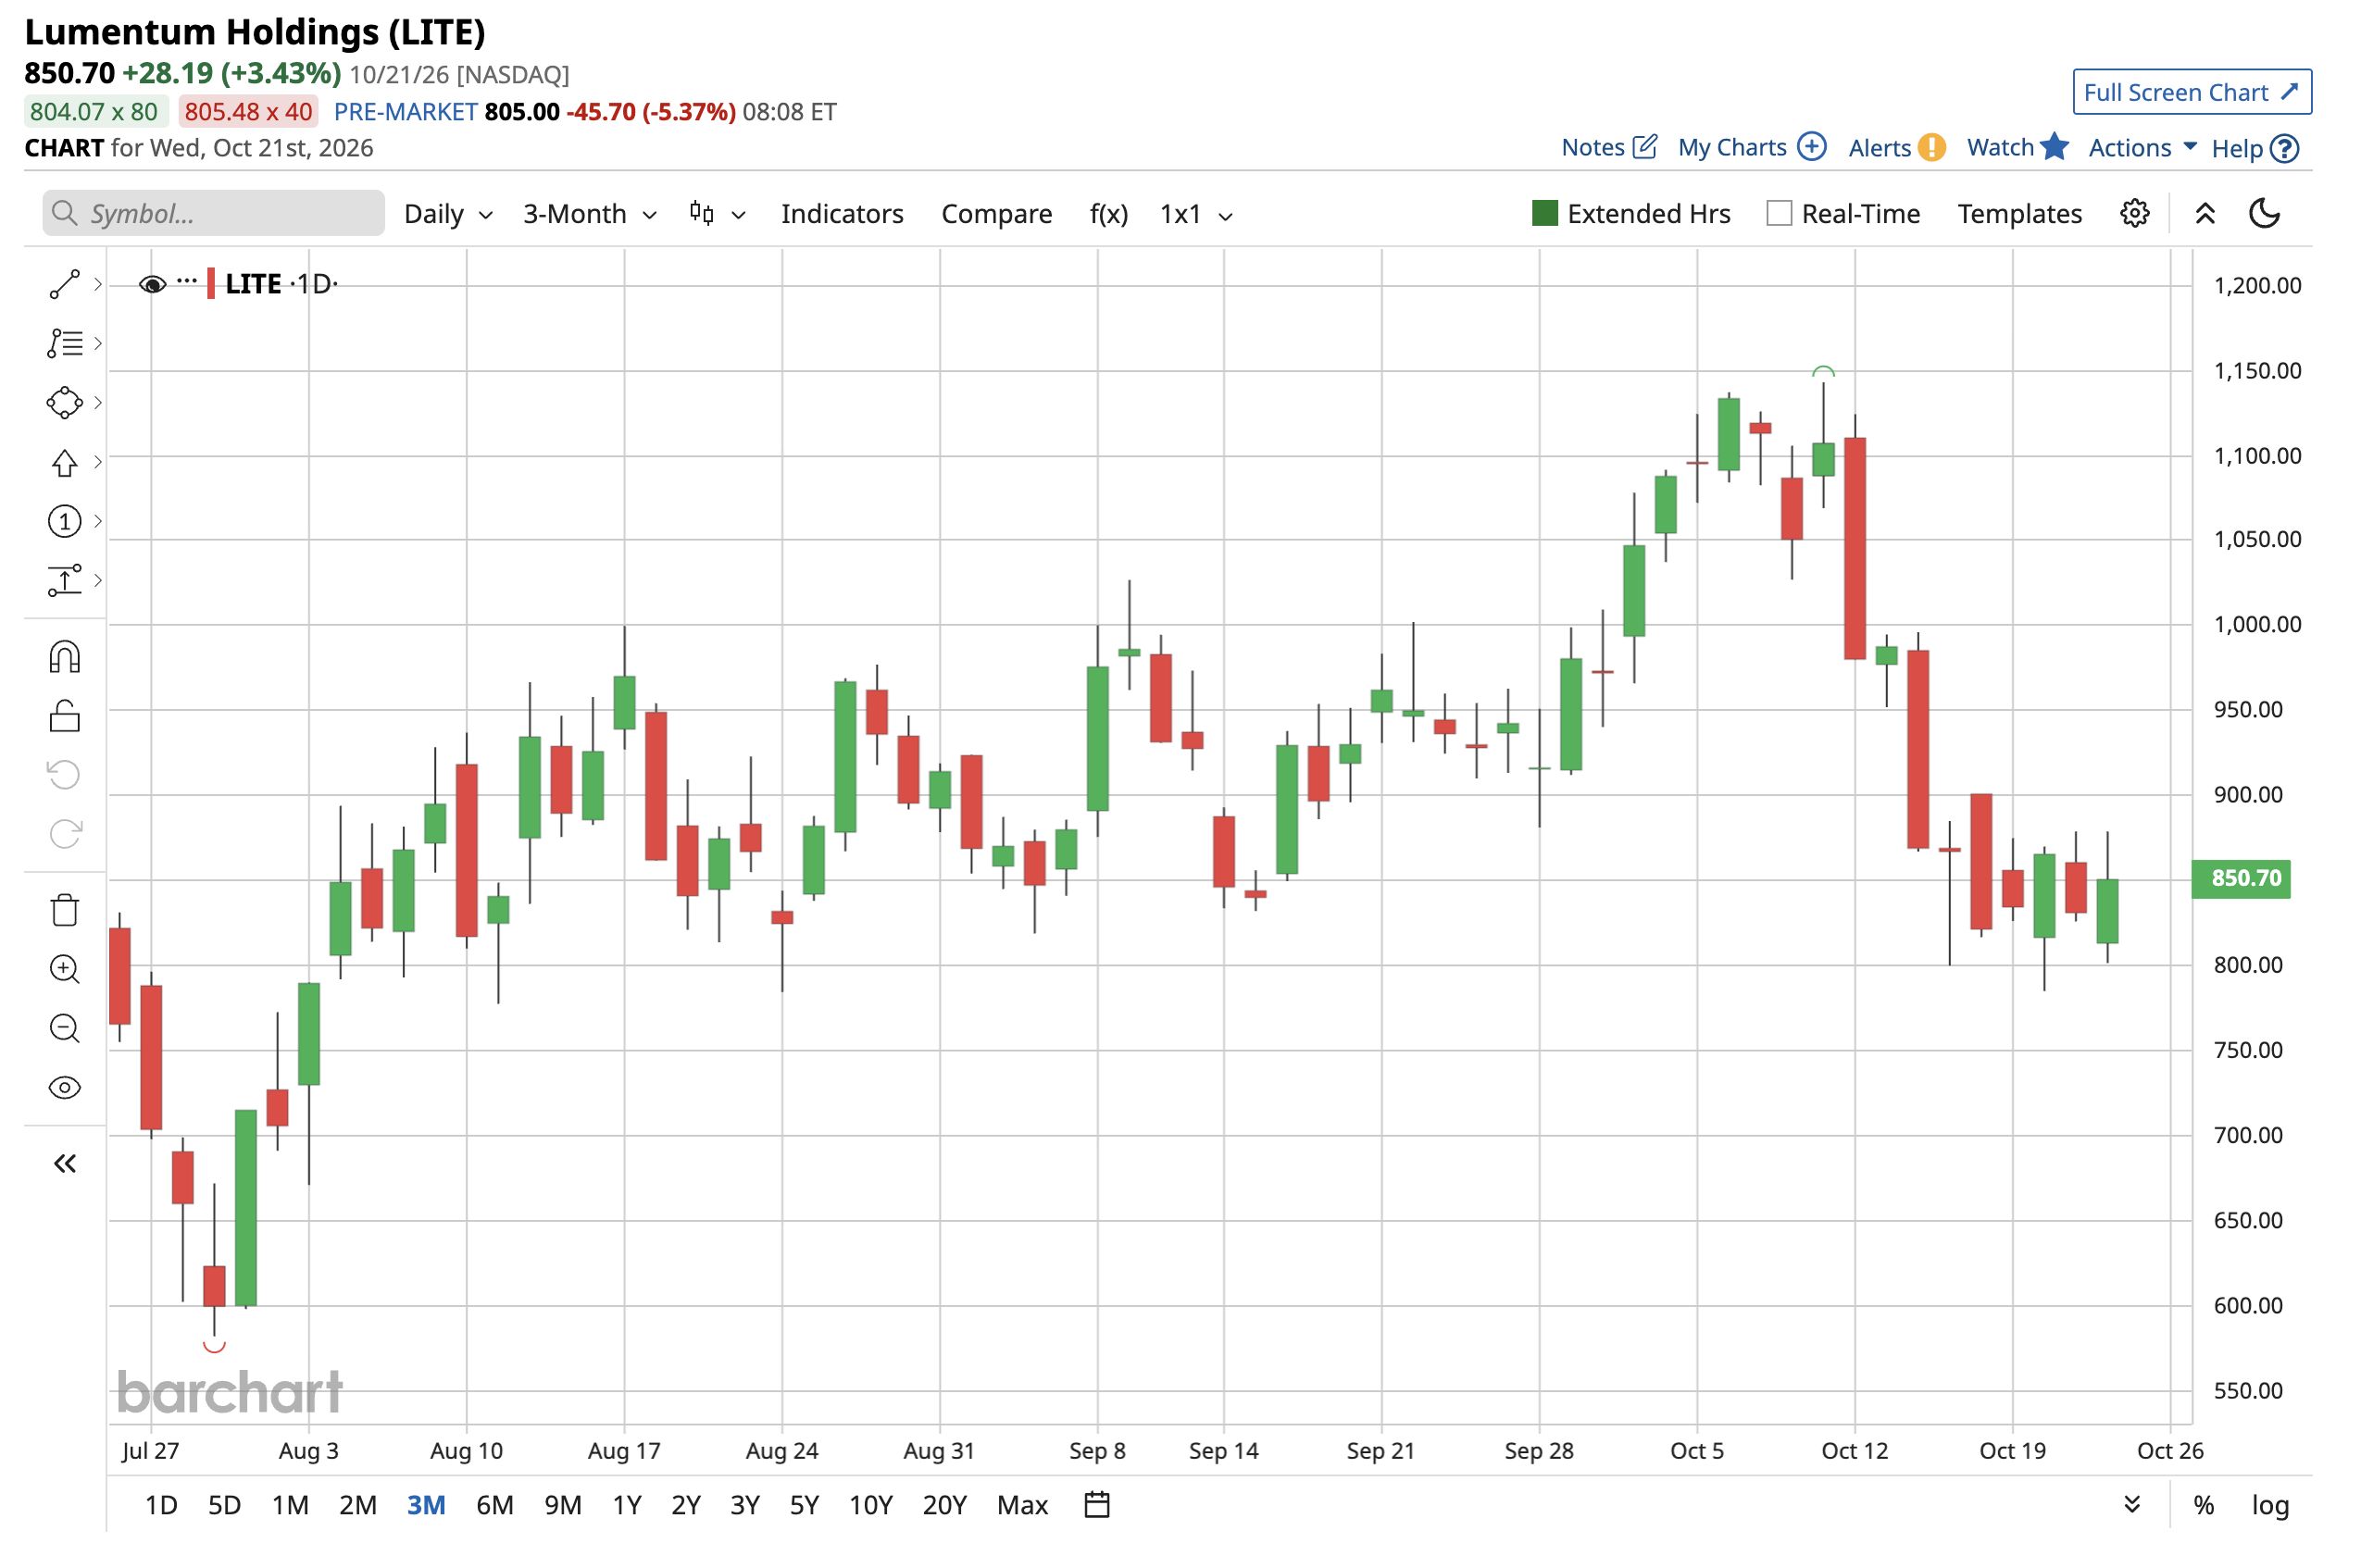
LITE stock has soared in 2026, up 122% year-to-date (YTD) as investors have poured into companies benefiting from surging AI infrastructure spending. The bull rally has been led by demand for optical elements to link larger clusters of high-speed GPUs. But AI stocks also have become fairly volatile. After trading near $602 at the end of July, LITE stock rallied to a high of $1,143 on Oct. 9, then fell to the $800 mark within a week. LITE stock now trades at roughly $818 per share. In contrast, the iShares U.S. Telecommunications ETF (IYZ) has climbed only 14% YTD.
 www.barchart.com
Is the Valuation Still Reasonable?
Lumentum stock trades at a forward price-to-earnings (P/E) ratio of 38 times, almost in line with its five-year average of roughly 37.5 times. However, its price-to-sales (P/S) ratio of 22.6 times is well above its five-year average of about 5.4 times.
This premium reflects the growth investors expect from the company as AI infrastructure spending drives demand for optical components. Analysts expect EPS to grow 143% in fiscal 2027 and another 67% in fiscal 2028. If these forecasts materialize, strong earnings growth could make the current valuation more reasonable. However, Lumentum still needs to expand production and turn its unmet demand into actual sales. Any delays or weaker-than-expected growth could put pressure on LITE stock.
Lumentum’s Earnings and Growth Drivers
The latest quarterly results give investors plenty to cheer. In Q4, the company reported revenue of $1.01 billion, up 109% YOY and ahead of Wall Street’s $988 million estimate. The increase was widespread throughout the company. Components revenue grew 103% YOY to $649.4 million, while Systems revenue increased 123% YOY to $356.9 million.
Profitability also improved, as gross margin climbed to 50.4% and the operating margin increased to 36.6%. On the balance sheet, free cash flow amounted to $196.2 million, while the company accumulated about $2.7 billion in cash and short-term investments by the end of the period, providing further financial flexibility.
Management anticipates the trend to persist through fiscal 2027. Lumentum is projecting an increase of more than $150 million in sales for Q1, along with gains in profitability. Revenue for the period is expected to be $1.225 billion to $1.275 billion, while adjusted EPS is projected to range between $4.05 and $4.35. CEO Michael Hurlston said that about half of the expected revenue growth will come from its components business, while the rest will come from 1.6T transceivers and faster deliveries of optical circuit switches.
What Do Analysts Expect for LITE Stock?
Analysts remain bullish after the latest earnings report. Stifel recently raised its price target from $1,100 to $1,232 and kept a “Buy” rating on shares. Meanwhile, Bernstein analyst Daniel Zhu has a “Buy” rating and a price target of $1,220 for LITE stock.
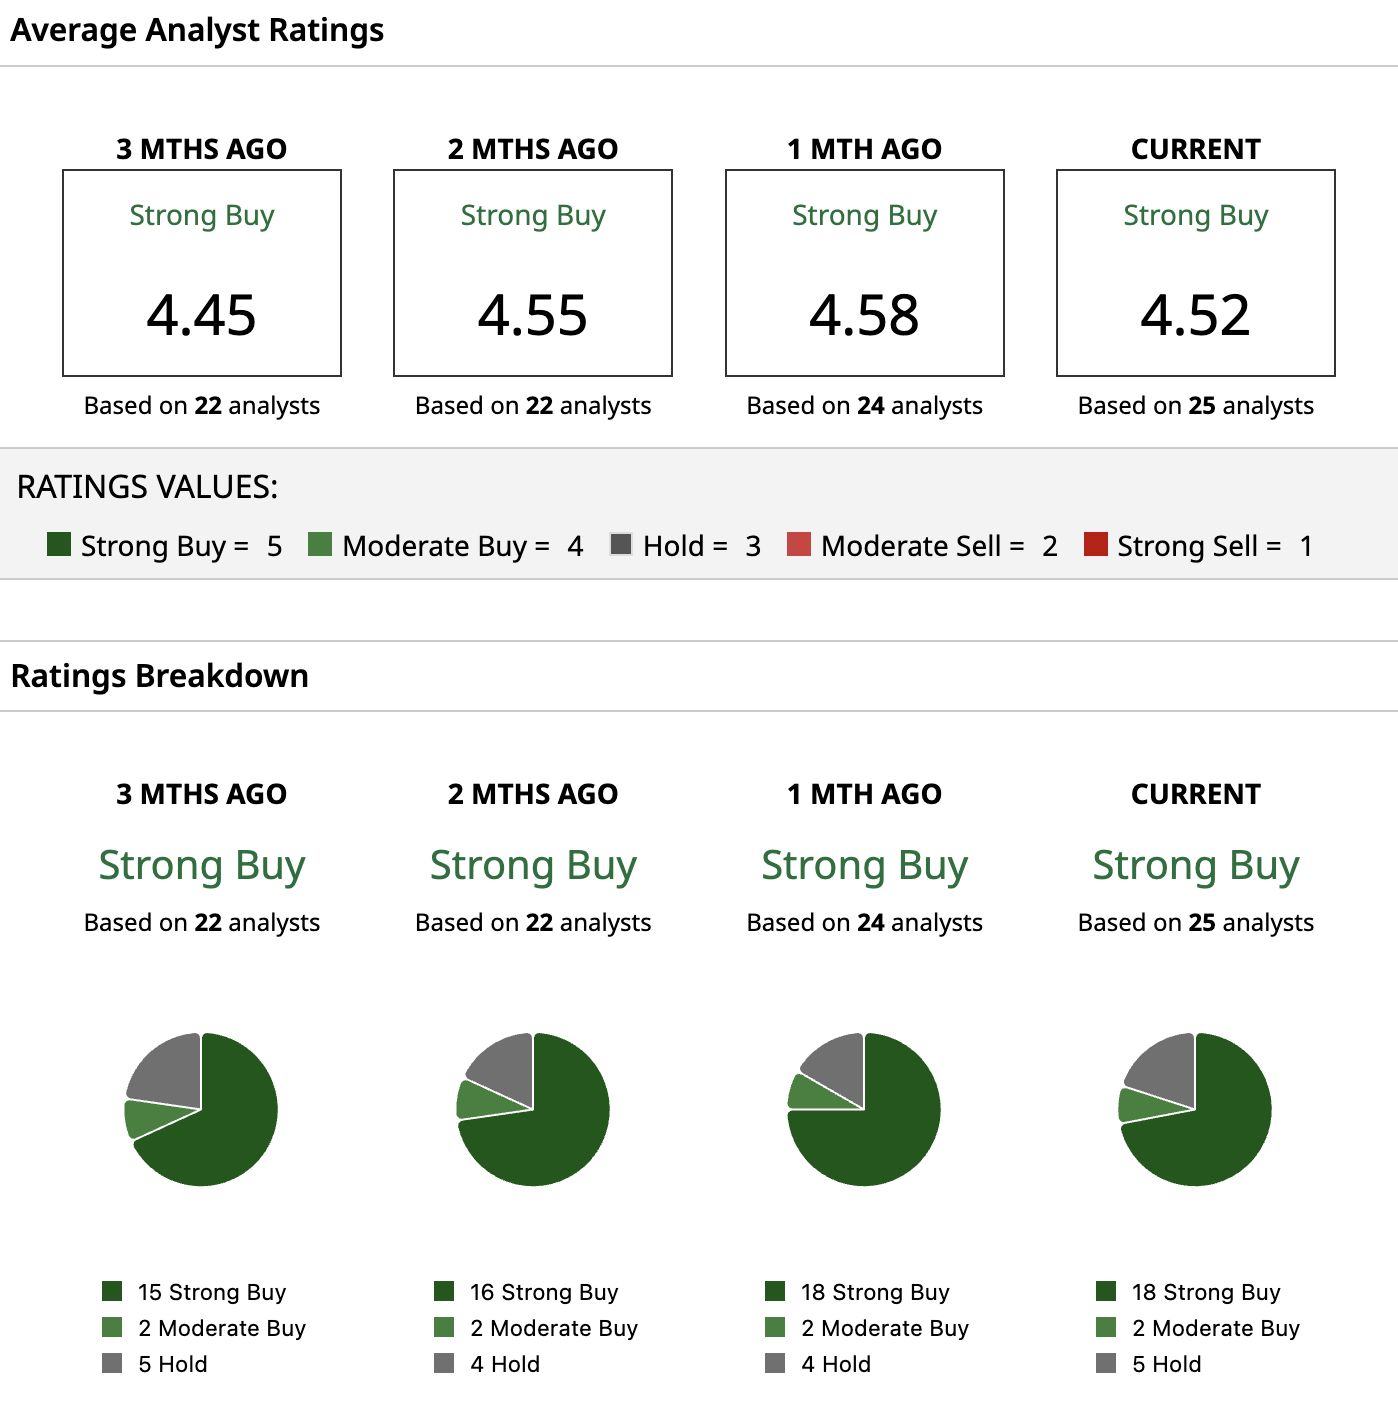
Overall, LITE stock holds a consensus “Strong Buy” rating from 25 Wall Street analysts with coverage. The mean price target of $1,169 reflects 43% potential upside from current levels, while the Street-high price target of $1,500 implies potential upside of 83% from here.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Lumentum Is Sold Out Until 2029. Is LITE Stock Still a Buy at $800+? Ahead of SoFi Earnings, Here's What Barchart Data Says Comes Next for SOFI Stock Anthropic Revenue Exploded 1,368%. Here’s Why I’m Not Buying the IPO Yet A $6 Billion Reason Why SGRY Stock Is Soaring Today