

Akamai Technologies, Inc. (AKAM), headquartered in Cambridge, Massachusetts, provides security, delivery, and cloud computing solutions. Valued at $14.2 billion by market cap, the company provides services for accelerating and improving the delivery of content and applications over the internet, ranging from live and on-demand streaming video capabilities to conventional content on websites, to tools that help people transact business and reach out to new and existing customers. The cybersecurity and cloud computing company is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Thursday, Nov. 5.
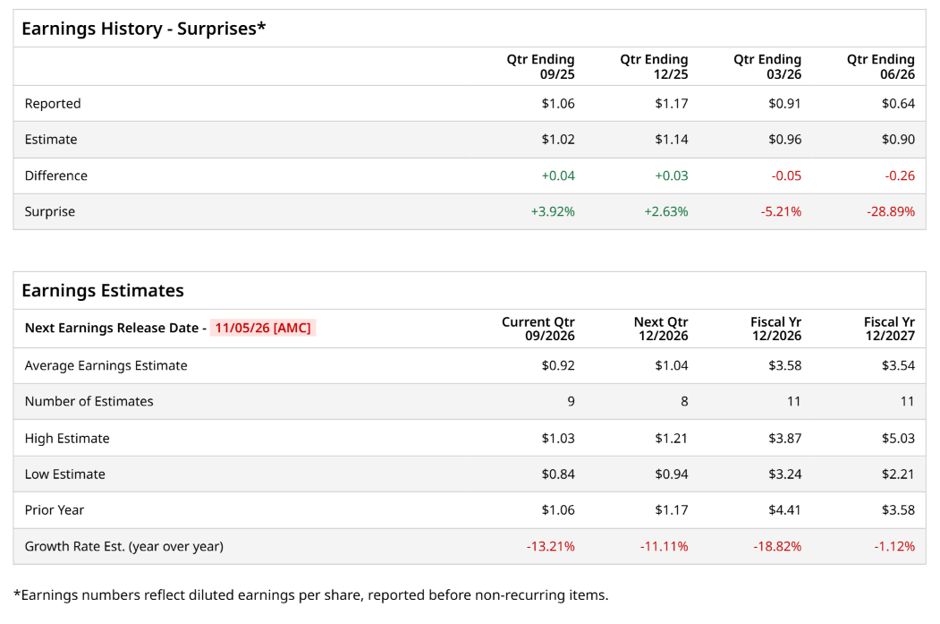
Ahead of the event, analysts expect Akamai Technologies to report a profit of $0.92 per share on a diluted basis, down 13.2% from $1.06 per share in the year-ago quarter. The company beat the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Akamai Technologies to report EPS of $3.58, down 18.8% from $4.41 in fiscal 2025. Its EPS is expected to fall 1.1% year over year to $3.54 in fiscal 2027.
 www.barchart.com
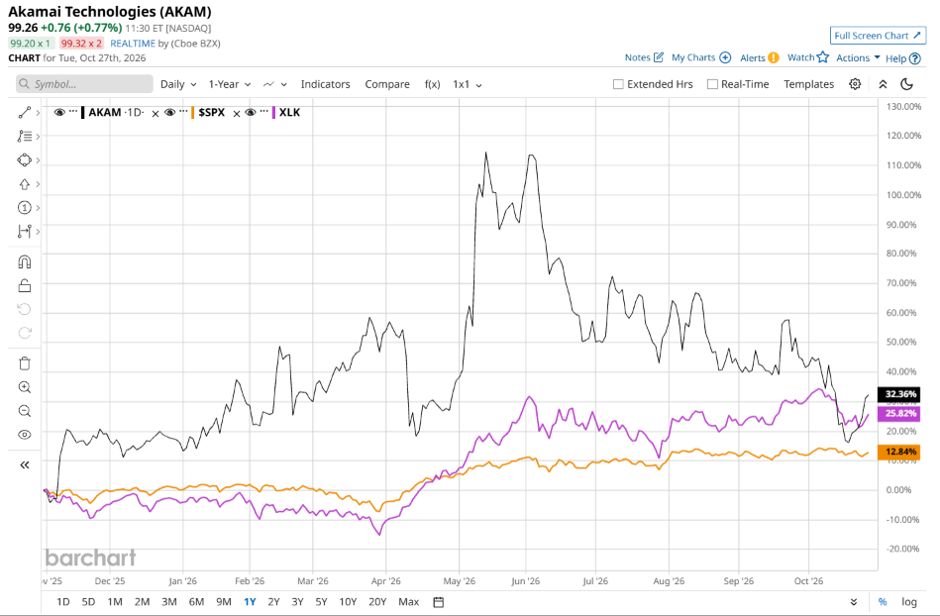
AKAM stock has outperformed the S&P 500 Index’s ($SPX) 13% gains over the past 52 weeks, with shares up 30.8% during this period. Similarly, it outperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 26% gains over the same time frame.
 www.barchart.com
AKAM's outperformance is driven by its emergence as a major player in enterprise AI infrastructure, headlined by a landmark $11.6 billion multi-year cloud agreement with Anthropic. This momentum is supported by robust hardware supply chain deals with Lenovo Group Limited (LNVGY) and Jabil Inc. (JBL) to secure custom server capacity, alongside strong ongoing demand in cloud computing and cybersecurity, highlighted by high-profile customer wins like CrowdStrike Holdings, Inc. (CRWD) and a separate $600 million U.S. tech contract.
Analysts’ consensus opinion on AKAM stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 21 analysts covering the stock, 13 advise a “Strong Buy” rating, seven give a “Hold,” and one recommends a “Strong Sell.” AKAM’s average analyst price target is $155.55, indicating a notable potential upside of 56.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ray Dalio Gave the U.S. 3 Years Before a Debt ‘Heart Attack.’ 19 Months Later, Here’s the Scorecard. Google Just Solved a Major Quantum Computing Problem. Here’s Why Investors Still Have a 10-Year Wait. Micron Just Rejected a Technology Its Biggest Rivals Are Chasing. Here’s Why. AMZN Stock: 3 Reasons Why Amazon Could Deliver Solid Growth in Q3