

It’s remarkable to think that Amazon (AMZN), once just an online bookseller, now counts cloud computing among its most powerful ventures. Today, Amazon Web Services (AWS) is the world’s largest cloud infrastructure provider, and its rapid growth is giving investors another reason to pay attention. Amazon is doubling down on AI, and several Wall Street analysts see an increasingly attractive opportunity ahead of Q3 earnings on Oct. 29.
Can another strong quarter boost Amazon stock?
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
AWS Is Booming, and Analysts Expect Much More in Q3
Amazon is winning more cloud business than ever, fueling Wall Street’s optimism. In the second quarter, AWS revenue soared 36.7% year-over-year (YoY) to $42.2 billion, marking its most rapid growth in 18 quarters. AWS began as a cloud computing powerhouse, but AI is now unlocking fresh waves of demand, from model training to powering production inference. CEO Andy Jassy noted that as customers ramp up their AI efforts, they are also deepening their trust in AWS’s core cloud offerings.
AWS's financial opportunity is extraordinary. Its annualized revenue run rate reached $169 billion. Amazon’s AI and custom-chip businesses also achieved annual revenue run rates exceeding $25 billion each, both growing at triple-digit rates YoY. Backlog also reached $496 billion in Q2. What’s truly fascinating is Amazon’s strategy of cultivating multiple growth engines within AWS, instead of betting everything on a single AI product. This diverse approach is fueling analysts’ optimism for yet another standout quarter.
Bank of America analyst Justin Post expects AWS revenue growth of 40% YoY, above the 38% consensus estimate. He cites new capacity, price increases, AI Lab contracts, and rising enterprise inference demand as drivers of the upside. He also expects AWS operating margins of 39%. Similarly, BNP Paribas analyst Nick Jones expects AWS growth of 43% to 45%, well above consensus estimates. Wells Fargo expects AWS growth to accelerate in the fourth quarter and believes Amazon could deliver operating income guidance near the high end of Wall Street expectations. It also expects Amazon to maintain its 2026 capital expenditure forecast of $220 billion.
Meanwhile, Cantor Fitzgerald anticipates not only accelerating cloud growth and robust operating margins but also looks to management’s upcoming commentary to strengthen confidence in the lasting power of AI demand.
The Biggest Concern: Can Amazon Justify Its AI Spending?
These soaring expectations have raised the bar for Amazon, forcing the company to build out data centers, servers, and networking gear at scale while racing to secure enough power to keep up with demand. The bulk of this spending is happening now, squeezing free cash flow long before the new infrastructure can pay off. In the second quarter, Amazon generated $45.4 billion in operating cash flow. But free cash flow came in negative $7.6 billion for the 12 months ended June 30, owing to higher capital spending.
Amazon is still on track to pour about $220 billion into cash capital expenditures this year. Jassy explained that these bold infrastructure investments are meant to pay off over the long haul, not just in the next quarter. He noted that Amazon expects its servers and networking gear to recoup their costs in just under three years, even though the equipment can remain in service for five to six years or longer. Data centers offer an even longer investment horizon of more than 30 years.
Yet investors are hungry for proof. If cash generation stays steady while AWS expands and operating margins remain robust, it would clearly show that Amazon's AI investments fuel lasting value, not just increase capital demands. The risk is that investors may have to wait longer than expected for those returns.
The Bottom Line on AMZN Ahead of Q3 Earnings
Goldman Sachs spotlighted Amazon on its Conviction List ahead of earnings, noting that falling valuations have made leading tech stocks even more appealing as earnings keep climbing. Morgan Stanley, too, now ranks Amazon among its top picks. Many analysts think that even with high spending, the payoff from Amazon's data center investments could be well worth the patience. As a result, they see Amazon as a compelling buy at today's valuation. The stock currently trades at 19 times projected 2026 earnings, which are forecast to soar by 80%. However, they also argue that investors' concerns about financing AI investments could weigh more on the stock now than another impressive earnings report.
Finally, capital spending stands out as the main risk. Even robust earnings might not lift the stock if investors start doubting the payoff from AI infrastructure.
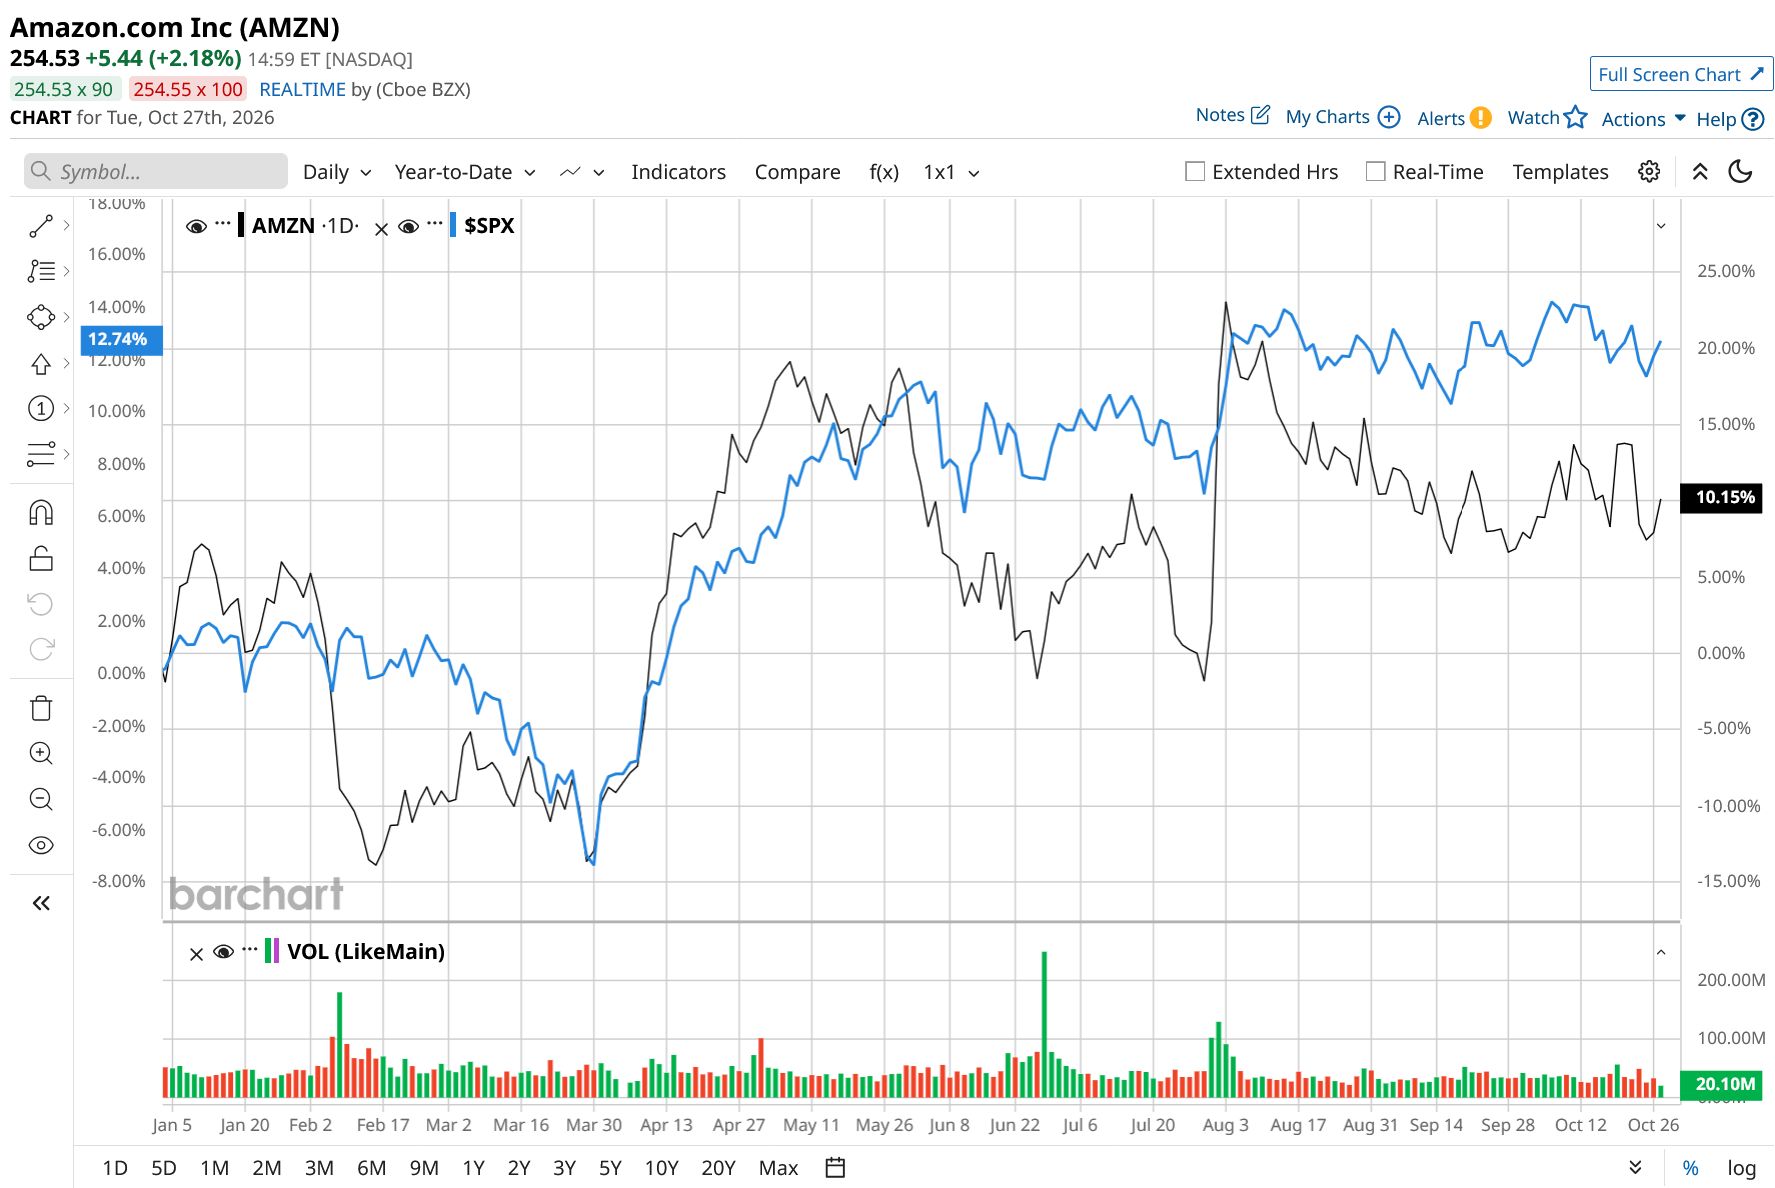
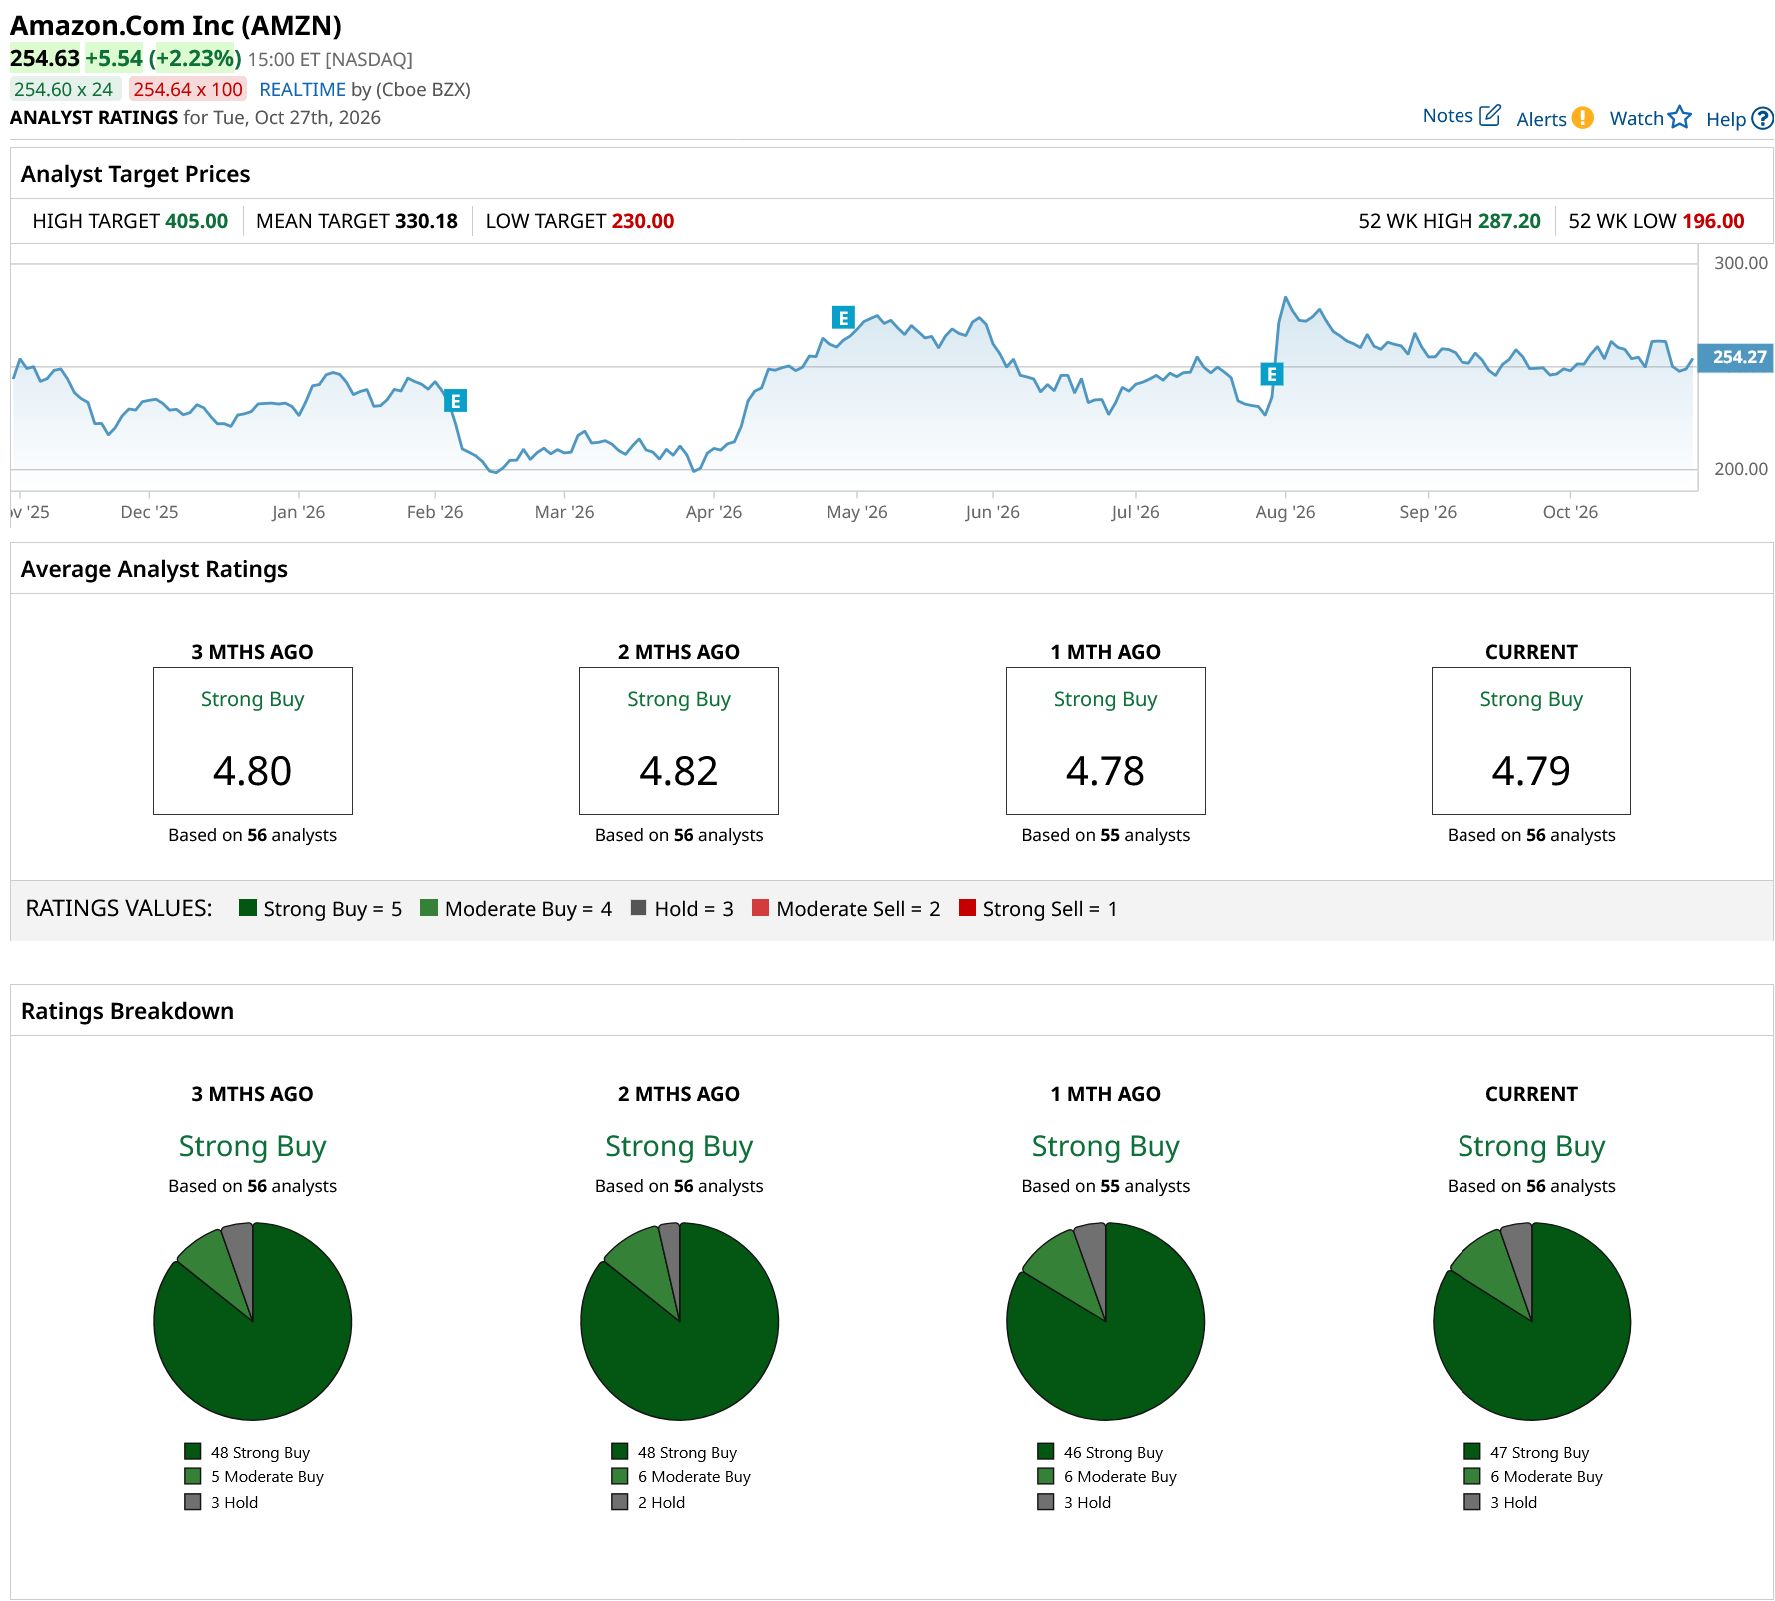
AMZN stock has climbed roughly 10% so far this year. Analysts project it to climb another 29% from current levels, based on its average target price of $330.18. Its high price estimate of $405 suggests 59% upside. On Wall Street, Amazon has a consensus “Strong Buy” rating. Of the 56 analysts covering the stock, 47 have a “Strong Buy,” six have a “Moderate Buy” rating, and three have a “Hold.”
 www.barchart.com
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Amazon Stock: Wall Street Says AMZN Looks Increasingly Attractive Ahead of Q3 Earnings A $1 Billion Reason to Consider Buying the IBM Stock Dip MSFT Stock Alert: What to Know as Microsoft Offers Buyouts to 60,000 Employees Barclays Layoffs: How to Play BCS Stock Amid 5,000 New Job Cuts